- Author: Raymond
- Category: Product Liability Insurance
Product Liability Insurance in Kenya: Complete Guide for Manufacturers, Distributors & Retailers
Discover everything about product liability insurance in Kenya. Learn coverage, costs, legal requirements under the Consumer Protection Act, who needs it, and how to protect your business from product-related claims.
In Kenya’s growing manufacturing, retail, and import sectors, a single defective product can trigger costly lawsuits, compensation claims, and reputational damage. Product liability insurance in Kenya provides essential protection against these risks.
This guide explains what product liability insurance covers, why it matters under Kenyan law, who needs it, typical costs, exclusions, and practical steps to secure the right policy.
What Is Product Liability Insurance?
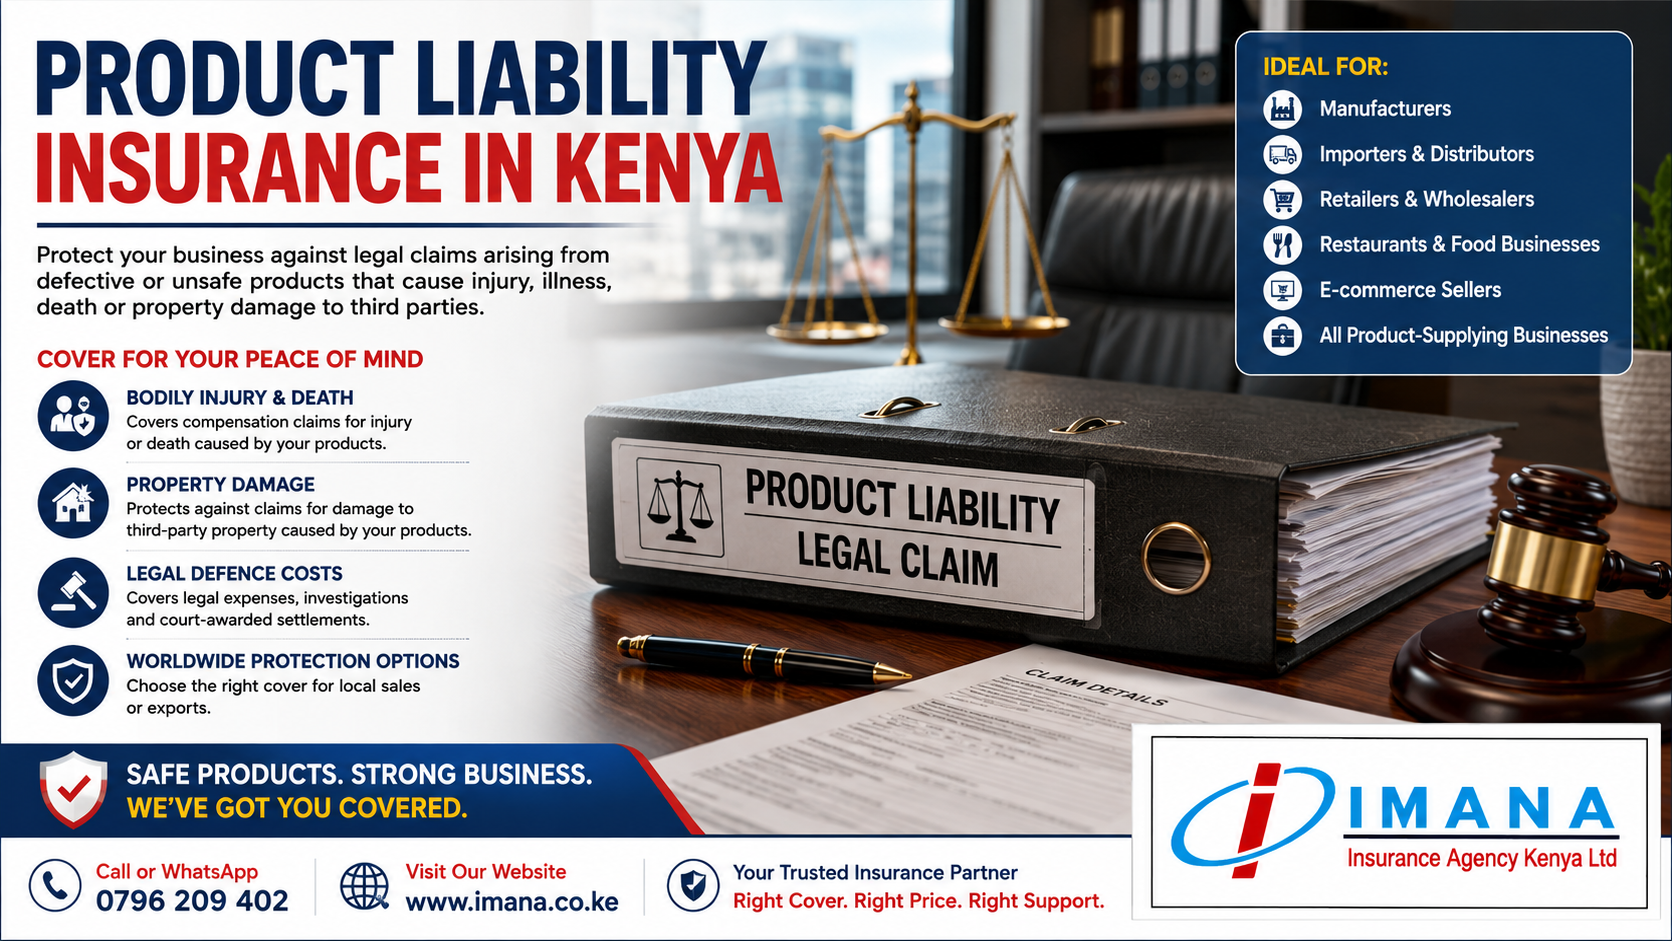
Product liability insurance protects businesses against legal liability arising from products they manufacture, assemble, process, modify, repair, service, label, sell, supply, or distribute. Coverage applies once the product has left the insured’s custody or control.
It typically responds to claims for:
- Accidental death, bodily injury, or illness to third parties
- Accidental loss of or damage to tangible property
caused by something harmful or defective in the product (or its container/packaging).
The policy usually covers compensation awarded to claimants plus legal defence costs and related expenses incurred with the insurer’s consent.
Legal Framework for Product Liability in Kenya
Kenya has no single comprehensive product liability statute. Liability arises from several overlapping laws:
- Consumer Protection Act, No. 46 of 2012 – Strengthens consumer rights and enables individual or class claims for loss or damage caused by defective products.
- Sale of Goods Act – Imposes obligations on sellers regarding quality and fitness for purpose.
- Constitution of Kenya, 2010 – Supports consumer protection principles.
- Competition Act, No. 12 of 2010 – Addresses unfair practices that can relate to product safety and marketing.
Liability can extend along the supply chain to manufacturers, component suppliers, importers, distributors, wholesalers, and retailers. Claims may be based on manufacturing defects, design defects, or inadequate warnings/instructions. In some cases, strict liability principles apply, meaning fault may not need to be proven if the product is defective and caused harm.
Although product liability insurance is not legally mandatory for most businesses, many retailers, supermarkets, hospitals, construction clients, exporters, and corporate buyers require proof of cover before doing business.
Who Needs Product Liability Insurance in Kenya?
Any business that places products into the Kenyan market should seriously consider this cover. High-priority sectors include:
- Food and beverage manufacturers and processors
- Cosmetics and personal care producers
- Pharmaceuticals and medical devices
- Electronics and electrical appliances
- Furniture, building materials, and household goods
- Machinery and industrial equipment
- Importers, distributors, wholesalers, and retailers of consumer products
Examples of potential claims include contaminated food causing illness, a defective ladder leading to injury, inadequate chemical warnings resulting in harm, or an exploding appliance causing property damage.
What Does Product Liability Insurance Cover?
Typical coverage includes:
- Legal defence and litigation costs (with insurer consent)
- Compensation or settlements for bodily injury, illness, or death
- Property damage claims
- Medical expenses related to injuries caused by the product (in many policies)
- Costs recovered by claimants against the insured
Coverage is generally limited to products supplied in connection with the insured’s business and often restricted to judgments obtained in Kenyan courts (territorial limits commonly Kenya only, though extensions may be available).
Common Exclusions
Policies usually exclude:
- Fines and penalties
- Damage to the insured’s own products
- Product recall costs
- Efficacy risks (product failing to perform its intended purpose)
- Intentional or criminal acts
- Gradual pollution
- Injury or damage to the insured or employees arising from use of the product
- Contractual liabilities beyond common law obligations
- Claims arising from products still in the insured’s custody or control
Always review the specific policy wording, as exclusions and extensions vary between insurers.
How Much Does Product Liability Insurance Cost in Kenya?
Premiums depend on several factors:
- Type and risk profile of the products
- Annual turnover/revenue
- Distribution channels and geographic reach
- Claims history
- Chosen indemnity limits (any one accident and aggregate)
- Excess/deductible levels
For many SMEs, annual premiums often range from KES 25,000 to KES 300,000. Higher-risk products or larger operations attract higher premiums. Insurers such as GA Insurance, Cannon, First Assurance, Old Mutual, MUA, and others offer these policies. Working with a reputable broker can help secure competitive terms.
Benefits of Having Product Liability Insurance
- Protects business assets and cash flow from large claims
- Covers expensive legal defence even if claims are unfounded
- Builds credibility with buyers, retailers, and export partners who require proof of cover
- Supports compliance with modern consumer protection expectations
- Complements public liability insurance (which covers premises and operational risks rather than products after they leave your control)
How to Obtain Product Liability Insurance in Kenya
- Assess your product risks and supply chain exposure.
- Gather key information: product details, turnover, claims history, desired limits.
- Obtain quotations from licensed insurers or through an insurance broker/intermediary.
- Complete a proposal form and provide supporting documents (e.g., certificate of incorporation, KRA PIN).
- Review policy wording carefully, especially exclusions, territorial limits, and conditions.
- Arrange payment and receive the policy document.
Maintain strong quality control, proper labelling, batch records, and recall procedures — these reduce risk and support claims handling.
Frequently Asked Questions
Is product liability insurance compulsory in Kenya?
No, but it is often a commercial requirement imposed by major clients and partners.
Does it cover product recalls?
Generally no. Separate product recall or contingency covers may be needed.
Can retailers and importers get cover?
Yes. Coverage is available to manufacturers, sellers, vendors, distributors, and others in the supply chain.
What is the difference between public liability and product liability?
Public liability covers injury or property damage arising from business premises or activities. Product liability specifically addresses harm caused by products after they leave the insured’s control.
Conclusion
Product liability insurance in Kenya is a practical risk-management tool for any business involved in bringing products to market. With stronger consumer protection laws and increasing awareness of product safety, the financial and reputational consequences of a claim can be severe.
By understanding coverage, exclusions, and costs, and by securing an appropriate policy from a licensed insurer, businesses can operate with greater confidence. Consult a qualified insurance advisor or broker to tailor cover to your specific products and operations.
Protecting your business today helps safeguard its future.
By Raymond Momanyi - Founder & CEO Imana Insurance Agency Kenya Ltd