- Author: Raymond
- Category: Affordable Health Insurance
Medical Insurance Cost in Kenya: MyKava Plans from KSh 4,810
What does medical insurance cost in Kenya? See MyKava Medical prices by age and plan, from KSh 4,810 a year, plus what's covered and how to buy online.
How Much Does Medical Insurance Cost in Kenya? MyKava Medical Plans Explained
medical insurance cost in Kenya, affordable medical cover Kenya, family medical insurance Kenya, inpatient cover price, outpatient cover Kenya.
How much does medical insurance cost in Kenya?
"How much will it cost me?" is the first thing most people ask about medical insurance, and it's a fair question. Many Kenyans assume private medical cover is only for people with big salaries or employer schemes. That isn't always true.
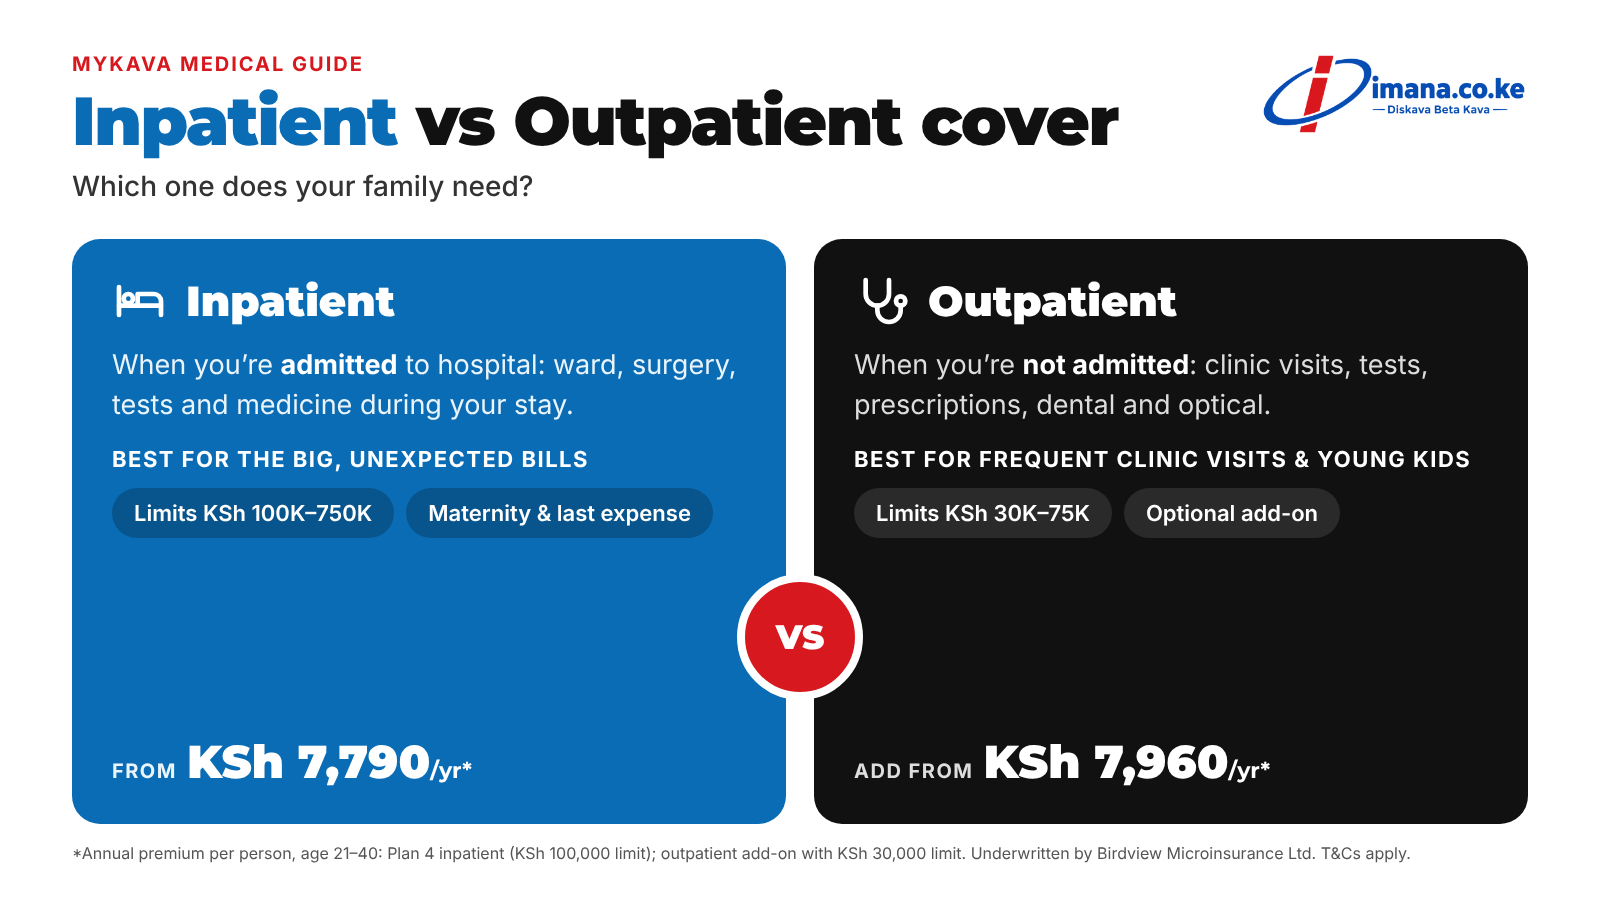
With MyKava Medical Insurance, from Imana Insurance Agency in partnership with Birdview Microinsurance Limited, inpatient cover starts from KSh 4,810 a year for children and young people up to 20, and from KSh 7,790 a year for adults aged 21–40. Your exact premium depends on two things: your age band and the cover limit you choose.
Below are the full annual premiums, so you can see what you'd pay before you even talk to us.
Inpatient cover: annual premiums per person
Inpatient cover pays for hospital admission: ward stay, doctors, tests, surgery and medicine while you're admitted. There are four plans. Find your age band, then pick the limit that fits your budget.
The four inpatient limits are Plan 1 (KSh 750,000), Plan 2 (KSh 500,000), Plan 3 (KSh 300,000) and Plan 4 (KSh 100,000). Here's what each costs per person, per year, by age:
- 1 month to 20 years: Plan 1 KSh 6,620 · Plan 2 KSh 5,890 · Plan 3 KSh 5,350 · Plan 4 KSh 4,810
- 21 to 40 years: Plan 1 KSh 11,800 · Plan 2 KSh 10,190 · Plan 3 KSh 9,260 · Plan 4 KSh 7,790
- 41 to 54 years: Plan 1 KSh 17,310 · Plan 2 KSh 14,910 · Plan 3 KSh 13,200 · Plan 4 KSh 9,730
- 55 to 65 years: Plan 1 KSh 23,450 · Plan 2 KSh 20,180 · Plan 3 KSh 17,610 · Plan 4 KSh 14,480
- 66 to 75 years: Plan 1 KSh 33,350 · Plan 2 KSh 26,680 · Plan 3 KSh 22,680 · Plan 4 KSh 17,400
That works out to about KSh 650 a month for an adult aged 21–40 on Plan 4. All prices are annual premiums.
Outpatient add-on: annual premiums per person
Outpatient cover is optional and is added to an inpatient plan. It pays for clinic visits, consultations, lab tests and prescriptions when you aren't admitted. Dental and optical benefits sit inside your outpatient limit.
You can choose an outpatient limit of KSh 30,000, 40,000, 50,000 or 75,000. Annual premiums per person:
- 1 month to 20 years: KSh 30,000 limit costs KSh 5,860 · KSh 40,000 costs KSh 7,880 · KSh 50,000 costs KSh 9,710 · KSh 75,000 costs KSh 12,210
- 21 to 40 years: KSh 30,000 limit costs KSh 7,960 · KSh 40,000 costs KSh 9,700 · KSh 50,000 costs KSh 11,290 · KSh 75,000 costs KSh 14,440
- 41 to 54 years: KSh 30,000 limit costs KSh 10,080 · KSh 40,000 costs KSh 11,770 · KSh 50,000 costs KSh 14,260 · KSh 75,000 costs KSh 16,670
- 55 to 75 years: KSh 30,000 limit costs KSh 12,910 · KSh 40,000 costs KSh 15,590 · KSh 50,000 costs KSh 18,160 · KSh 75,000 costs KSh 20,390
What every MyKava Medical plan includes
Whichever limit you choose, all four plans come with:
- Cover across East Africa, including when you're travelling
- General ward accommodation and road ambulance
- Maternity cover, after the waiting period
- Last expense benefit
- Psychiatric hospitalisation
- Pre-existing, chronic and congenital conditions, and HIV/AIDS-related conditions, within plan sub-limits and after the waiting period
- No medical exams to join
Who can join:
- Adults can join from 18 to 75 years and renew up to 100 years
- Children can be covered from birth
- Dependants are covered up to 25 years with proof of schooling
- Individuals, families and groups (staff, chamas, saccos) can all buy
If you add outpatient, dental and optical are included within that limit: KSh 10,000 on Plan 1, KSh 7,500 on Plan 2, and KSh 5,000 on Plans 3 and 4.
How to choose: three examples
Start with the inpatient limit you can comfortably afford, since hospital admission is the biggest financial risk. Then add outpatient if you visit clinics often or have young children. These examples use the published per-person rates; your final quote will be confirmed by our team.
Brian, 28, single and self-employed. Brian wants a safety net he can afford, plus help with clinic visits. He picks Plan 4 inpatient (KSh 7,790) and the KSh 30,000 outpatient option (KSh 7,960), for a total of KSh 15,750 a year.
The Wanjikus, a young family. The parents are 35 and 32, and the children are 6 and 3. They put all four on Plan 3, with a KSh 300,000 inpatient limit each. That's two adults at KSh 9,260 and two children at KSh 5,350, for a total of KSh 29,220 a year.
Grace, 50, a business owner. Grace wants a higher limit for peace of mind, so she picks Plan 2 inpatient (KSh 500,000) for KSh 14,910 a year.
Names are illustrative.
A few quick rules of thumb:
- Young and healthy on a tight budget? Plan 4 gives you a safety net for under KSh 650 a month.
- Young family? Cover the children too. Their premiums are the lowest in the table, and outpatient helps with frequent clinic visits.
- Over 40, or managing a chronic condition? Consider a higher inpatient limit (Plan 1 or 2), so a longer hospital stay is less likely to go over your limit.
Waiting periods and exclusions: read before you buy
We'd rather you know this upfront. Cover starts once your premium is paid in full and confirmed in writing, and some benefits have a waiting period:
- Accidents: covered from day one, with no waiting period
- General illness: 30 days
- Maternity and pregnancy complications: 10 months
- Chronic and pre-existing conditions: 10 months
These waiting periods apply to individual policies and to group policies with an annual premium below KSh 250,000. MRI, CT and PET scans need pre-authorisation.
The main things not covered include:
- Cosmetic or plastic surgery (unless needed after an insured accident)
- Herbal, acupuncture and chiropractic treatment
- Beauty treatments, massage, and old age home stays
- Genetic disorders and genetic testing
- Vitamins, supplements and nutritional products
- Alcohol or drug addiction treatment, and weight-loss services
- Epidemics, pandemics and unknown diseases
- War, riots, strikes and terrorism
- Costs recoverable under SHA, WIBA or personal accident insurance
This isn't the full list, so please read the policy document before you buy. We're happy to walk you through it.
How to get MyKava Medical cover
Getting covered takes five steps:
- Choose your inpatient limit (Plan 1 to 4)
- Add outpatient cover if you need it
- Confirm your age band and the dependants you want covered
- Review the waiting periods and exclusions
- Pay your premium and receive written confirmation of cover
Ready to see your exact price? Get a quote online at imana.co.ke/mykava-product-quote, or WhatsApp us on +254 745 218 460. You can also email insurance@imana.co.ke or visit us on the 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi.
Follow Imana Insurance on Facebook, Instagram, LinkedIn and X for more tips on protecting your family and your money.
MyKava Medical Insurance is distributed by Imana Insurance Agency Kenya Ltd and underwritten by Birdview Microinsurance Limited. Premiums shown are annual, per person, and correct as of November 2026; they vary by age band and the limits selected. Benefits are subject to policy terms, sub-limits, waiting periods and exclusions. T&Cs apply.