- Author: Raymond
- Category: Insurance in Kenya
Insurance Agency in Westlands Nairobi | Imana Guide
Find and compare motor, medical, WIBA, travel, life, home and business insurance through Imana in Westlands, Nairobi. Get expert guidance.
Looking for insurance in Westlands, Nairobi, elsewhere in Kenya or across borders? This complete guide explains how Imana Insurance Agency Kenya Ltd helps individuals, families, motorists, employers and businesses compare suitable cover, understand policy terms and receive support from quotation to claim.
By Raymond Momanyi, Founder & CEO, Imana Insurance Agency Kenya Ltd
Insurance should not begin with a sales pitch. It should begin with one honest question: what could go wrong, and what protection would actually help when it does?
That question matters whether you are insuring a private car in Westlands, arranging medical cover for a family in Nairobi, protecting employees anywhere in Kenya, moving goods across East Africa, applying for a visa, managing rental property, running a growing company or seeking Kenyan insurance support while living abroad.
Imana Insurance Agency Kenya Ltd is a digital-first insurance intermediary based at 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya. We help individuals, families, professionals, employers, SMEs and larger organisations understand insurance, compare quotations from trusted insurers and choose cover based on benefits, exclusions, limits, service and price.
For a quotation comparison, visit ImanaInsurance.com. For travel and selected medical solutions, visit MyKava Travel & Insurance. You may also contact the Imana team or Call/WhatsApp +254 796 209 402.
Why choosing the right insurance intermediary matters
Insurance is not simply a certificate, a policy schedule or the lowest premium on a quotation. It is a contract. The real test comes after a collision, hospital admission, workplace injury, burglary, fire, professional allegation, cargo loss or disrupted journey.
A good insurance intermediary should help you:
- identify the risks that genuinely matter;
- compare more than price;
- understand excesses, waiting periods, exclusions, sublimits and conditions;
- disclose all material information correctly;
- select an appropriate insurer and policy;
- complete documentation accurately;
- receive the policy and certificate promptly; and
- navigate notification and documentation when a claim occurs.
Imana is an insurance intermediary, not the underwriting insurer. The chosen insurer issues the policy, carries the insured risk and determines claims in accordance with the policy terms. Imana's role is to make the journey clearer—from risk review and quotation comparison to placement, renewal and claims support.
Kenya's insurance sector is regulated by the Insurance Regulatory Authority. Buyers should always confirm the insurer, intermediary, scope of cover, premium, policy wording and official payment instructions before committing funds.
Insurance near Westlands, Sarit Centre, Westgate and Nairobi
Searching for an insurance agency near me, an insurance broker in Westlands, or help with motor, medical or corporate insurance near Sarit Centre or Westgate often means the same thing: you want professional assistance that is accessible, fast and accountable.
Imana combines a physical office in Westlands with online service across Kenya. Clients do not have to cross Nairobi traffic merely to request a quotation. Information and documents can be shared digitally, comparisons can be discussed by phone or WhatsApp, and eligible certificates and policy documents can be delivered electronically.
The office remains available for clients who prefer face-to-face guidance, especially where the risk is complex, several covers must be coordinated or policy terms need a deeper explanation.
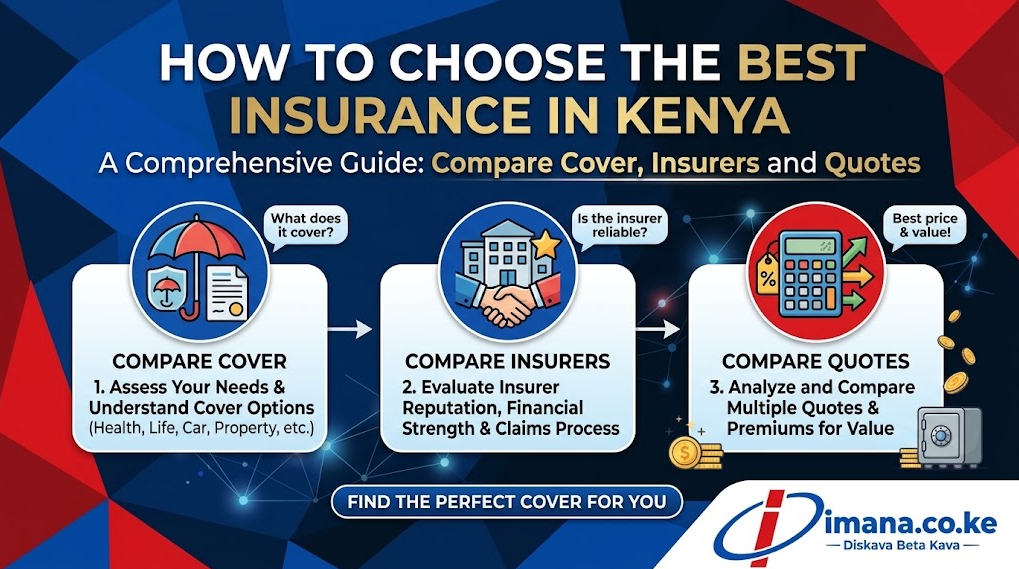
Compare insurance quotations before you buy
Two policies with similar names can behave very differently. A cheaper quotation may carry a higher excess, narrower territorial limits, restrictive theft conditions, a smaller hospital network or missing extensions. A higher premium is not automatically better either.
When comparing insurance quotations in Kenya, examine:
- who the underwriting insurer is;
- exactly what is insured;
- the sum insured or benefit limit;
- excesses and deductibles;
- exclusions and special conditions;
- waiting periods and co-payments;
- territorial scope;
- optional extensions;
- claims-reporting requirements;
- premium payment terms; and
- the service available after purchase.
Use ImanaInsurance.com as the quotation-comparison pathway, or select the relevant product below.
Motor insurance in Kenya
Motor insurance is needed for many different vehicle uses, and the correct classification matters. A private vehicle, commercial pickup, taxi, matatu, school bus, tour van, motorcycle and tuk-tuk do not present the same risk.
Start with the motor insurance authority page or explore car insurance in Kenya. Available solutions may include Third Party Only, Third Party Fire and Theft, and Comprehensive insurance, subject to the vehicle type, use, value, age, underwriting requirements and insurer terms.
Imana can also assist with:
- PSV insurance for taxis, ride-hailing vehicles, matatus, buses, school transport and tour vehicles;
- motorcycle insurance for private, boda boda, delivery and commercial use;
- tuk-tuk insurance;
- commercial and fleet motor insurance; and
- add-ons such as excess protector, political violence and terrorism, road rescue, passenger liability, windscreen, entertainment equipment and other extensions where offered.
For vehicles crossing participating regional borders, review COMESA Yellow Card insurance. The COMESA Yellow Card is a regional third-party motor insurance system intended to support cross-border movement and claims involving visiting motorists; territorial recognition and policy requirements should be confirmed for the intended route before travel.
Ready to compare? Use the motor insurance quotation form.
Medical and health insurance for individuals and families
Medical cover should match more than a budget. It should reflect age, family composition, medical history, preferred hospitals, geographic needs and the benefits that are most likely to be used.
Begin with the health insurance guide and product page. Clients looking for an arranged individual or family solution can also review Imana Health.
Depending on the selected plan, medical insurance may include inpatient treatment, outpatient care, maternity, dental, optical, last expense and emergency benefits, subject to policy limits, waiting periods, exclusions, co-payments and provider networks.
Imana also supports:
- individual medical insurance;
- family medical cover;
- child-only options where available;
- medical insurance for parents and senior citizens, subject to entry-age rules;
- group medical insurance for employers;
- regional or international medical options where available; and
- maternity insurance, including plans where maternity is an included or optional benefit.
Request a comparison through the health insurance quotation form. For selected simplified health options, use the micro-health quotation pathway or medical registration page.
Life, personal accident and last expense insurance
Life and personal protection covers help families and organisations manage the financial shock of death, accidental injury, disability or funeral costs.
Explore life insurance and individual life solutions for longer-term personal and family protection. The right structure may depend on income, dependants, debts, education goals, business obligations and the amount of protection required.
Personal accident insurance can provide defined benefits following accidental bodily injury, disability or death, subject to the policy. Review further personal accident details when assessing the scope.
Last expense insurance is designed to provide a stated funeral benefit after an insured death, subject to eligibility, waiting periods and policy terms. Individuals, families, welfare groups, churches, associations and employers can use the last expense quotation form.
For a tailored life quotation, use the life insurance quote pathway.
Home, landlord, tenant and property insurance
A home is more than walls. It may contain furniture, electronics, appliances, personal possessions and years of accumulated value. Owners may also face liability to third parties or loss of rental income, while tenants may need to insure contents even when they do not own the building.
Home insurance, often arranged as a domestic package, may combine several sections such as buildings, contents, burglary, domestic workers' liability, owners' or occupiers' liability and portable items. Cover varies by insurer and must be matched to the property and occupancy.
Imana can guide:
- homeowners insuring buildings and contents;
- landlords protecting buildings and rental exposures;
- tenants insuring household contents;
- Airbnb and short-stay hosts seeking suitable property and liability protection;
- families insuring electronics and mobile equipment; and
- property owners reviewing fire, flood, burglary and liability risks.
Portable devices or valuable items may require declaration, valuation, serial numbers or an all-risks extension. Do not assume every phone, laptop or item outside the home is automatically insured.
WIBA and employee insurance
Employers need to protect both their people and the organisation. WIBA insurance responds to work-related injury, occupational disease or death in accordance with the policy and Kenya's applicable work-injury framework.
Premium assessment commonly considers payroll, occupations, employee numbers and the nature of the work. Office employees, retail workers, drivers, factory staff and construction workers do not carry identical exposure.
WIBA should not be confused with Group Personal Accident. WIBA focuses on work-related events, while GPA can be structured more broadly, including 24-hour accidental injury benefits where selected. Employers may combine WIBA, GPA, Group Life and Group Medical as part of a coordinated employee-benefits programme.
The Ministry of Labour's occupational safety resources explain the reporting process and prescribed documentation for workplace injuries. Employers should notify workplace accidents promptly and follow the required DOSH process; the applicable deadlines and forms should be checked at the time of an incident.
Business, SME and corporate insurance
A business can survive a slow month. It may not survive an uninsured fire, major liability claim, cyber incident, machinery failure or prolonged interruption.
The business insurance page introduces covers that may be combined for shops, offices, professional firms, contractors, schools, hospitality businesses, property owners, logistics companies, manufacturers and other enterprises.
For wider organisational needs, explore corporate insurance. A well-designed corporate programme may include:
- fire and special perils;
- burglary;
- business interruption or consequential loss;
- money insurance;
- goods in transit;
- machinery breakdown;
- electronic equipment;
- fidelity guarantee;
- public and products liability;
- employers' liability;
- WIBA and Group Personal Accident;
- Group Medical and Group Life;
- cyber insurance;
- contractors' all risks and erection all risks;
- directors' and officers' liability;
- professional indemnity;
- motor fleet; and
- marine cargo or hull insurance.
No two businesses should be insured by blindly copying the same package. A clinic, law firm, restaurant, warehouse, technology company and construction contractor each require a different risk conversation.
Request a review through the corporate insurance quotation form.
Professional indemnity and liability insurance
Professionals may face allegations that an error, omission, negligent act or inadequate advice caused a client financial loss. Professional indemnity insurance is relevant to many consultants, lawyers, accountants, engineers, architects, medical practitioners, technology providers and other professionals, subject to the insurer's occupation appetite and wording.
Businesses should also consider public liability, products liability, employers' liability, directors' and officers' liability or cyber liability where those exposures exist. These covers are not interchangeable. The trigger, claimant, limit, excess, territorial scope and exclusions must be reviewed carefully.
Marine cargo, transit and logistics insurance
Importers, exporters, manufacturers, distributors, clearing agents and logistics businesses can face loss or damage while goods are moving or temporarily stored during an insured transit.
Marine insurance may include marine cargo, marine hull and related transit risks. Cover can be arranged for individual shipments or, where suitable, on an open-cover basis for repeated movements.
The correct solution depends on the goods, packing, voyage, conveyance, origin, destination, value, Incoterms, claims history and required clauses. “Warehouse to warehouse” does not mean every delay, loss or event is automatically covered; the wording and exclusions still govern.
Travel insurance from Kenya to the world
Travel insurance is relevant to holidaymakers, business travellers, students, families, groups and visitors requiring evidence of cover for a visa application.
Review travel insurance and the additional travel insurance details. For travel planning and selected insurance services, visit MyKava Travel & Insurance.
A travel policy may cover eligible emergency medical expenses, evacuation, repatriation, baggage loss, travel delay, cancellation or personal liability, depending on the plan. Always confirm destination, trip dates, age limits, pre-existing-condition rules, activity exclusions and visa requirements before purchase.
Travel insurance connects Imana's Westlands office to the world: a client may buy in Nairobi, travel across East Africa, study abroad, visit Europe, do business in Asia or arrange cover from the diaspora for a journey beginning in Kenya. What matters is that the selected policy fits the traveller, destination and journey.
Expatriate and internationally connected insurance needs
Kenya attracts expatriates, investors, development organisations, diplomatic communities, regional businesses and returning diaspora families. These clients may require local medical insurance, international health options, motor cover, home insurance, travel insurance, professional protection or coordinated corporate programmes.
Explore expatriate insurance and speak with Imana about the countries involved, desired territorial scope and where the insured risk is physically located.
Imana's international reach should be understood correctly: the agency is based in Kenya and can support overseas clients and travellers where a suitable policy can lawfully be arranged through its insurer partners. Availability depends on residency, destination, risk location, insurer appetite and policy jurisdiction.
Specialist risks, bonds and covers not listed above
Insurance needs do not always fit neatly into a menu. Imana can assist clients in exploring specialist covers such as cyber, aviation, contractors' all risks, plant and machinery, bonds, political violence and terrorism, directors' and officers' liability, event-related risks and other tailored solutions, subject to availability and underwriting.
If the required product does not have a dedicated page, use the other insurance quotation form or the MyKava product quotation form. Describe the activity, asset, contract or risk clearly so the team can identify an appropriate route.
Claims support: the moment insurance becomes real
Claims are not won by panic. They are protected by prompt reporting, accurate information, reasonable loss mitigation and complete documentation.
After an incident:
- Protect life and seek emergency help first.
- Take reasonable steps to prevent further loss without putting anyone at risk.
- Notify the insurer or Imana promptly.
- Report to the police, DOSH or another relevant authority where required.
- Preserve evidence, photographs, receipts and damaged property.
- Do not admit liability, negotiate privately or repair/dispose of insured property without approval where the policy requires consent.
- Complete claim forms honestly and submit the requested documents.
Use the Imana claims request page to begin the support process. Claim admissibility and settlement remain subject to the insurer's assessment, policy wording, exclusions, excesses and supporting evidence.
How to get an insurance quotation from Imana
The process is designed to be clear:
- Identify the need. Select motor, medical, travel, life, property, WIBA, business or another class.
- Share accurate information. The required documents depend on the risk and may include identification, KRA PIN, logbook, valuation, employee schedule, payroll, asset values, travel dates, medical details or company registration documents.
- Compare quotations. Review benefits, limits, exclusions, excesses and insurer terms—not price alone.
- Choose the cover. Confirm the insurer, period of insurance, named insured, risk details and extensions.
- Pay through confirmed channels. Verify all payment instructions before sending funds.
- Receive and check the documents. Read the schedule, certificate and wording, then report any error immediately.
- Stay renewal-ready. Update material changes and begin renewal review before expiry.
Start at ImanaInsurance.com, choose a dedicated quotation form on Imana.co.ke, or Call/WhatsApp +254 796 209 402.
Why individuals and businesses choose Imana
The Imana approach rests on four ideas.
Comparison with context. A quotation becomes useful only when the buyer understands what sits behind the price.
Digital convenience with human guidance. Clients can transact remotely but still speak to a real team or visit the Westlands office.
One relationship across many risks. A family may need motor, medical, home, life and travel cover. A company may need WIBA, liability, property, cyber, marine and employee benefits. Coordinated advice reduces gaps and unnecessary duplication.
Support beyond the sale. Renewals, amendments, questions and claims guidance are part of the insurance relationship.
Frequently asked questions
Where is Imana Insurance Agency Kenya Ltd located?
Imana is located at 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya, near the wider Sarit Centre and Westgate area. Services are also available online to clients across Kenya.
Is Imana an insurance company?
No. Imana Insurance Agency Kenya Ltd is an insurance intermediary. It helps clients compare and arrange policies from insurers. The selected insurer underwrites the risk and determines claims under the policy terms.
Can I compare insurance quotations through Imana?
Yes. Imana helps clients compare suitable options based on price, benefits, limits, exclusions, excesses and underwriting terms. Begin at ImanaInsurance.com.
Which types of insurance does Imana arrange?
The portfolio includes motor, PSV, motorcycle, tuk-tuk, COMESA Yellow Card, medical, life, last expense, personal accident, home, WIBA, employee benefits, business, corporate, professional indemnity, marine, travel, expatriate and other specialist covers, subject to availability and underwriting.
Can I buy insurance online from outside Nairobi?
Yes. Many quotation, documentation and policy-delivery steps can be completed remotely. Availability and requirements depend on the product, insurer and location of the risk.
Does Imana serve East African and international clients?
Imana can assist with relevant regional and international needs such as COMESA Yellow Card, East Africa medical options, travel insurance, expatriate solutions and cover for overseas clients with insurable interests connected to Kenya. Every case remains subject to territory, residency, regulation and insurer acceptance.
What documents are needed for a quotation?
Requirements vary. Motor quotations may need vehicle and usage details; medical quotations need ages and benefit preferences; WIBA requires workforce and payroll information; travel cover needs dates and destinations; property and business covers require values and risk details.
How quickly can insurance be issued?
Simple covers can often be processed digitally once complete information, acceptable documents, underwriting approval and cleared premium are received. Complex corporate or specialist risks require more review. No certificate or cover should be assumed until formally confirmed.
Does Imana help with insurance claims?
Yes. Imana can guide notification and documentation through the claims request page. The insurer remains responsible for assessing and deciding the claim under the policy.
How do I contact Imana?
Visit the contact page, Call/WhatsApp +254 796 209 402, visit Imana.co.ke, compare quotations at ImanaInsurance.com, or explore travel and selected insurance solutions through MyKava.co.ke.
One agency. Many risks. One clearer path.
Insurance does not stop bad days from arriving. It can stop one bad day from becoming a permanent financial wound.
If you are looking for an insurance agency in Westlands, comparing insurance in Nairobi, arranging protection anywhere in Kenya, travelling or trading across East Africa, or seeking cover connected to Kenya from elsewhere in the world, Imana Insurance Agency Kenya Ltd offers a practical starting point.
Compare carefully. Understand the cover. Protect what matters.
- Compare insurance quotations
- Explore Imana Insurance products
- Explore MyKava travel and insurance solutions
- Request support
- Call/WhatsApp: +254 796 209 402
Author
Raymond Momanyi is the Founder & CEO of Imana Insurance Agency Kenya Ltd, a digital-first insurance intermediary based in Westlands, Nairobi. His work focuses on insurance comparison, risk advisory, motor and medical insurance, WIBA, PSV insurance, business protection, digital distribution and claims support for individuals and organisations in Kenya and East Africa.
Editorial and insurance disclaimer
This article provides general information and does not replace a policy schedule, policy wording, professional risk assessment or insurer underwriting decision. Insurance availability, premiums, benefits, limits, exclusions, excesses, waiting periods, territorial scope and acceptance may change and differ by insurer. Read the policy documents and confirm current terms before purchase. Claims are assessed by the underwriting insurer in accordance with the issued policy and supporting evidence.