- Author: Raymond
- Category: Compare Insurance Quotations In Kenya
Best Insurance in Kenya | Compare Covers and Quotes
Learn how to choose insurance in Kenya by comparing insurers, benefits, exclusions, claims service and premiums for motor, medical and business cover.
The best insurance in Kenya is not automatically the cheapest or most advertised policy. Learn how to compare insurers, benefits, exclusions, claims service and premiums before choosing motor, medical, WIBA, travel, home, life or business insurance.
How to Choose the Best Insurance in Kenya: Compare Cover, Insurers and Quotes
By Raymond Momanyi, Founder & CEO, Imana Insurance Agency Kenya Ltd
What is the best insurance in Kenya?
The honest answer is simple: the best insurance is the policy that matches your risk, provides adequate benefits, comes from a suitable licensed insurer and responds as expected when a valid claim occurs. It is not necessarily the cheapest quotation, the most famous insurance company or the policy with the longest list of benefits.
For a motorist, the right cover may be comprehensive insurance with excess protector and political violence and terrorism extensions. For a young family, it may be medical insurance with a suitable hospital network and manageable co-payments. For an employer, it may be a combination of WIBA, Group Personal Accident, Group Medical and Group Life. For a business, it could involve property, liability, cyber, marine and business interruption insurance working together.
This guide explains how individuals, families, motorists, professionals and businesses can compare insurance in Kenya intelligently—without choosing blindly or buying on price alone.
To request and compare personalised quotations, visit ImanaInsurance.com. To explore insurance information and product pages, visit Imana Insurance Agency Kenya Ltd. For travel and selected medical solutions, visit MyKava Travel & Insurance.
What “best insurance” really means
There is no single insurance company or policy that is automatically best for every person and every risk.
Insurers have different underwriting appetites. One may be competitive for private motor vehicles while another may be more suitable for PSV, medical, marine cargo, professional indemnity or corporate property. Hospital networks, claims procedures, excesses, exclusions, territorial limits and optional extensions also differ.
The best choice should therefore be evaluated using several questions:
- Does the policy cover the risk you are genuinely exposed to?
- Is the insurer licensed and suitable for that class of insurance?
- Are the benefit limits adequate?
- Which exclusions, excesses, waiting periods and conditions apply?
- Is the premium affordable throughout the policy period?
- Does the insurer have appropriate service providers, such as hospitals or repair garages?
- What documents and timelines apply when making a claim?
- Can you obtain guidance before purchase and support after an incident?
The word best should describe suitability—not hype.
Start by identifying what you need to protect
Insurance comparison works only when the information supplied is accurate. Before asking for quotations, identify the asset, person, responsibility or income stream that needs protection.
You may need to protect:
- a private car, commercial vehicle, motorcycle, taxi, matatu or bus;
- personal or family healthcare costs;
- employees exposed to workplace injury;
- a home, rental property or household contents;
- family income after death or disability;
- an international journey;
- imported or exported goods;
- professional advice or services;
- company buildings, stock, machinery and revenue;
- customer, employee or digital data; or
- contractual obligations requiring a bond.
Once the risk is clear, quotations can be compared on a like-for-like basis.
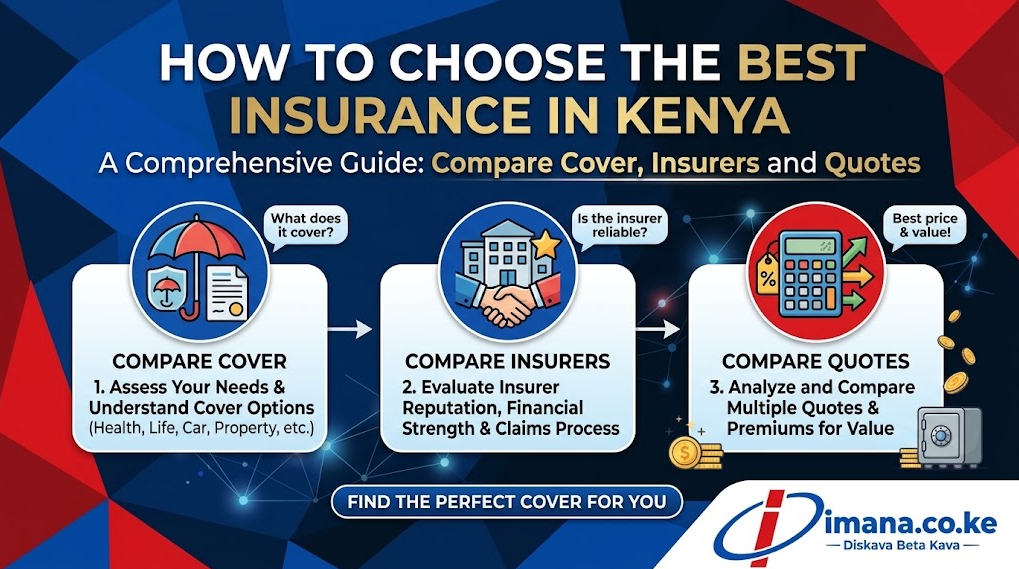
How to compare insurance quotations in Kenya
A low premium can look attractive until you discover that an important extension is missing, the excess is high or the benefit limit is too small. Conversely, an expensive quotation is not automatically superior.
Compare the following before making a decision.
1. Confirm the underwriting insurer
Know which insurance company will issue the policy and carry the risk. An insurance intermediary helps arrange and service the policy, but the insurer underwrites it and assesses claims according to the contract.
Kenya's insurance industry is supervised by the Insurance Regulatory Authority. Buyers should confirm that the insurer and intermediary are appropriately authorised and should verify payment instructions before sending money.
2. Compare the same scope of cover
Do not compare a comprehensive motor quotation with Third Party Only, or an inpatient-only medical plan with a plan containing inpatient, outpatient, dental, optical and maternity benefits. The policies solve different problems.
Ask for a clear breakdown of the principal cover and optional extensions.
3. Examine the benefit or sum insured
The sum insured is the value or maximum limit applied to the insured item or benefit, subject to the policy wording. An inadequate limit may leave you financing a large part of the loss yourself.
Property and motor values should be reasonably accurate. Medical, life, liability and employee-benefit limits should reflect the exposure and financial consequences of a serious event.
4. Read the exclusions
An exclusion describes an event, circumstance or loss that the policy does not cover. Common examples may involve undeclared vehicle use, wear and tear, pre-existing medical conditions, unattended property, fraud, contractual liability, unapproved repairs or travel undertaken against medical advice.
Never rely on a headline alone. Read the schedule, wording, endorsements and exclusions together.
5. Understand excesses and deductibles
An excess is the portion of an admissible claim that the insured must bear. Different excesses may apply to theft, young drivers, inexperienced drivers, windscreen damage, property claims or other circumstances.
A motor policy may offer an excess protector extension, but it does not erase every excess in every situation. Its own conditions and exclusions still apply.
6. Check waiting periods, co-payments and sublimits
These are especially important in medical, life and last expense insurance.
A waiting period delays access to certain benefits. A co-payment requires the member to contribute a stated amount or percentage. A sublimit restricts the amount available for a specific treatment or service even where the overall benefit is higher.
7. Review territorial limits
A Kenyan motor policy may not automatically provide the protection required when driving across regional borders. A medical policy may cover Kenya, East Africa or wider territories depending on the plan. Travel policies are issued for stated destinations and dates.
Confirm the actual territory before travelling, relocating or moving goods.
8. Study the claims process
Ask what must happen after an accident, illness, injury, theft, fire or professional allegation. Understand notification deadlines, required reports, assessment procedures, approved service providers and documents.
Claims service should be part of the buying decision—not an afterthought.
Best motor insurance in Kenya: what should you compare?
The correct motor policy depends on vehicle type, use, age, value, claims history and required extensions.
Motor insurance generally falls into three broad levels:
Third Party Only primarily covers legal liability for third-party bodily injury and property damage within the policy and applicable legal limits. It does not generally repair or replace the insured vehicle after an accident, theft or fire.
Third Party, Fire and Theft adds specified fire and theft protection for the insured vehicle to third-party cover, subject to the wording.
Comprehensive insurance usually combines accidental damage to the insured vehicle with third-party liability and other insured events. It is broader, but it does not cover everything.
When comparing comprehensive motor insurance, review:
- the insured value;
- basic premium rate and minimum premium;
- excesses;
- excess protector;
- political violence and terrorism cover;
- windscreen and entertainment-system limits;
- road rescue;
- courtesy car or loss-of-use benefits;
- authorised repair arrangements;
- theft requirements;
- geographical limits; and
- instalment conditions, where available.
Different vehicle classes require different policies. Explore private car insurance, PSV insurance, motorcycle insurance and tuk-tuk insurance.
For cross-border driving, consider COMESA Yellow Card insurance. It is a regional third-party motor insurance system; it should not be mistaken for comprehensive cover on the insured vehicle.
Request a personalised comparison using the motor insurance quotation form.
Best medical insurance in Kenya: what matters most?
The best medical insurance is not necessarily the plan with the largest headline inpatient limit. It must work for the people being covered, the hospitals they are likely to use and the treatments that matter to them.
When comparing medical insurance in Kenya, examine:
- inpatient and outpatient limits;
- hospital network;
- maternity benefits and waiting periods;
- dental and optical benefits;
- chronic and pre-existing-condition provisions;
- congenital-condition provisions;
- psychiatric and counselling benefits;
- co-payments;
- overseas or East Africa cover;
- emergency evacuation;
- age limits at entry and renewal; and
- exclusions and preauthorisation requirements.
Individuals and families can also explore Imana Health. Clients seeking maternity benefits should review maternity insurance options, while eligible customers looking for simplified plans can use the micro-health quotation pathway.
Do not hide medical information on an application. Non-disclosure can create serious problems when a claim is assessed.
Request a tailored comparison using the health insurance quotation form.
Best WIBA and employee insurance for Kenyan employers
WIBA insurance is designed to address an employer's obligations arising from work-related injury, occupational disease or death, subject to the applicable law and policy.
The premium commonly depends on employee numbers, annual earnings, occupations and the level of workplace risk. An office-based team and a construction workforce should not be rated or described as though their exposures were identical.
Employers should also understand the difference between WIBA and Group Personal Accident. WIBA focuses on work-related events. GPA may be arranged with broader accidental injury protection, including 24-hour cover where selected. Group Medical and Group Life can then provide additional employee protection.
The best programme may therefore be a coordinated combination of:
- WIBA or WIBA Plus;
- Group Personal Accident;
- Group Medical;
- Group Life; and
- appropriate liability and property insurance for the employer.
Accidents must be reported promptly through the applicable occupational-safety process. Use Imana's corporate quotation form to request an employee-benefits comparison.
Best home insurance for homeowners, landlords and tenants
Home insurance may protect buildings, contents and specified liabilities under a domestic package. The appropriate sections depend on whether you own the building, rent the property, let it to tenants or operate short-stay accommodation.
Homeowners should consider rebuilding value rather than the property's sale price. Tenants may not need to insure the landlord's building, but they still need to consider furniture, electronics, clothing and other contents. Landlords may require building insurance, owners' liability, loss-of-rent protection and suitable terms for the property's occupancy.
Portable electronics, jewellery, phones and laptops may need to be declared and insured under an all-risks section. Theft conditions, proof of ownership and security requirements should be understood before purchase.
Read the broader Domestic Package Insurance guide before selecting a policy.
Best travel insurance from Kenya
The right travel insurance depends on destination, trip duration, traveller age, planned activities and visa requirements.
A policy may include eligible emergency medical expenses, evacuation, repatriation, baggage loss, travel delay, cancellation, curtailment, passport loss and personal liability. Benefits differ considerably.
Before buying travel insurance, confirm:
- all destination countries;
- departure and return dates;
- age limits;
- medical limits;
- treatment of pre-existing conditions;
- sports and activity exclusions;
- cancellation conditions;
- baggage sublimits; and
- whether the policy satisfies the relevant embassy or visa requirement.
For travel planning and selected insurance solutions, visit MyKava Travel & Insurance or review the additional travel insurance details.
Best life, personal accident and last expense insurance
These covers address different financial needs.
Life insurance can provide longer-term financial protection for dependants, debts, education goals or business obligations. The appropriate benefit should reflect income, responsibilities and the financial gap that death would create.
Personal accident insurance provides defined benefits following insured accidental injury, disability or death, subject to the schedule and wording. It is not a substitute for comprehensive medical or life insurance.
Last expense insurance is intended to provide a stated funeral benefit after an insured death. Compare entry ages, family definitions, waiting periods, benefit limits and exclusions.
Use the life quotation form or last expense quotation form to obtain suitable options.
Best business and corporate insurance in Kenya
The right business insurance programme begins with a risk assessment—not a pre-packed list of covers.
A retailer, school, restaurant, law firm, medical facility, contractor, logistics operator and manufacturer face very different exposures. Begin with the business insurance page or corporate insurance page.
A tailored programme may include:
- fire and special perils;
- burglary;
- business interruption;
- money insurance;
- fidelity guarantee;
- goods in transit;
- machinery breakdown;
- electronic equipment;
- public and products liability;
- employers' liability;
- professional indemnity;
- directors' and officers' liability;
- cyber insurance;
- contractors' all risks;
- marine insurance;
- motor fleet;
- WIBA and GPA; and
- Group Medical and Group Life.
Professional indemnity insurance is particularly important for professionals and businesses whose advice, designs or services could allegedly cause a client financial loss.
Marine insurance may protect imports, exports, cargo and related transit exposures. The goods, packing, voyage, value, Incoterms and required clauses must be disclosed correctly.
Request a tailored review through the corporate insurance quotation form. If the required specialist cover is not listed, use the other insurance quotation form.
Should you choose the cheapest insurance quotation?
Not automatically.
Price matters because an unaffordable policy may lapse or become difficult to maintain. But the cheapest quotation can become expensive if it leaves out the very event that causes your loss.
A meaningful price comparison must use equivalent:
- sums insured;
- benefit limits;
- excesses;
- policy periods;
- extensions;
- territories;
- insured persons or assets; and
- payment terms.
If one quotation is dramatically cheaper, ask why. The difference may be legitimate, but it may also reflect missing benefits, different deductibles, restricted cover or inaccurate risk information.
Red flags when buying insurance
Pause before proceeding if:
- the seller will not identify the underwriting insurer;
- payment is requested through an unverified personal number or account;
- the premium is suspiciously lower than every comparable option;
- you are encouraged to provide false information;
- nobody explains exclusions, excesses or waiting periods;
- the policyholder, vehicle, property or employee details are incorrect;
- a certificate is promised before underwriting requirements are met;
- guaranteed claim payment is promised;
- you receive only a payment message but no policy documentation; or
- you are pressured to buy immediately without reviewing the quotation.
Check the schedule and certificate as soon as they are issued. Errors should be reported immediately.
Why claims are part of choosing the best cover
Insurance becomes real at the claim stage. A strong buying decision anticipates what must happen after a loss.
When an incident occurs:
- Protect life and seek emergency assistance.
- Take reasonable steps to prevent further loss.
- Notify the insurer or intermediary promptly.
- Report to the police, DOSH or another authority where required.
- Preserve photographs, reports, receipts and damaged property.
- Do not admit liability or arrange unauthorised repairs or disposal.
- Complete the claim form accurately.
- Submit all requested supporting documents.
Use the Insurance Claims Knowledge Centre to understand common processes. Relevant guides include:
- How to File a Motor Insurance Claim in Kenya
- WIBA Claims Process in Kenya
- Medical Insurance Claims and Preauthorisation
- How to Challenge a Rejected Insurance Claim
Clients can also begin a notification through the Imana claims request page. The insurer assesses and determines every claim according to the policy, evidence and applicable terms.
Why use an insurance intermediary?
Buying directly from one provider may show you only that provider's solution. An intermediary can help examine available options, explain differences and coordinate the documentation.
Imana Insurance Agency Kenya Ltd is a digital-first insurance intermediary based at 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi. Imana helps individuals, families, motorists, professionals, employers and businesses compare suitable policies from trusted insurers.
The process may include:
- understanding the risk;
- sourcing suitable quotations;
- explaining benefits and exclusions;
- arranging documentation and policy placement;
- checking issued documents;
- renewal reminders and policy amendments; and
- claims-notification and documentation support.
Imana is not the underwriting insurer and cannot guarantee claim approval. The selected insurer carries the risk and determines claims under the policy.
For a complete overview of Imana and its product range, read the Insurance in Westlands, Nairobi, Kenya and East Africa guide.
How to buy insurance online through Imana
The online process is straightforward:
- Choose the type of insurance required.
- Share accurate risk information and supporting documents.
- Receive and compare suitable quotations.
- Review the insurer, benefits, exclusions, limits and excesses.
- Select the preferred option.
- Confirm official payment instructions and pay the required premium.
- Receive and check the certificate, schedule and policy documents.
Start at ImanaInsurance.com, use the relevant quotation form on Imana.co.ke, or contact the Imana team.
Frequently asked questions about the best insurance in Kenya
Which is the best insurance company in Kenya?
No single insurance company is best for every customer or class of business. Compare insurers according to the required product, policy benefits, exclusions, financial limits, provider network, service, premium and claims process.
Which insurance is compulsory in Kenya?
Motor vehicles used on public roads require the applicable statutory third-party insurance. Employers must also understand their obligations for work-related injuries under Kenya's work-injury framework. The exact cover and legal requirements should be confirmed for the particular risk.
Is comprehensive motor insurance always better than Third Party Only?
Comprehensive insurance is broader because it can cover accidental loss or damage to the insured vehicle as well as third-party liability. However, suitability depends on vehicle value, use, budget, exclusions and excesses. Comprehensive does not mean every possible loss is insured.
How can I compare insurance prices in Kenya?
Provide the same accurate information to obtain like-for-like quotations, then compare the insurer, scope, limits, excesses, exclusions, extensions and payment terms. Use ImanaInsurance.com to request a personalised comparison.
Can I purchase insurance online in Kenya?
Yes. Many quotation, documentation, payment and policy-delivery steps can be completed digitally. Issuance remains subject to accurate information, required documentation, insurer acceptance and cleared premium.
How quickly can motor insurance be issued?
Straightforward motor covers may be processed promptly after the required documents, underwriting approval and premium are received. Never assume that cover exists until the certificate or formal confirmation has been issued.
What should I check immediately after receiving a policy?
Check the insured name, identification or registration details, period of insurance, asset description, vehicle use, sum insured, benefits, excesses, endorsements and contact information. Report any error immediately.
Does the cheapest premium mean poor insurance?
Not necessarily. A competitive price may be valid. The important step is confirming that the quotation offers the required cover on comparable terms and that no important benefit or disclosure is missing.
Does Imana help with claims?
Yes. Imana can guide clients through notification and documentation. The underwriting insurer remains responsible for investigating, assessing and deciding the claim.
Does Imana serve clients outside Nairobi?
Yes. Imana's digital service supports eligible clients across Kenya. Regional or international solutions—including travel, expatriate, cross-border motor and wider medical options—depend on the policy territory, residency, destination, risk location and insurer acceptance.
Final verdict: the best insurance is the cover you understand
The best insurance in Kenya is not found by chasing one company name or the lowest figure on a quotation. It is found by matching the policy to the risk, comparing equivalent benefits, reading the conditions and preparing for the possibility of a claim.
Good insurance should answer four questions clearly:
- What is covered?
- What is not covered?
- How much protection is available?
- What must happen when a claim occurs?
If those answers are unclear, keep asking questions before paying.
Compare carefully. Buy with understanding. Protect what matters.
- Compare insurance quotations online
- Explore Imana Insurance products
- Explore MyKava travel and medical solutions
- Request a quotation or speak to the team
- Call/WhatsApp: +254 796 209 402
About the author
Raymond Momanyi is the Founder & CEO of Imana Insurance Agency Kenya Ltd, a digital-first insurance intermediary based in Westlands, Nairobi. His work focuses on motor insurance, medical insurance, WIBA, PSV insurance comparison, business risk, digital insurance distribution and claims support for individuals and organisations in Kenya and East Africa.
Insurance disclaimer
This article provides general insurance information and does not replace a personalised risk assessment, insurer quotation, policy schedule or policy wording. Insurance premiums, benefits, limits, excesses, exclusions, waiting periods, provider networks, territorial scope and acceptance vary by insurer and may change. Read the issued documents and confirm current terms before purchasing. Claims are assessed by the underwriting insurer according to the policy, evidence and applicable conditions.