- Author: Raymond
- Category: Compare Insurance Quotations In Kenya
Compare Insurance Quotations in Kenya | Imana Insurance Hub
Learn about motor, medical, travel, WIBA, life, business and property insurance. Compare quotations, buy cover, claim and renew with Imana Kenya.
Author: Imana Insurance Content Team
Reviewed by: Raymond Momanyi, Founder and CEO
Last updated: 2 August 2026
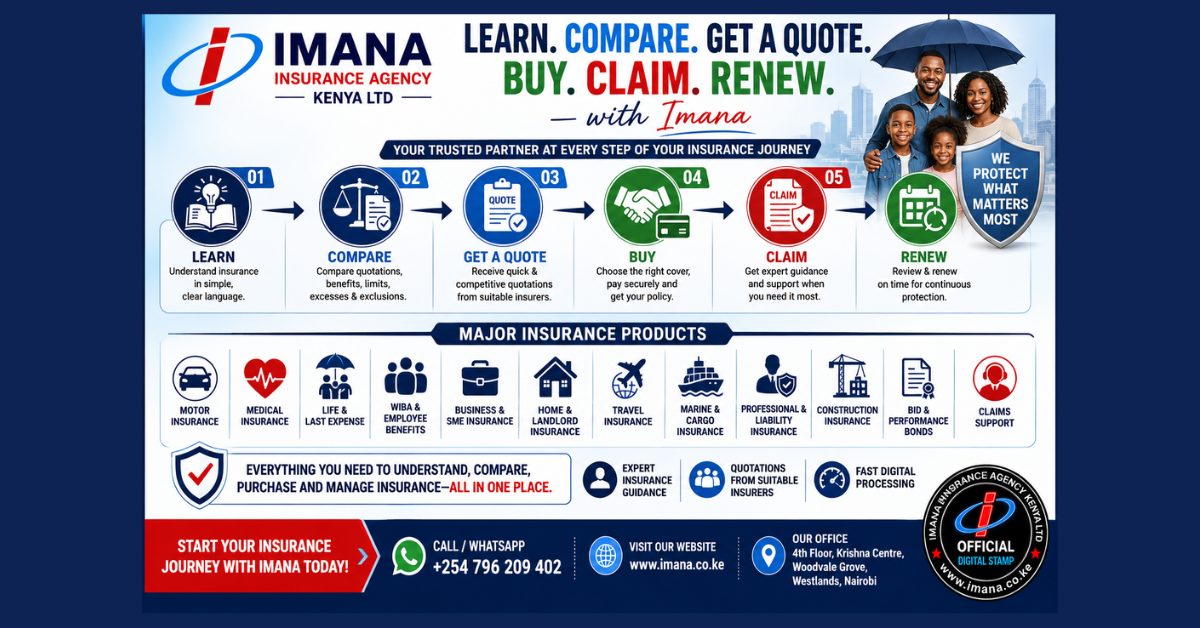
Learn. Compare. Get a Quote. Buy. Claim. Renew—with Imana
Finding suitable insurance should not require visiting multiple insurance companies, completing the same form repeatedly or trying to understand complicated policy documents alone.
The Imana Insurance Knowledge, Comparison and Quotation Hub brings insurance education, quotation comparison, digital purchasing, claims assistance and renewal support into one customer journey.
Through Imana Insurance Agency Kenya Ltd, individuals, families, SMEs, employers and larger organisations can:
- Learn how different insurance products work.
- Identify the right insurance class for a particular risk.
- Compare quotations from suitable licensed insurers.
- Review premiums, benefits, limits, excesses and exclusions.
- Request quotations digitally or through WhatsApp.
- Purchase suitable insurance and receive policy documents.
- Obtain guidance when reporting a claim.
- Review existing protection before renewal.
Imana’s website already provides dedicated quotation forms and product pages for motor, health, corporate, life, travel, WIBA, business and other insurance classes. (imana.co.ke)
Insurance should be easy to understand, practical to compare and dependable when a claim occurs.
How the Imana Insurance Journey Works
1. Learn
Start by understanding:
- What the policy covers
- What it excludes
- The maximum amount payable
- The excess you may contribute
- The documents required
- The claims process
- The conditions you must observe
Imana’s insurance guides explain technical insurance terms in practical language so that customers can make informed decisions.
2. Compare
Quotations that appear similar may have major differences in:
- Benefit limits
- Excesses
- Waiting periods
- Provider networks
- Territorial scope
- Optional extensions
- Special conditions
- Claims requirements
The purpose of comparison is not merely to find the lowest premium. It is to identify suitable protection at a sustainable price.
3. Get a Quote
Choose the relevant insurance category and submit the information required for underwriting.
Popular quotation links include:
- Motor Insurance Quote
- Health Insurance Quote
- Life Insurance Quote
- Corporate Insurance Quote
- Microinsurance Quote
- Last Expense Quote
The official quotation forms collect information relevant to each product, including vehicle details, family size, selected medical benefits, corporate insurance needs and desired cover commencement dates. (imana.co.ke)
4. Buy
After reviewing the available options:
- Select the suitable insurer and policy.
- Confirm the premium and payment terms.
- Complete the proposal or application documents.
- Pay through an approved channel.
- Obtain the official receipt.
- Review the issued certificate or policy schedule.
- Report any incorrect details immediately.
Some products may be issued digitally, while others require inspections, valuations, medical information, signed proposal forms or additional underwriting approval.
5. Claim
When an insured event occurs:
- Protect life and property.
- Report the incident promptly.
- Preserve photographs, reports and receipts.
- Notify Imana or the issuing insurer.
- Complete the appropriate claim form.
- Submit all supporting documents.
- Cooperate with assessors, investigators or medical administrators.
- Track the claim using the reference provided.
Imana provides a dedicated Insurance Claim Notification Form, and its website describes claim management as including claims-handling guidance, coverage evaluation, service-provider coordination and follow-up. (imana.co.ke)
6. Renew
Renewal should not be treated as an automatic repetition of the previous policy.
Before renewing, review:
- Changes in vehicle or property value
- Changes in vehicle use
- New family members
- Employee numbers and payroll
- Business expansion
- New stock or equipment
- Claims during the year
- Hospital requirements
- New travel destinations
- Policy exclusions
- Alternative quotations
A renewal is an opportunity to correct gaps—not merely another payment deadline.
Motor Insurance in Kenya
Motor Insurance protects vehicle owners against selected physical damage and legal liability arising from the use of a vehicle.
Imana assists customers with motor insurance for private, commercial and passenger-transport vehicles. Its official motor quotation form accommodates private cars, commercial vehicles, PSVs, motorcycles and Tuk-Tuks. (imana.co.ke)
Motor Insurance products available
Private Motor Insurance
Suitable for vehicles used for personal, social and domestic purposes.
Options may include:
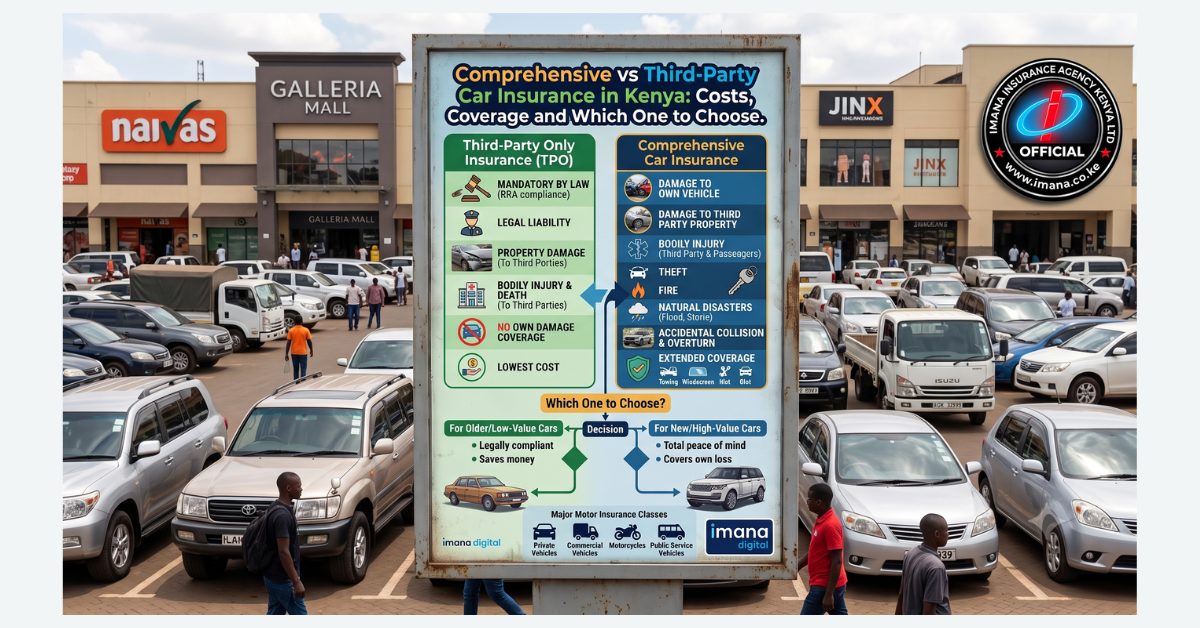
- Comprehensive Insurance
- Third-Party Only Insurance
- Third-Party, Fire and Theft
- Short-term Third-Party Insurance
Comprehensive Motor Insurance
Comprehensive cover may protect against:
- Accidental vehicle damage
- Fire
- Theft
- Third-party bodily injury
- Third-party property damage
Optional benefits may include:
- Excess Protector
- Political Violence and Terrorism
- Windscreen cover
- Entertainment-system cover
- Road rescue
- Courtesy car
- Driver Personal Accident
- Passenger Liability
- COMESA Yellow Card
Commercial Motor Insurance
Commercial vehicles should be insured according to their actual use.
Classes may include:
- Own Goods
- General Cartage
- Staff Transport Vehicles
- Special-Type Vehicles
- Delivery vehicles
- Trucks
- Prime movers
- Fleet vehicles
PSV and Passenger Transport Insurance
Passenger vehicles may include:
- Taxis
- Matatus
- Buses
- School buses
- Tour vans
- Safari vehicles
- Chauffeur-driven vehicles
- Online taxis
Imana maintains a dedicated PSV Insurance page covering passenger-transport motor solutions. (imana.co.ke)
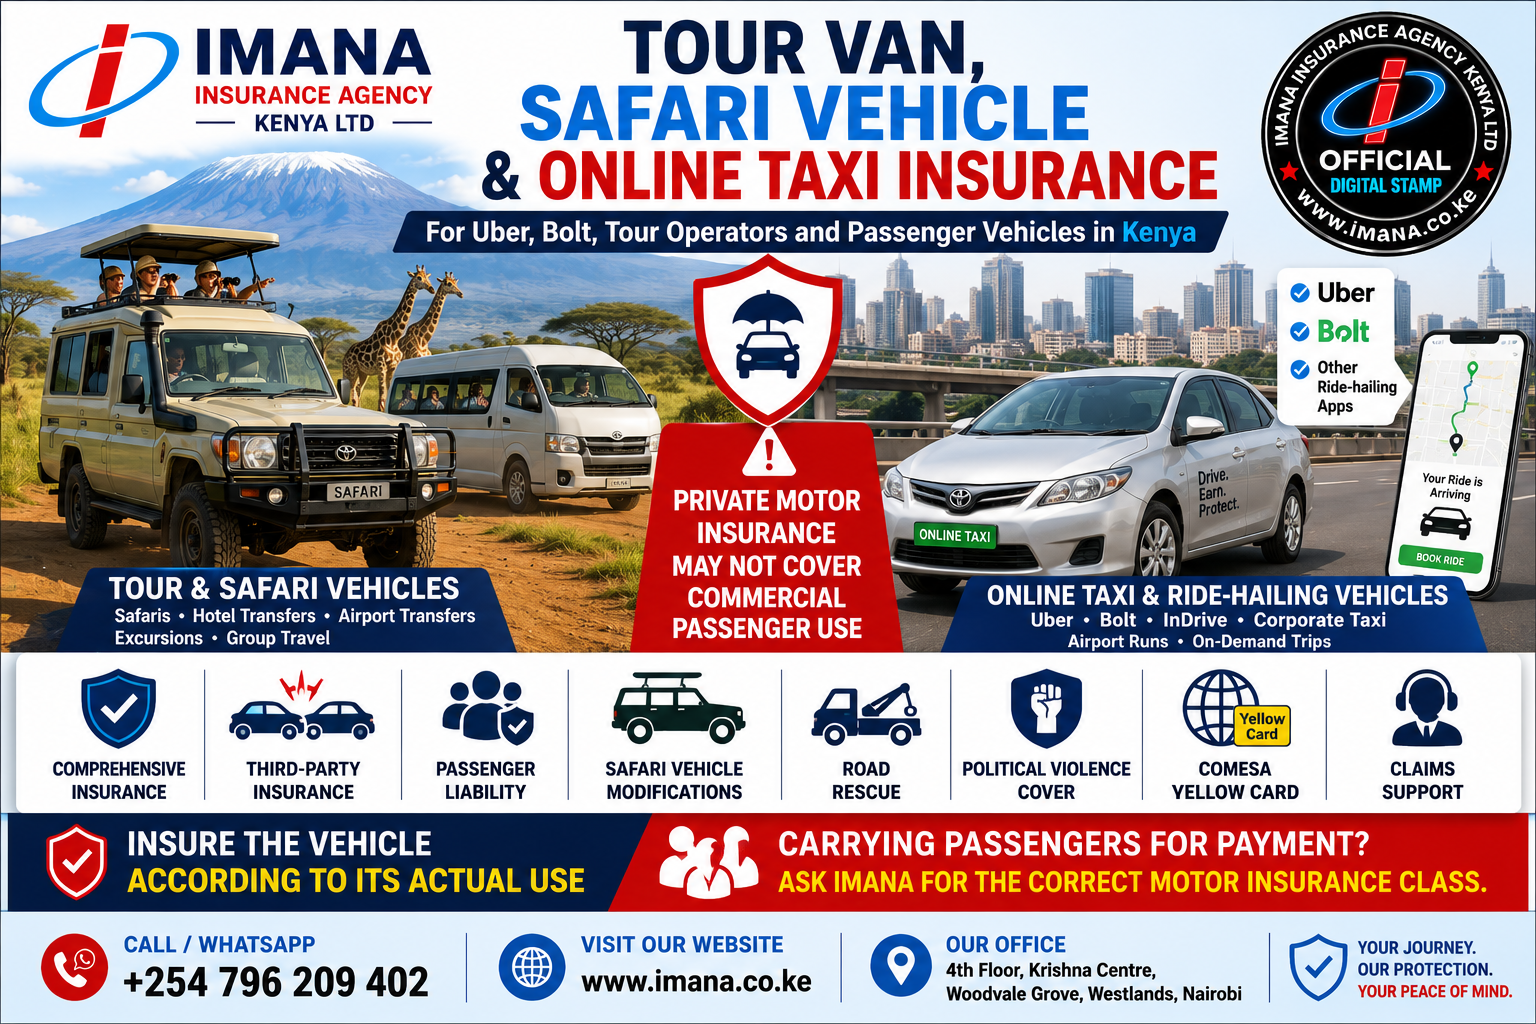
Uber, Bolt and Online Taxi Insurance
A vehicle used to carry passengers for payment should not ordinarily be insured as a car used exclusively for private purposes.
The policy should correctly reflect:
- Commercial passenger use
- Seating capacity
- Passenger Liability
- Approved drivers
- Operating area
- Required vehicle documentation
Tour Van and Safari Vehicle Insurance
Tour-service vehicles may require protection for:
- Accidental damage
- Passenger Liability
- Safari modifications
- Road rescue
- Cross-border travel
- Special equipment
- Political Violence and Terrorism
Motorcycle and Boda Boda Insurance
Motorcycle cover may be arranged for:
- Private motorcycles
- Delivery motorcycles
- Commercial motorcycles
- Boda boda operations
Fleet Insurance
A fleet arrangement may combine several declared vehicles under one coordinated programme.
The business should provide:
- Vehicle schedule
- Individual vehicle values
- Driver information
- Claims history
- Vehicle use
- Operating locations
COMESA Yellow Card Insurance
The COMESA Yellow Card provides recognised third-party motor protection for vehicles travelling through participating countries.
It does not automatically provide comprehensive own-damage protection outside Kenya. A separate territorial extension may be needed.
Motor quotation and application links
- Motor Insurance Information
- Get a Motor Insurance Quote
- Complete a Car Insurance Application
- PSV Insurance
- Report a Motor Claim
The motor application captures identification, KRA PIN, vehicle registration, value, make, model, year of manufacture, intended cover and optional benefits. (imana.co.ke)
Health and Medical Insurance in Kenya
Medical Insurance helps individuals, families and organisations manage eligible healthcare expenses.
A proper comparison should go beyond the headline inpatient limit.
Customers should examine:
- Inpatient benefit
- Outpatient benefit
- Co-payments
- Hospital network
- Maternity limit
- Dental and optical limits
- Chronic-condition benefits
- Cancer and renal benefits
- Waiting periods
- Family-shared or per-person limits
- Maximum entry and renewal ages
- Territorial scope
Imana’s health-insurance pages describe options for individuals, families, corporates and SMEs, including inpatient, outpatient, maternity, dental, optical and chronic-illness benefits. (imana.co.ke)
Medical Insurance options
Individual Medical Insurance
Cover arranged for one person based on their:
- Age
- Preferred limits
- Hospital requirements
- Medical history
- Optional benefits
Family Medical Insurance
A family plan may include:
- Principal member
- Spouse
- Children
- Other eligible dependants
Benefits may be structured as:
- Per person
- Family shared
- Hybrid arrangements
Child-Only Medical Cover
Parents may arrange medical protection for a child without necessarily insuring every adult under the same policy, subject to product rules.
Senior Citizens’ Medical Insurance
Senior medical plans should be compared carefully for:
- Entry age
- Renewal age
- Co-payments
- Chronic-condition cover
- Pre-existing-condition terms
- Hospital network
- Medical limits
Inpatient-Only Insurance
This is designed primarily for treatment requiring formal hospital admission.
Inpatient and Outpatient Insurance
This may cover eligible:
- Admission expenses
- Consultations
- Diagnostic tests
- Prescribed medicines
- Specialist treatment
- Other selected benefits
Maternity Insurance
Maternity cover may be subject to:
- Waiting periods
- Delivery sublimits
- Caesarean-section limits
- Age conditions
- Hospital-network requirements
Group Medical Insurance
Employers may insure employees and eligible dependants under one coordinated programme.
Pricing may consider:
- Number of members
- Ages
- Benefit limits
- Claims history
- Hospital network
- Co-payments
SHA Supplementary Cover
Private medical insurance may supplement statutory healthcare benefits by providing additional limits, hospital choices or benefits not fully available under the statutory package.
Medical Insurance links
- Health and Medical Insurance
- Imana Health and Micro Health Insurance
- Get a Health Insurance Quote
- Get a Microinsurance Quote
The health quotation form allows customers to select inpatient, outpatient, maternity, dental and optical requirements and indicate their preferred limits. (imana.co.ke)
Life Insurance, Personal Accident and Last Expense
Life and accident-related products help individuals and families manage the financial consequences of death, disability, illness or accidental injury.
Individual Life Insurance
Life Insurance may provide:
- Death benefit
- Income replacement
- Education funding
- Mortgage protection
- Critical-illness benefits
- Accidental-death benefits
- Savings or investment elements
Imana’s individual-life page explains that quotation preparation may consider age, occupation, required benefit and budget. (imana.co.ke)
Life Insurance links
Personal Accident Insurance
Personal Accident Insurance may provide fixed benefits following eligible accidental:
- Death
- Permanent disability
- Temporary disability
- Medical expenses
- Funeral expenses
Imana’s online Personal Accident application collects identity, occupation, cover limit, previous-accident information and desired policy duration. (imana.co.ke)
Personal Accident link
Group Personal Accident
Employers, schools, associations and other groups may arrange accident protection for several members.
Last Expense Insurance
Last Expense cover provides a fixed benefit to help a family meet funeral and burial expenses following an eligible death.
It may be arranged for:
- Individuals
- Families
- Chamas
- SACCOs
- Welfare groups
- Employers
- Associations
Last Expense links
Business and SME Insurance in Kenya
Every business has a different combination of property, liability, employee, financial and operational risks.
A suitable insurance programme should be based on what the business actually does.
Imana’s business-insurance page identifies covers including WIBA, Fire and Allied Perils, Consequential Loss, Burglary, All Risks, Product Liability and Professional Indemnity. (imana.co.ke)
Fire and Allied Perils
May protect declared property against selected risks such as:
- Fire
- Lightning
- Explosion
- Storm
- Flood
- Earthquake
- Impact
- Burst pipes
- Malicious damage
Burglary Insurance
May cover specified property stolen following forcible or violent entry into or exit from the insured premises.
All Risks Insurance
May protect selected property against accidental loss or damage, subject to exclusions.
Business Interruption Insurance
May cover eligible loss of income and continuing expenses after insured property damage interrupts business operations.
Money Insurance
May cover money:
- On the premises
- In a locked safe
- In transit
- In the custody of authorised employees
Fidelity Guarantee
May protect a business against specified direct financial loss caused by dishonest employees.
Electronic Equipment Insurance
May protect:
- Computers
- Servers
- Point-of-sale equipment
- CCTV
- Communication equipment
- Specialist electronic devices
Machinery Breakdown
May cover sudden and unforeseen internal mechanical or electrical failure of insured machinery.
Cyber Insurance
Cyber Insurance may address eligible incidents involving:
- Data breaches
- Ransomware
- System interruption
- Privacy claims
- Data-restoration expenses
- Cyber incident response
Public Liability
May cover eligible legal liability where a visitor, customer or other third party suffers accidental bodily injury or property damage connected to the business.
Product Liability
May respond to eligible claims alleging that a supplied product caused bodily injury or third-party property damage.
Goods in Transit
May protect declared goods while being transported by road.
SME Combined Insurance
Several business covers may be combined under one coordinated package.
Business links
Corporate Insurance and Employee Benefits
Corporate insurance programmes protect employees, assets, operations and organisational liability.
Imana’s corporate-insurance page lists solutions including Motor Fleet Insurance, WIBA, GPA, Group Life, construction insurance, Professional Indemnity and Marine Insurance. (imana.co.ke)
WIBA Insurance
WIBA protects employers against qualifying liabilities arising from work-related injuries and occupational diseases.
A quotation may require:
- Number of employees
- Occupations
- Annual gross payroll
- Work locations
- Claims history
Imana’s WIBA page includes claim-document guidance and positions WIBA alongside GPA, Group Life, Medical and Last Expense protection. (imana.co.ke)
WIBA link
WIBA Plus
WIBA Plus may combine statutory workplace cover with additional employee benefits, subject to the insurer’s product terms.
Group Personal Accident
May extend accident protection beyond work-related incidents, potentially on a 24-hour basis.
Group Life
May provide death benefits to nominated beneficiaries following an eligible death.
Group Medical
May provide inpatient, outpatient and optional healthcare benefits to employees and dependants.
Directors and Officers Liability
May protect directors and senior officers against eligible claims alleging wrongful acts committed in their management capacity.
Corporate Fleet Insurance
May combine multiple company vehicles under one policy schedule and coordinated claims programme.
Corporate links
Home, Property and Landlord Insurance
Property insurance protects buildings, contents and rental income against selected insured events.
Home Insurance
A domestic package may cover:
- Residential building
- Household contents
- Portable belongings
- Domestic employees
- Alternative accommodation
- Personal Liability
Landlord Insurance
A landlord may need protection for:
- Rental building
- Permanent fixtures
- Landlord-owned contents
- Loss of rent
- Property Owners’ Liability
- Burglary
- Machinery Breakdown
- Political Violence and Terrorism
Commercial Property Insurance
Commercial property may include:
- Offices
- Shops
- Warehouses
- Shopping centres
- Clinics
- Schools
- Restaurants
- Apartment developments
Important valuation principle
A building should generally be insured using its rebuilding cost rather than a selling price that includes land value.
Underinsurance may result in a reduced settlement where the policy contains an average condition.
Property quotation link
Travel and Cross-Border Insurance
Travel Insurance may protect travellers against selected emergencies and financial losses occurring before or during a journey.
Imana’s Travel Insurance page covers business, leisure, study and medical travel, including emergency medical benefits and other travel-related protection. (imana.co.ke)
Travel Insurance options
- Single-trip insurance
- Annual Multi-Trip Insurance
- Schengen Travel Insurance
- Student Travel Insurance
- Senior Travel Insurance
- Business Travel Insurance
- Group Travel Insurance
- Inbound Travel Health Insurance
Benefits may include
- Emergency medical expenses
- Hospitalisation
- Medical evacuation
- Repatriation
- Trip cancellation
- Trip curtailment
- Flight delay
- Lost or delayed baggage
- Passport loss
- Personal Accident
- Personal Liability
Important comparison questions
Before buying, ask:
- Does the policy meet the destination or visa requirements?
- What is the emergency medical limit?
- Are pre-existing conditions covered?
- What excess applies?
- Are baggage limits per item?
- Is cancellation included?
- What is the maximum trip duration?
- What activities are excluded?
Travel link
Marine, Cargo and Transport Insurance
Marine Insurance protects goods transported through sea, air, rail or road, depending on the selected policy.
Imana’s Marine Insurance page focuses on protecting cargo from departure until arrival and connecting customers to suitable marine insurers. (imana.co.ke)
Marine Cargo Insurance
May protect imports, exports and other shipments against specified risks during transit.
Marine Open Cover
Suitable for businesses making regular shipments throughout the policy period.
Single-Shipment Marine Cover
Suitable for one declared consignment.
Goods in Transit
Provides protection for goods carried by road within the agreed territory.
Carrier’s Liability
May protect a transport operator against eligible legal liability involving customers’ goods.
Warehouse Insurance
May protect goods and other property stored at declared locations.
Marine link
Construction and Engineering Insurance
Construction projects create risks involving works, equipment, employees and the public.
Contractors All Risks
May cover:
- Contract works
- Construction materials
- Temporary works
- Accidental project damage
- Third-party liability
Erection All Risks
May protect machinery and equipment during installation, testing and commissioning.
Contractors’ Plant and Machinery
May cover:
- Excavators
- Cranes
- Loaders
- Concrete mixers
- Compressors
- Other construction equipment
Machinery Breakdown
May protect completed machinery against sudden internal mechanical or electrical failure.
Electronic Equipment
May protect specialist electronic and control equipment.
Construction-related supporting covers
A project may also require:
- WIBA
- Public Liability
- Professional Indemnity
- Performance Bond
- Advance Payment Bond
- Marine Cargo
- Goods in Transit
Construction quotation link
Professional and Liability Insurance
Liability insurance protects individuals and organisations against eligible legal claims.
Professional Indemnity
Professional Indemnity may protect against claims alleging:
- Negligent professional advice
- Errors
- Omissions
- Failure to perform professional duties
- Loss of client documents
- Breach of confidentiality where included
Imana maintains a dedicated Professional Indemnity page describing cover for professional risks and different industries. (imana.co.ke)
Professional Indemnity link
Medical Malpractice
A specialised Professional Indemnity policy for healthcare practitioners and facilities.
Public Liability
Protects against eligible general third-party bodily injury or property-damage claims.
Product Liability
Protects against eligible claims involving products supplied by the insured business.
Employers’ Liability
May provide additional protection for employee-related liability beyond the principal WIBA framework, subject to the selected policy.
Tour Operator’s Liability
May protect tour companies against eligible legal claims arising from their operations.
Cyber Liability
May address privacy, data-breach and network-security claims.
Bid Bonds, Performance Bonds and Guarantees
Insurance bonds support tender and contractual obligations.
Bid Bond
Submitted with a tender to secure the bidder’s obligations during the procurement stage.
Performance Bond
Submitted after contract award to guarantee proper performance of the contract.
Advance Payment Bond
Guarantees repayment or proper application of an advance paid to the contractor.
Retention Bond
May replace retention money that would otherwise be withheld from the contractor.
Immigration Bond
May be required for specified immigration or work-permit purposes.
Customs Bond
Supports specified customs and revenue obligations.
Information required
An application may require:
- Tender document
- Bond wording
- Required amount
- Beneficiary
- Validity period
- Company documents
- Financial statements
- Bank statements
- Previous contract experience
- Award letter
- Contract
- Collateral or indemnity
Issuance remains subject to insurer underwriting approval.
Bond quotation links
Microinsurance for Individuals and SMEs
Microinsurance provides simplified protection using relatively low premiums and limited benefits.
Potential products may include:
- Personal Accident
- Last Expense
- Hospital Cash
- Crop and Livestock Insurance
- Home and belongings
- Tools of trade
- Credit Life
- SME protection
Microinsurance may be useful as entry-level protection, but a growing business should review whether its assets and liabilities have exceeded the product’s benefit limits.
Microinsurance link
Insurance for Specialised Sectors
Imana can help structure insurance programmes for different organisations and professions.
Schools
A school may require:
- Student Personal Accident
- WIBA
- Property Insurance
- Public Liability
- School Bus Insurance
- Business Interruption
- Cyber Insurance
- Group Medical
Clinics and Pharmacies
Healthcare businesses may require:
- Medical Malpractice
- Professional Indemnity
- Product Liability
- Public Liability
- WIBA
- Pharmaceutical stock cover
- Deterioration of Stock
- Cyber Insurance
- Business Interruption
Hotels and Airbnb Properties
Possible covers include:
- Buildings and Contents
- Public Liability
- Loss of income
- Guest-related liability
- Burglary
- Fidelity Guarantee
- WIBA
- Product Liability for food services
Logistics Businesses
A logistics programme may combine:
- Commercial Motor
- Marine Cargo
- Goods in Transit
- Carrier’s Liability
- Warehouse Insurance
- WIBA
- Public Liability
- Fidelity Guarantee
Contractors
A contractor may require:
- Contractors All Risks
- Plant and Machinery
- WIBA
- Public Liability
- Professional Indemnity
- Bid and Performance Bonds
- Commercial Motor
Professional Firms
Professional firms may require:
- Professional Indemnity
- Cyber Insurance
- WIBA
- Group Medical
- Office Contents
- Public Liability
- Fidelity Guarantee
Specialised business quotation
How to Compare Insurance Quotations Properly
Never compare premium alone.
Use the following checklist.
1. Confirm the insurance class
The policy must accurately reflect the risk.
Examples:
- Private car versus online taxi
- Home versus rental property
- Office versus clinic
- General shop versus pharmacy
- Private vehicle versus tour van
2. Compare the sums insured
Ensure that vehicle, property, stock and equipment values are realistic.
3. Review the benefits
Check what each quotation actually includes.
4. Compare sublimits
A large overall limit may contain smaller limits for specific benefits.
5. Review excesses
An excess is the amount the policyholder may contribute toward a claim.
6. Check exclusions
Look for risks or circumstances the policy does not cover.
7. Review waiting periods
These are particularly important in Medical, Life, Last Expense and Maternity Insurance.
8. Compare provider networks
For medical cover, confirm:
- Preferred hospitals
- Co-payment requirements
- Specialist facilities
- Emergency providers
9. Check territorial limits
Confirm whether the policy applies:
- Only in Kenya
- Within East Africa
- Across COMESA countries
- Worldwide
10. Review claims requirements
Understand:
- Notification period
- Required reports
- Documents
- Authorisation rules
- Applicable excesses
A suitable quotation should be affordable, clear and capable of responding to the risk you intended to insure.
Insurance Claims Support
Insurance becomes most valuable when a claim occurs.
Imana may assist customers with:
- Initial claim notification
- Claim-document checklists
- Claim-form guidance
- Police-report requirements
- Medical-document guidance
- Assessment coordination
- Repair-authorisation follow-up
- Insurer communication
- Settlement-status follow-up
The insurer remains responsible for assessing and determining the claim under the policy terms.
Important claim steps
- Report promptly.
- Protect people and property.
- Preserve evidence.
- Avoid unauthorised repairs.
- Keep receipts and reports.
- Do not admit legal liability.
- Respond to document requests.
- Retain copies of submissions.
Claim link
Renewing Insurance Through Imana
A renewal review should begin before the current policy expires.
Motor renewal review
Check:
- Current vehicle value
- Actual vehicle use
- Drivers
- Claims history
- Optional benefits
- COMESA requirements
Medical renewal review
Check:
- Family membership
- Preferred hospitals
- Co-payments
- Claims utilisation
- Benefit limits
- New medical needs
Business renewal review
Check:
- Updated stock
- New equipment
- Turnover
- Employee payroll
- New branches
- New services
- Liability limits
Property renewal review
Check:
- Rebuilding value
- Renovations
- Contents
- Rental income
- Vacancy
- Security controls
Send the existing schedule or renewal notice early enough for proper comparison.
Why Choose Imana Insurance Agency Kenya Ltd?
Multiple insurance categories in one place
Customers can obtain assistance with personal, family, business, corporate and specialised insurance.
Quotation comparison
Imana helps customers compare suitable quotations rather than depending on one unexplained option.
Digital accessibility
Many enquiries, quotations, document submissions and policy processes can begin digitally.
Claims assistance
The relationship continues after policy issuance through claim notification and follow-up guidance.
Convenient Westlands location
Imana operates from 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi. The official website lists the office, email and contact numbers and provides online contact and quotation forms. (imana.co.ke)
Licensed insurance intermediary
Imana’s official company profile states that it was registered as an insurance agency in November 2020 and licensed as an insurance agency in December 2020. (imana.co.ke)
Frequently Asked Questions
Can Imana compare insurance quotations from different insurers?
Yes. Imana helps customers review premiums, benefits, excesses, limits and exclusions from suitable insurers.
Can I request an insurance quotation online?
Yes. Imana provides online forms for Motor, Health, Life, Corporate, Microinsurance and Last Expense quotations. (imana.co.ke)
Can I buy insurance without visiting the office?
Many processes can be completed digitally, although some risks require inspections, valuations, medical information, signed documents or further underwriting.
How quickly can I receive a quotation?
Timing depends on:
- Type of insurance
- Complexity of the risk
- Completeness of the information
- Insurer response
- Required inspections or medical information
Is the cheapest insurance quotation always the best?
No. A lower premium may come with:
- Higher excesses
- Lower benefits
- Restrictive conditions
- Important exclusions
- A narrower provider network
Does Imana assist with claims?
Yes. Imana can help with notification, document requirements and follow-up. The issuing insurer remains responsible for making the claim decision.
Where is Imana located?
Imana Insurance Agency Kenya Ltd is located at 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi. (imana.co.ke)
Can customers outside Nairobi obtain insurance?
Many quotation and policy processes can be handled digitally for customers across Kenya, subject to insurer requirements.
What documents are normally required?
Requirements depend on the policy but may include:
- National ID or passport
- KRA PIN
- Logbook
- Property valuation
- Employee schedule
- Payroll
- Medical information
- Company registration documents
- Tender or contract documents
Can Imana arrange insurance for an SME?
Yes. SMEs may obtain quotations for property, WIBA, liability, business interruption, cyber, motor and other relevant covers.
Can Imana help with medical insurance?
Yes. Imana assists individuals, families, senior citizens, children, employers and groups with medical-insurance comparison.
Can Imana arrange Bid Bonds and Performance Bonds?
Yes, subject to insurer underwriting, complete documents, acceptable wording, financial capacity and any collateral requirements.
Start Your Insurance Journey With Imana
Whether you need protection for your:
- Vehicle
- Family
- Health
- Employees
- Business
- Home
- Rental property
- Journey
- Cargo
- Profession
- Construction project
- Tender or contract
Imana Insurance Agency Kenya Ltd can help you understand the available options and request suitable quotations.
Quick links
- Motor Insurance Quote
- Health Insurance Quote
- Life Insurance Quote
- Corporate Insurance Quote
- Microinsurance Quote
- Last Expense Quote
- Travel Insurance
- Marine Insurance
- WIBA Insurance
- Professional Indemnity
- Report a Claim
- Contact Imana
Contact Imana Insurance Agency Kenya Ltd
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Email: insurance@imana.co.ke
Website: www.imana.co.ke
Learn. Compare. Get a Quote. Buy. Claim. Renew—with Imana.
Insurance premiums, benefits, underwriting requirements, policy limits, excesses, provider networks, waiting periods and exclusions vary between insurers. Product availability and website links may change. Obtain a current written quotation, policy schedule and complete policy wording before purchasing insurance.