- Author: Raymond
- Category: Corporate & SME Insurance in Kenya
Public Liability Insurance in Kenya | Business Liability Cover
Learn how Public Liability Insurance in Kenya protects businesses against third-party injury, accidental death, property damage and approved legal costs. Compare quotations through Imana Insurance Agency Kenya Ltd.
What Happens When a Customer Is Injured at Your Business?
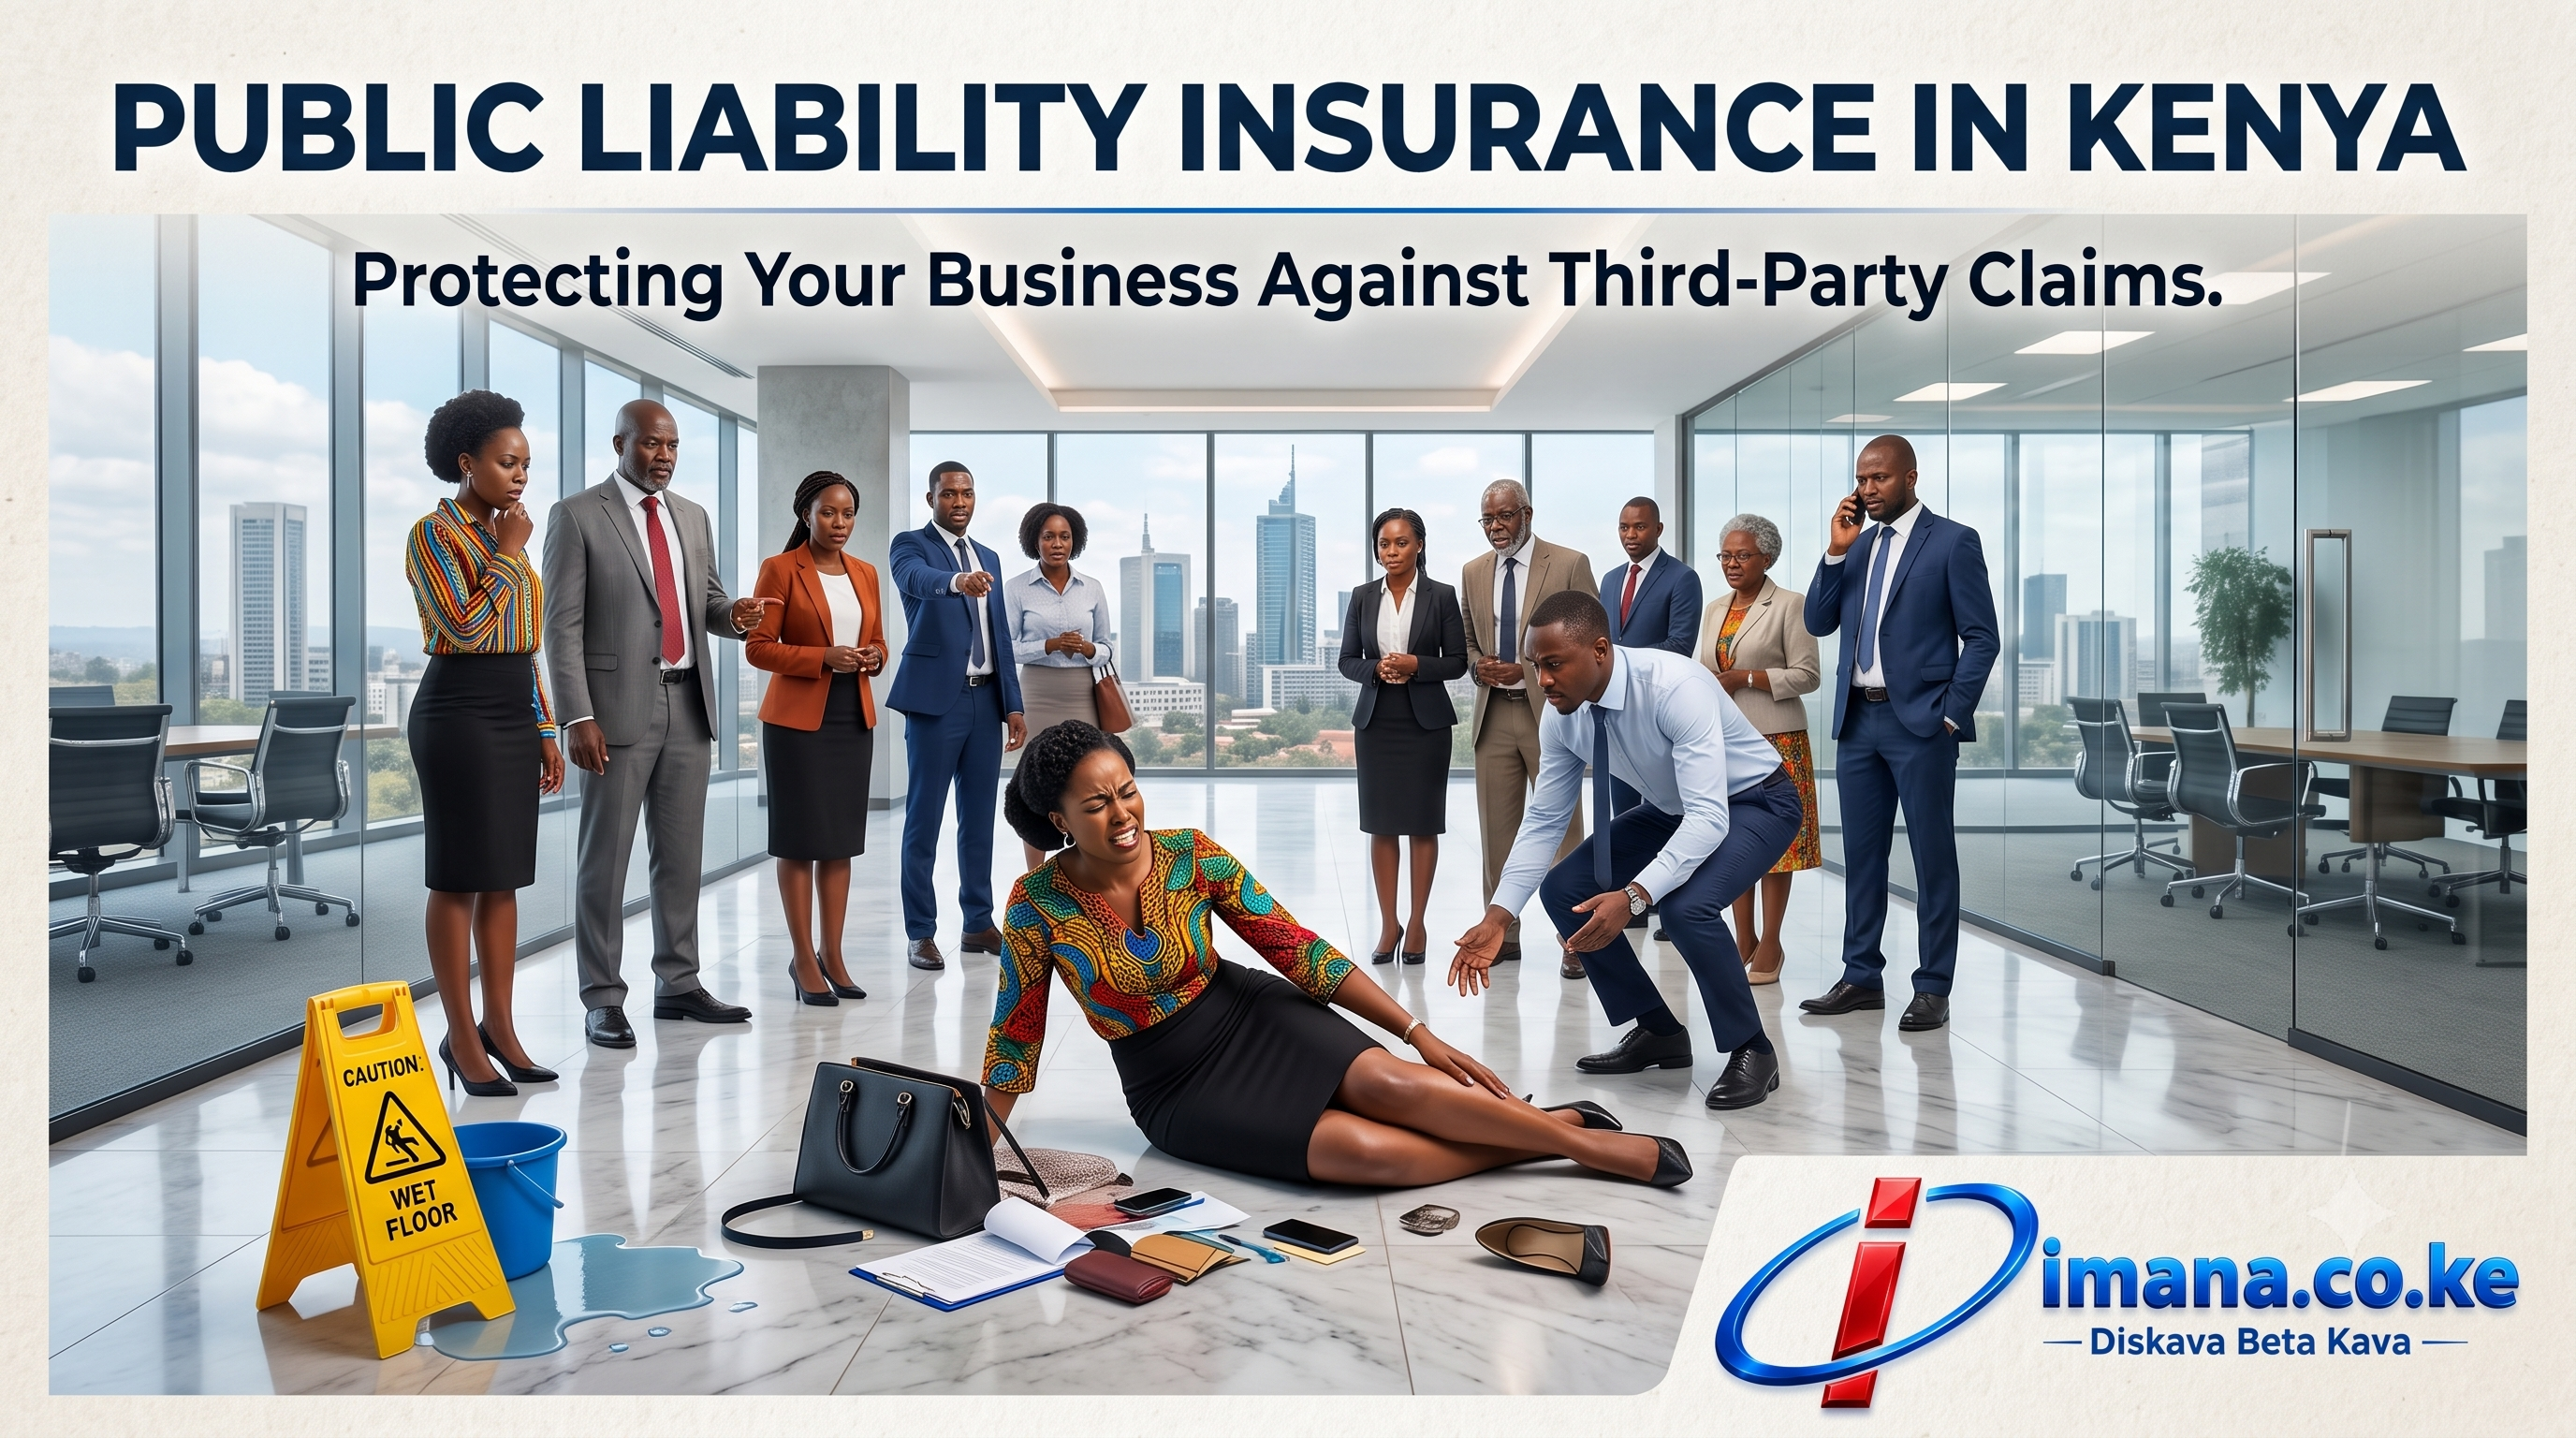
Imagine a customer visits your shop and slips on a wet floor.
A delivery person enters your warehouse and is injured by falling stock. A loose signboard falls onto a visitor’s vehicle. Water leaks from your office and damages equipment belonging to another tenant.
Even where an incident appears minor, the affected person may demand compensation for:
- Medical expenses
- Lost income
- Disability
- Property repairs
- Replacement costs
- Legal expenses
- Other proven financial losses
The business may also need to appoint lawyers, investigate the incident and defend itself in court.
These costs may be difficult for an SME to meet from ordinary cash flow.
Public Liability Insurance is designed to protect a business against eligible legal liabilities arising when a member of the public suffers accidental bodily injury, accidental death or property damage connected to the insured business activities.
Your property insurance protects what belongs to your business. Public Liability Insurance helps protect your business when someone else alleges that your operations caused them harm.
What Is Public Liability Insurance?
Public Liability Insurance covers specified legal liabilities to third parties arising from the insured’s business operations, premises or activities.
Depending on the policy, it may respond when a customer, visitor, supplier, contractor or other member of the public experiences:
- Accidental bodily injury
- Accidental death
- Accidental loss of property
- Accidental damage to property
The policy may also meet legal expenses incurred with the insurer’s prior written approval.
CIC’s current public-liability product description identifies bodily injury, accidental death, property loss or damage and insurer-approved legal expenses among the principal areas of protection. Britam similarly categorises public liability as a form of liability insurance against third-party claims. (CIC Kenya)
Public Liability Insurance is not a general fund for every complaint made against a business. A valid claim must fall within the policy wording and normally requires the insured business to be legally liable.
The Legal Duty Businesses Owe Visitors
Kenya’s Occupiers’ Liability Act regulates the duty an occupier of premises owes visitors in relation to dangers caused by the state of the premises or by things done—or not done—there.
The law provides that an occupier owes visitors a common duty of care: taking such care as is reasonable in the circumstances to ensure that visitors are reasonably safe while using the premises for the purpose for which they were invited or permitted to be there. The Act can also apply to fixed and movable structures, including vehicles, vessels and aircraft. (Kenya Law)
This legal context is relevant to businesses operating:
- Shops
- Offices
- Hotels
- Restaurants
- Warehouses
- Schools
- Clinics
- Shopping centres
- Apartment buildings
- Construction sites
- Event venues
- Recreational facilities
A warning sign does not automatically remove liability. Under the Occupiers’ Liability Act, the adequacy of a warning depends on whether it was sufficient in the circumstances to enable the visitor to remain reasonably safe. (Kenya Law)
Public Liability Insurance helps manage the financial consequences of eligible claims. It does not remove the business’s responsibility to maintain safe premises.
Is Public Liability Insurance Compulsory in Kenya?
Public Liability Insurance is not automatically compulsory for every business in Kenya.
However, it may be required by:
- A landlord
- A shopping mall
- A commercial lease
- A county authority
- A principal contractor
- A client contract
- A tender document
- An event venue
- A financier
- An industry regulator
- A project owner
Businesses with frequent public interaction should consider the cover even where no contract expressly requires it.
A business should also distinguish public liability from insurance that is legally compulsory in specific situations. For example, employers must maintain WIBA insurance for statutory liabilities involving employees, while motor vehicles used on public roads must have the prescribed motor third-party protection. Public Liability Insurance does not replace either of those policies. (Kenya Law)
Who Is a Third Party?
A third party is generally someone other than the policyholder or insurer who may suffer injury or property damage connected to the insured business.
Depending on the circumstances, third parties may include:
- Customers
- Visitors
- Suppliers
- Delivery personnel
- Neighbouring businesses
- Tenants
- Landlords
- Event attendees
- Subcontractors
- Members of the public
- Property owners at sites where the insured works
Employees are not ordinarily treated as public-liability claimants for workplace injuries because employee-related risks are addressed through WIBA and, where relevant, Employer’s Liability or Group Personal Accident insurance.
What Does Public Liability Insurance Cover?
The exact benefits differ between insurers, but a typical policy may include the following.
1. Accidental Bodily Injury
The policy may respond where a third party suffers an accidental physical injury connected to the business premises or operations.
Examples include:
- A customer slipping on a wet supermarket floor
- A visitor falling on a broken staircase
- A shopper being injured by falling merchandise
- A guest being hurt by damaged furniture
- A pedestrian being injured by materials from a work site
- A contractor being injured in a common area
The claimant must ordinarily establish that the insured business was legally responsible.
2. Accidental Death
Where an insured incident results in a third party’s death, the policy may respond to eligible legal claims made by the deceased person’s estate or dependants.
The insurer will assess:
- How the incident occurred
- Whether the insured was negligent
- Whether the event occurred during the policy period
- Whether the business activity was declared
- The applicable liability limit
- Relevant exclusions
- Supporting legal and medical evidence
3. Third-Party Property Damage
The policy may cover legal liability for accidental damage to property belonging to someone else.
Examples include:
- A contractor damaging a client’s wall
- Water escaping from an office and damaging another tenant’s stock
- A business sign falling onto a customer’s car
- An employee accidentally damaging property while working at a client’s premises
- Debris from a construction activity damaging an adjacent building
- Equipment at an event damaging the venue
Property owned by the insured is not protected by Public Liability Insurance. The business requires property insurance for its own assets.
4. Legal Defence Costs
Liability claims can result in substantial legal expenses even where the insured ultimately proves that it was not responsible.
A policy may cover:
- Approved lawyers’ fees
- Court expenses
- Investigation expenses
- Expert-witness costs
- Other authorised defence costs
These costs are normally payable only with the insurer’s written consent.
The business should not appoint lawyers, admit liability or negotiate a settlement without first notifying the insurer.
5. Claimant’s Costs and Compensation
Where the insured is found legally liable, the policy may pay eligible compensation and court-awarded costs up to the applicable policy limit.
Whether defence costs are included within or paid in addition to the liability limit depends on the policy wording.
Practical Public Liability Claim Examples
Example 1: Slip-and-Fall Accident
A restaurant employee mops the entrance but does not display a warning sign.
A customer slips, fractures an arm and requires surgery.
The customer alleges that the restaurant failed to provide a reasonably safe environment. Public Liability Insurance may respond to eligible compensation and approved legal costs, subject to the policy terms.
Example 2: Falling Stock in a Shop
Heavy goods are stacked incorrectly on a shelf and fall onto a shopper.
The shopper suffers an injury and cannot work for several weeks.
The claim may include:
- Medical treatment
- Proven lost income
- Rehabilitation costs
- Legal expenses
Example 3: Damage at a Client’s Premises
A cleaning company’s employee accidentally knocks over and damages specialised equipment at a client’s office.
A Public Liability policy may respond where damage arising from the business activity falls within the cover.
Property in the insured’s custody or control may, however, be restricted or excluded unless specifically extended.
Example 4: Signboard Damage
Strong winds loosen a poorly maintained business sign, which falls onto a vehicle parked outside.
If the vehicle owner alleges negligent installation or maintenance, the policy may respond to the eligible property-damage claim.
Example 5: Neighbouring Property Damage
A contractor carrying out renovations accidentally damages a water pipe, flooding the neighbouring tenant’s premises.
The resulting third-party property damage may trigger the liability section, while damage to the contractor’s own works would require another policy such as Contractors All Risks Insurance.
Who Needs Public Liability Insurance?
Retail Shops and Supermarkets
Customers, suppliers and delivery teams visit the premises throughout the day.
Relevant risks include:
- Slippery floors
- Falling displays
- Poorly stacked goods
- Defective furniture
- Congested aisles
- Unsafe entrances
Restaurants and Cafés
Possible risks include:
- Burns
- Slips and falls
- Broken furniture
- Falling fixtures
- Damage caused by leaks
- Customer injuries on the premises
Food-related illness caused by a supplied product may require Product Liability Insurance rather than ordinary Public Liability Insurance.
Hotels and Airbnb Properties
Hotels, serviced apartments and short-term accommodation providers interact directly with guests.
Possible incidents include:
- Falls
- Swimming-pool accidents
- Faulty balconies
- Damaged furniture
- Inadequate lighting
- Injuries in common areas
- Guest-property damage
Offices and Professional Firms
Even a low-risk office receives:
- Clients
- Couriers
- Maintenance contractors
- Suppliers
- Job applicants
- Other visitors
A loose cable, damaged chair, unsafe staircase or falling fixture can create a claim.
Schools and Educational Institutions
Public-liability risks may involve:
- Parents
- Visitors
- Contractors
- Spectators
- Students in circumstances outside the scope of other policies
- Third-party property
Schools should also consider Student Personal Accident, WIBA, Motor, Property and Professional Indemnity insurance where relevant.
Clinics, Hospitals and Pharmacies
Public liability may protect against accidents involving visitors or property.
Claims arising directly from professional medical treatment, diagnosis or advice generally require Medical Malpractice or Professional Indemnity Insurance.
Property Owners and Managers
Landlords and property managers may face claims arising from:
- Common stairways
- Lifts
- Parking areas
- Gates
- Roofs
- Balconies
- Shared electrical installations
- Poorly maintained common spaces
The Occupiers’ Liability Act also addresses circumstances in which a landlord with maintenance or repair obligations may owe duties relating to dangers caused by failure to perform those obligations. (Kenya Law)
Contractors and Tradespeople
Contractors frequently work on property belonging to clients.
Public liability may be relevant to:
- Electricians
- Plumbers
- Painters
- Interior designers
- Cleaners
- Security companies
- Installers
- Renovation contractors
- Landscapers
- Event contractors
Construction projects may require a broader Contractors All Risks policy with a third-party liability section.
Event Organisers
Conferences, concerts, exhibitions, weddings, trade fairs and corporate events can expose organisers to claims involving:
- Temporary structures
- Crowds
- Cables
- Staging
- Lighting
- Catering
- Seating
- Exhibitor property
The venue may require evidence of Public Liability Insurance before allowing the event to proceed.
Manufacturers and Distributors
Public liability may cover incidents arising from premises and operations.
Injury or property damage caused by a product after it has left the business’s possession may require Product Liability Insurance.
Public Liability vs Other Liability Covers
Public Liability vs Product Liability
Public Liability Insurance addresses eligible injury or property damage arising from the business’s premises or activities.
Product Liability Insurance addresses eligible injury or property damage caused by products manufactured, sold, supplied or distributed by the insured.
A restaurant may need both:
- Public liability for a customer slipping on the floor
- Product liability for illness allegedly caused by contaminated food
Public Liability vs Professional Indemnity
Public Liability Insurance primarily concerns accidental bodily injury and property damage.
Professional Indemnity Insurance addresses claims arising from professional negligence, errors, omissions, designs or advice.
An architect whose visitor trips at the office may face a public-liability claim. A claim alleging negligent architectural design would fall under Professional Indemnity Insurance.
Public Liability vs Employer’s Liability
Public liability relates to third parties.
Employer’s Liability concerns claims by employees alleging employer negligence or common-law liability.
Workplace injury compensation is primarily addressed through WIBA, which every employer is required to maintain. (Kenya Law)
Public Liability vs Motor Third Party
Motor Third-Party Insurance addresses liabilities arising from the use of an insured vehicle on a road.
Public Liability Insurance generally excludes liabilities that should be covered under compulsory motor insurance.
Public Liability vs Property Insurance
Property insurance covers the business’s own:
- Buildings
- Contents
- Stock
- Machinery
- Equipment
Public liability protects against eligible legal claims involving third-party injury or property damage.
Public Liability vs Directors and Officers Liability
Directors and Officers Insurance addresses claims made personally against directors and officers for alleged wrongful management acts.
It does not replace Public Liability Insurance. Britam lists public, product, employer’s, directors and officers, carriers and trustees’ liability as distinct liability classes. (Britam)
What Is Not Normally Covered?
Common exclusions may include:
- Deliberate injury or damage
- Criminal acts
- Contractual liability assumed beyond ordinary legal liability
- Employee injuries covered under WIBA or Employer’s Liability
- Motor-vehicle liabilities
- Professional negligence
- Defective products
- Pollution unless specifically extended
- Damage to the insured’s own property
- Property in the insured’s custody or control
- Fines and penalties
- War and terrorism
- Cyber incidents
- Asbestos-related claims
- Gradual damage
- Known incidents predating the policy
- Activities not declared to the insurer
- Claims outside the territorial limits
The exclusions vary between insurers.
A business should not rely on a summary or poster alone. The quotation, policy schedule and complete wording determine the actual protection.
Understanding Public Liability Limits
The limit of liability is the maximum amount the insurer may pay under the policy, subject to its terms.
The policy may specify:
- Limit for any one occurrence
- Overall annual aggregate
- Property-damage limit
- Pollution sublimit
- Legal-cost limit
- Specific activity limits
Possible limits may range from modest amounts suitable for small shops to hundreds of millions of shillings for major contractors, malls, hotels and infrastructure projects.
The appropriate limit depends on:
- Number of visitors
- Type of business
- Severity of possible injuries
- Value of neighbouring property
- Contractual requirements
- Size of events
- Number of branches
- Work performed away from the premises
- Client requirements
The cheapest limit is not always suitable.
A business located inside a high-value commercial building may have a much larger property-damage exposure than a small standalone shop.
What Is a Public Liability Excess?
An excess is the amount the insured business contributes towards an approved claim.
A policy may apply:
- One fixed excess
- A percentage of the claim
- A higher property-damage excess
- A special excess for particular activities
- No excess for certain bodily-injury claims
For example, where an approved property-damage claim is KSh 500,000 and the policy excess is KSh 50,000, the insured may meet the first KSh 50,000, subject to the policy terms.
Compare both the premium and excess.
A low-cost policy with a very high excess may place a difficult financial burden on a small business when a claim occurs.
How Much Does Public Liability Insurance Cost in Kenya?
There is no universal price.
Premiums depend on:
- Nature of the business
- Annual turnover
- Number of visitors
- Business location
- Number of branches
- Required liability limit
- Claims history
- Type of work performed
- Work away from the premises
- Use of subcontractors
- Health and safety controls
- Contract requirements
- Selected extensions
- Policy excess
A small office-based consultancy may pay less than:
- A busy shopping mall
- A nightclub
- A construction company
- A hotel
- A school
- An event organiser
- A manufacturer
- A contractor working at airports or industrial plants
Insurers will assess both the probability of a claim and the possible severity of the loss.
Information Required for a Quotation
A business may need to provide:
- Registered business name
- KRA PIN
- Nature of operations
- Physical address
- Number of branches
- Annual turnover
- Number of employees
- Estimated visitor numbers
- Required liability limit
- Claims history
- Contracts requiring insurance
- Work performed away from the premises
- Subcontractor details
- Safety procedures
- Property-owner or landlord requirements
- Existing policy schedule
Contractors may also need to provide:
- Contract value
- Project duration
- Site location
- Description of work
- Principal’s name
- Surrounding-property exposure
- Required limit
- Contract wording
Accurate information allows insurers to price the actual exposure.
How to Reduce Public Liability Risks
Insurance should be supported by practical safety measures.
Maintain Safe Floors and Walkways
- Clean spills quickly
- Display warning signs
- Repair damaged tiles
- Keep corridors clear
- Provide adequate lighting
Inspect the Premises Regularly
Check:
- Staircases
- Handrails
- Balconies
- Shelves
- Ceilings
- Signboards
- Gates
- Lifts
- Electrical installations
Control Contractors
Confirm that contractors are:
- Competent
- Properly supervised
- Appropriately insured
- Following safety procedures
The Occupiers’ Liability Act recognises that use of an independent contractor does not automatically settle every liability question; the occupier’s reasonableness in appointing a competent contractor and checking the work may still be relevant. (Kenya Law)
Record Incidents
Maintain:
- Accident reports
- Witness details
- CCTV recordings
- Photographs
- Maintenance records
- Cleaning schedules
- Security reports
- Medical-assistance records
Train Employees
Staff should understand:
- Emergency procedures
- Customer safety
- Spill response
- Incident reporting
- Crowd management
- Fire safety
- When not to admit liability
Display Appropriate Warnings
Warnings can help visitors avoid hazards, but they must be clear, visible and adequate for the specific risk.
Maintain Emergency Equipment
Depending on the business, this may include:
- Fire extinguishers
- First-aid kits
- Emergency lighting
- Exit signs
- Barriers
- Alarm systems
What to Do After a Public Liability Incident
1. Assist the Injured Person
Obtain appropriate medical or emergency assistance.
2. Secure the Area
Prevent further injury or damage.
3. Record the Incident
Capture:
- Date
- Time
- Location
- What happened
- Witnesses
- Photographs
- CCTV
- Weather conditions
- Safety measures in place
4. Notify the Insurer or Intermediary
Report the incident immediately, even where no formal demand has been received.
5. Do Not Admit Liability
Be helpful and professional, but do not promise payment, accept legal responsibility or negotiate settlement without insurer approval.
6. Preserve Evidence
Do not destroy:
- Damaged equipment
- CCTV recordings
- Inspection logs
- Cleaning schedules
- Contracts
- Witness contacts
7. Forward Legal Documents Immediately
Send demand letters, summonses and other legal correspondence to the insurer without delay.
Documents Required for a Public Liability Claim
Depending on the incident, the insurer may request:
- Completed claim form
- Incident report
- Police report
- Witness statements
- Photographs or videos
- CCTV recordings
- Medical reports
- Treatment invoices
- Property-repair quotations
- Proof of ownership
- Demand letter
- Court documents
- Maintenance records
- Contracts
- Safety inspection records
- Business permits
- Communication with the claimant
The insurer may appoint a loss adjuster, investigator, lawyer, engineer or medical specialist.
Common Mistakes Businesses Make
Assuming Small Businesses Cannot Face Large Claims
A small business can cause serious injury or substantial property damage.
Buying an Inadequate Liability Limit
The limit should reflect the possible severity of a claim, not only the premium available.
Failing to Declare All Activities
A company insured as an office consultant may not be covered for undeclared construction work.
Ignoring Work Away from the Premises
Confirm whether the policy covers activities at customer sites.
Admitting Liability Immediately
An apology or offer to pay may affect the insurer’s ability to investigate and defend the claim.
Reporting Incidents Late
A minor incident may develop into a major claim months later.
Confusing Public Liability with Professional Indemnity
The policies address different risks.
Assuming a Warning Sign Removes Liability
The warning must be adequate in the circumstances. (Kenya Law)
Allowing the Policy to Lapse
Claims must ordinarily arise from incidents occurring within the insured period.
How to Compare Public Liability Quotations
Ensure every insurer receives the same:
- Business description
- Turnover
- Locations
- Required liability limit
- Contract requirements
- Claims history
- Activities away from the premises
- Subcontractor information
Then compare:
- Annual premium
- Limit per occurrence
- Annual aggregate
- Policy excess
- Territorial limits
- Legal-cost treatment
- Work-away cover
- Tenant’s liability
- Landlord’s liability
- Cross-liability extension
- Subcontractor conditions
- Property in custody or control
- Product-liability inclusion
- Pollution terms
- Exclusions
- Claims-notification period
A quotation that costs less may contain a lower limit, higher excess or narrower business description.
Verifying the Insurer and Intermediary
Liability business should be placed with appropriately licensed insurers and intermediaries.
The Insurance Regulatory Authority maintains a 2026 licensed-entities register and identifies liability as a recognised class of general insurance business. Customers can use the current register to verify the insurer, agent or broker before purchasing cover. (Insurance Regulatory Authority)
Confirm:
- Name of the underwriting insurer
- Name of the intermediary
- Policy period
- Business description
- Insured locations
- Liability limit
- Premium payment channel
- Certificate or policy schedule
How Imana Helps Businesses Arrange Public Liability Insurance
Imana Insurance Agency Kenya Ltd helps SMEs, property owners, contractors, professional firms and organisations compare Public Liability Insurance quotations from suitable insurers.
The process includes:
- Understanding the business activities.
- Identifying third-party exposures.
- Reviewing contractual requirements.
- Selecting an appropriate liability limit.
- Preparing accurate quotation information.
- Comparing premiums, excesses and extensions.
- Coordinating policy issuance.
- Supporting policy changes and renewals.
- Providing claims guidance after an incident.
Imana can also help arrange related covers such as:
- WIBA
- Employer’s Liability
- Product Liability
- Professional Indemnity
- Contractors All Risks
- Fire and Allied Perils
- Business Interruption
- Commercial Motor
- Cyber Insurance
- Group Medical
- Goods in Transit
- Property Insurance
Public Liability Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Imana serves businesses around:
- Westlands
- Parklands
- Riverside
- Lavington
- Kitisuru
- Gigiri
- Runda
- Muthaiga
- Nairobi CBD
- Industrial Area
- Other parts of Kenya through digital channels
Call or WhatsApp: +254 796 209 402
Website: Imana.co.ke
Compare quotations. Understand the liability limits. Choose suitable protection. Let Imana handle the rest.
Frequently Asked Questions
What does Public Liability Insurance cover?
It generally covers eligible legal liability for accidental bodily injury, death or property damage affecting third parties, together with approved legal expenses.
Is Public Liability Insurance compulsory in Kenya?
It is not compulsory for every business, but it may be required by a contract, lease, tender, client, landlord, regulator or venue.
Does it cover employees?
Employee workplace injuries are generally addressed through WIBA and Employer’s Liability insurance rather than Public Liability Insurance.
Does it cover customers who slip and fall?
It may, where the business is legally liable and the incident falls within the policy terms.
Does it cover damage to customer property?
It may cover accidental third-party property damage, subject to exclusions such as custody-and-control restrictions.
Does it cover defective products?
A separate Product Liability section may be required for injury or damage caused by products supplied by the business.
Does it cover professional mistakes?
No. Professional Indemnity Insurance is normally required for claims arising from negligent advice, designs, errors or omissions.
Does it cover motor accidents?
Liabilities arising from use of a vehicle are generally addressed through Motor Insurance.
Can contractors buy Public Liability Insurance?
Yes. Contractors may arrange standalone cover or obtain third-party liability protection within Contractors All Risks Insurance.
Can a landlord require a tenant to have it?
Yes. Commercial leases may require tenants to maintain a stated level of Public Liability Insurance.
How much cover should a business buy?
The appropriate limit depends on visitor numbers, activities, contractual requirements, surrounding property and potential claim severity.
Can Imana compare Public Liability Insurance quotations?
Yes. Imana can help businesses compare premiums, liability limits, excesses, extensions and exclusions from suitable insurers.
The Bottom Line
Every customer, visitor, supplier or contractor who enters your premises creates a potential liability exposure.
Good safety practices reduce the chance of an accident, but they cannot eliminate every risk.
Public Liability Insurance provides an important financial safety net where a third party alleges that your premises, employees or business activities caused accidental injury, death or property damage.
Before buying:
- Identify who visits your premises
- Review your business activities
- Check your contracts
- Select an adequate liability limit
- Compare excesses and exclusions
- Confirm whether work away from the premises is covered
- Maintain strong safety and incident records
You may not be able to predict who will make a claim or when an accident will happen—but you can prepare your business for the financial consequences.
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call or WhatsApp: +254 796 209 402
Public Liability Insurance premiums, limits, excesses, extensions, territorial scope and exclusions vary between insurers. This article provides general information and is not legal advice. Obtain a current written quotation, policy schedule and complete policy wording before purchasing cover.