- Author: Raymond
- Category: Personal Accident Insurance in Kenya
How Much Does Personal Accident Insurance Cost in Kenya?
Personal Accident Insurance in Kenya can start from about KSh 1,800 a year for KSh 500,000 accidental death cover. Compare seven benefit options up to KSh 10 million and get a quote through Imana.
Website: www.imana.co.ke
MyKava: www.mykava.co.ke
Compare Personal Accident Insurance:
https://imana.co.ke/
Personal Accident Insurance in Kenya can be relatively affordable compared with many other forms of insurance.
Based on the illustrative premium schedule used for this guide, annual premiums range from:
KSh 1,800 to KSh 25,000
depending on the benefit limit selected.
The corresponding Accidental Death and Permanent Total Disability benefits range from:
KSh 500,000
up to:
KSh 10,000,000
The policy may also include:
- Temporary Total Disability
- Accident Medical Expenses
- Funeral Expenses
subject to the insurer's wording.
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Corporate and other insurance classes.
To compare Personal Accident options:
https://imana.co.ke/
Quick Answer: Personal Accident Insurance Premiums in Kenya
Based on the illustrative rate card:
Option 1: KSh 1,800 annually
Option 2: KSh 2,700 annually
Option 3: KSh 3,600 annually
Option 4: KSh 5,600 annually
Option 5: KSh 13,000 annually
Option 6: KSh 20,000 annually
Option 7: KSh 25,000 annually
The higher the benefit level, the higher the annual premium.
Option 1 — KSh 500,000 Personal Accident Cover
Annual premium:
KSh 1,800
Benefits:
Accidental Death: KSh 500,000
Permanent Total Disability: KSh 500,000
Temporary Total Disability: KSh 5,000
Accident Medical Expenses: KSh 50,000
Funeral Expenses: KSh 40,000
This is the lowest-cost option on the sample schedule.
Option 2 — KSh 800,000 Personal Accident Cover
Annual premium:
KSh 2,700
Benefits:
Accidental Death: KSh 800,000
Permanent Total Disability: KSh 800,000
Temporary Total Disability: KSh 8,000
Accident Medical Expenses: KSh 80,000
Funeral Expenses: KSh 50,000
Option 3 — KSh 1 Million Personal Accident Cover
Annual premium:
KSh 3,600
Benefits:
Accidental Death: KSh 1,000,000
Permanent Total Disability: KSh 1,000,000
Temporary Total Disability: KSh 10,000
Accident Medical Expenses: KSh 100,000
Funeral Expenses: KSh 60,000
For someone asking:
“How much does KSh 1 million Personal Accident Insurance cost in Kenya?”
the illustrative answer on this sample card is:
About KSh 3,600 per year.
Option 4 — KSh 2 Million Personal Accident Cover
Annual premium:
KSh 5,600
Benefits:
Accidental Death: KSh 2,000,000
Permanent Total Disability: KSh 2,000,000
Temporary Total Disability: KSh 15,000
Accident Medical Expenses: KSh 200,000
Funeral Expenses: KSh 75,000
This option provides a substantial increase in death and disability protection for a relatively modest annual premium.
Option 5 — KSh 5 Million Personal Accident Cover
Annual premium:
KSh 13,000
Benefits:
Accidental Death: KSh 5,000,000
Permanent Total Disability: KSh 5,000,000
Temporary Total Disability: KSh 30,000
Accident Medical Expenses: KSh 500,000
Funeral Expenses: KSh 90,000
This may be more relevant where the insured has:
- Dependants
- Higher income
- Significant debts
- Larger financial obligations
- Greater accident exposure
Option 6 — KSh 8 Million Personal Accident Cover
Annual premium:
KSh 20,000
Benefits:
Accidental Death: KSh 8,000,000
Permanent Total Disability: KSh 8,000,000
Temporary Total Disability: KSh 40,000
Accident Medical Expenses: KSh 800,000
Funeral Expenses: KSh 100,000
Option 7 — KSh 10 Million Personal Accident Cover
Annual premium:
KSh 25,000
Benefits:
Accidental Death: KSh 10,000,000
Permanent Total Disability: KSh 10,000,000
Temporary Total Disability: KSh 50,000
Accident Medical Expenses: KSh 1,000,000
Funeral Expenses: KSh 150,000
This is the highest benefit level on the sample rate card.
What Does Personal Accident Insurance Cover?
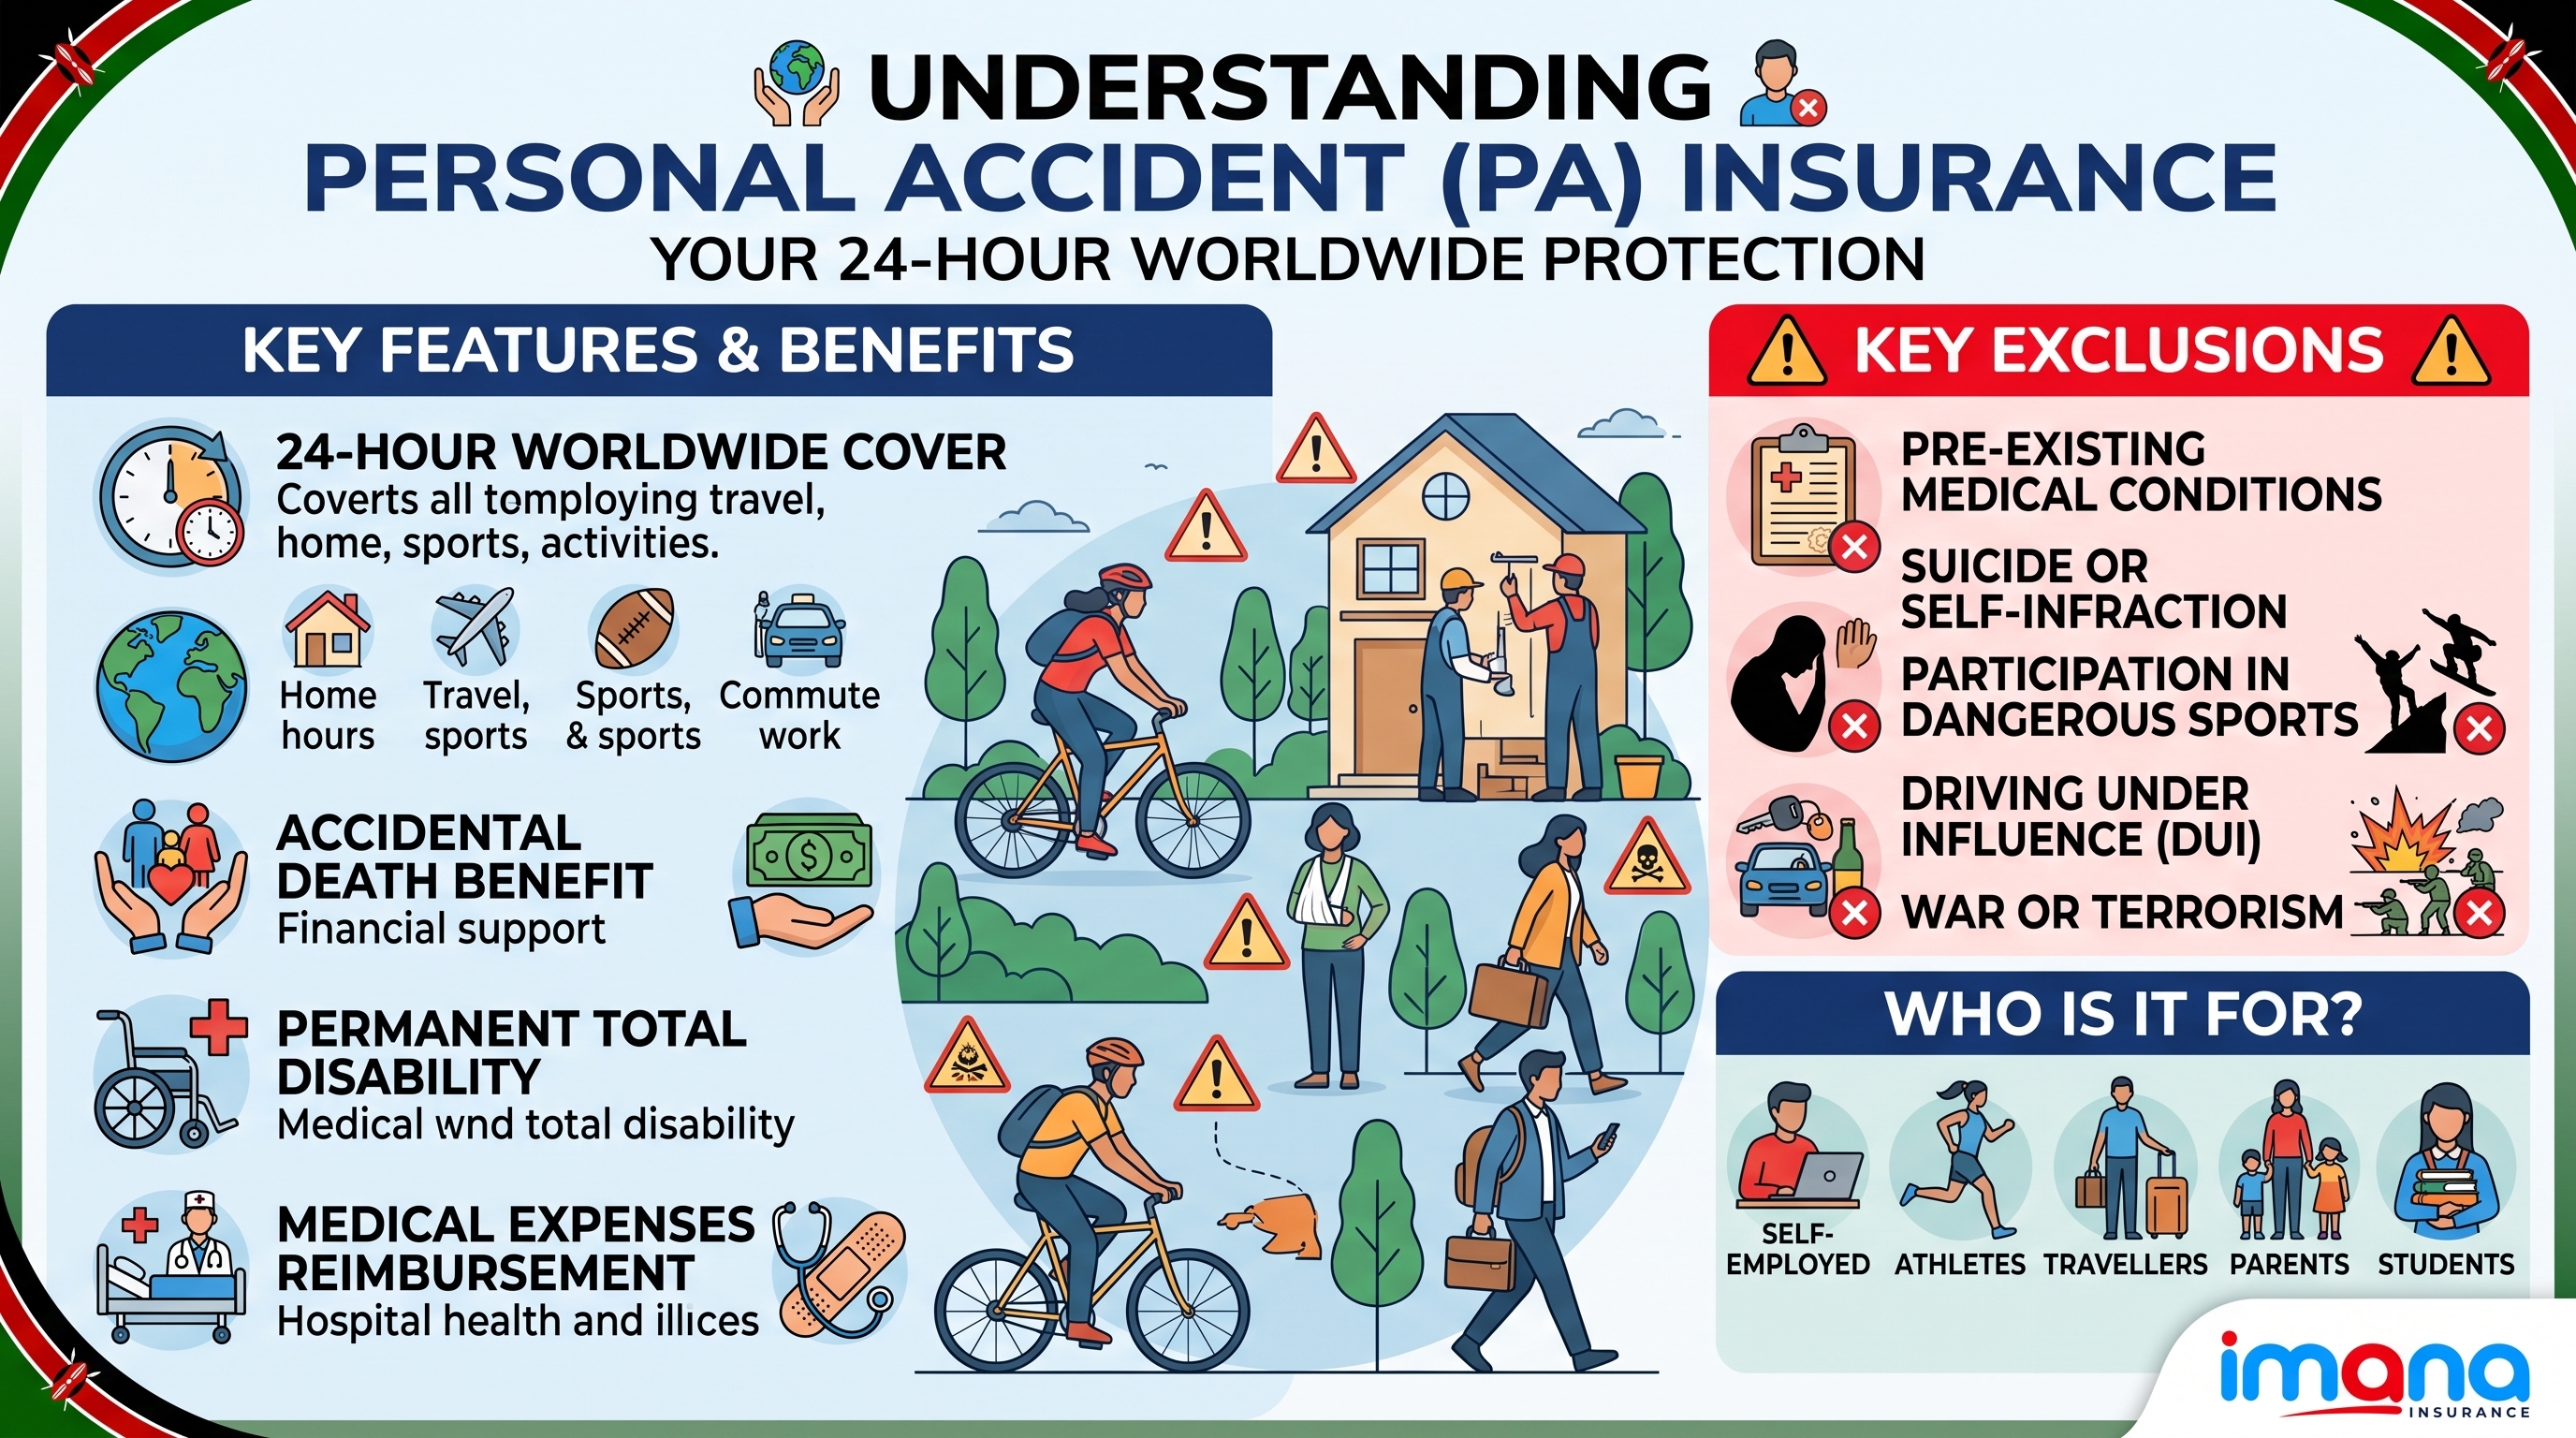
Personal Accident Insurance provides specified benefits when the insured suffers an accident covered by the policy.
The main benefits can include:
- Accidental Death
- Permanent Total Disability
- Temporary Total Disability
- Accident Medical Expenses
- Funeral Expenses
It is primarily an accident policy, not a general healthcare plan.
What Is Accidental Death Benefit?
Accidental Death benefit pays the stated sum where death results from an insured accident, subject to the policy.
For example:
Option 1: KSh 500,000
Option 3: KSh 1,000,000
Option 5: KSh 5,000,000
Option 7: KSh 10,000,000
The amount chosen should ideally reflect the financial impact the insured person's death could have on dependants or other obligations.
What Is Permanent Total Disability?
Permanent Total Disability, commonly called PTD, provides a benefit where an insured accident results in permanent total disability as defined by the insurer.
The benefit on the sample schedule mirrors the Accidental Death amount.
That means:
Option 1: KSh 500,000
through to:
Option 7: KSh 10 million
What Is Temporary Total Disability?
Temporary Total Disability, or TTD, applies where an insured accident temporarily prevents the insured person from carrying out normal duties, subject to policy wording.
The sample rate card shows benefit figures ranging from:
KSh 5,000 to KSh 50,000
depending on option.
However, the rate card alone does not specify whether those figures are:
- Weekly
- Periodic
- Monthly
- Overall limits
That detail must be confirmed in the final policy wording before purchase.
What Are Accident Medical Expenses?
This benefit helps meet eligible medical expenses arising from an insured accident.
The sample limits range from:
KSh 50,000
to:
KSh 1,000,000
depending on option.
Supporting documents may still be required for claims.
This is different from full Medical Insurance because the trigger is an accident rather than general illness.
Does Personal Accident Insurance Cover Funeral Expenses?
Yes, under the illustrative schedule.
The funeral limits range from:
KSh 40,000
to:
KSh 150,000
depending on the selected option.
This provides an additional funeral-related benefit following an eligible accidental death, subject to the policy.
How Much Does Personal Accident Insurance Cost Per Month?
For simple budgeting, the annual premiums work out approximately as follows when divided by 12.
Option 1: about KSh 150 per month
Option 2: about KSh 225 per month
Option 3: about KSh 300 per month
Option 4: about KSh 467 per month
Option 5: about KSh 1,083 per month
Option 6: about KSh 1,667 per month
Option 7: about KSh 2,083 per month
These are only monthly equivalents for budgeting.
The policy itself may still be payable annually unless the insurer specifically allows instalments.
How Much Is KSh 1 Million Accident Cover?
Based on this sample card:
KSh 3,600 per year
provides:
- KSh 1 million Accidental Death
- KSh 1 million PTD
- KSh 10,000 TTD
- KSh 100,000 Accident Medical Expenses
- KSh 60,000 Funeral Expenses
subject to policy terms.
How Much Is KSh 2 Million Personal Accident Cover?
The sample Option 4 costs:
KSh 5,600 annually
and provides:
- KSh 2 million Accidental Death
- KSh 2 million PTD
- KSh 200,000 Accident Medical Expenses
- KSh 75,000 Funeral Expenses
plus the stated TTD benefit.
How Much Is KSh 5 Million Personal Accident Cover?
The sample Option 5 costs:
KSh 13,000 annually
It includes:
- KSh 5 million Accidental Death
- KSh 5 million PTD
- KSh 500,000 Accident Medical Expenses
- KSh 90,000 Funeral Expenses
How Much Is KSh 10 Million Personal Accident Cover?
The sample Option 7 costs:
KSh 25,000 per year
It provides:
- KSh 10 million Accidental Death
- KSh 10 million PTD
- KSh 1 million Accident Medical Expenses
- KSh 150,000 Funeral Expenses
plus the stated TTD benefit.
How Should You Choose a Personal Accident Limit?
Do not start with:
“Which option is cheapest?”
Start with:
“What financial gap would an accident create?”
Consider:
- Annual income
- Number of dependants
- School fees
- Rent or mortgage
- Loans
- Existing Life Insurance
- Existing Medical Insurance
- Employer benefits
- Existing WIBA or Group PA cover
A low premium is attractive, but the benefit should still be meaningful.
Why Income Matters
Suppose someone earns:
KSh 100,000 per month
Annual income is:
KSh 1.2 million
A KSh 500,000 accident-death benefit is less than six months of gross income.
For someone supporting a family, that may not be enough.
A higher benefit may be more appropriate.
Why Debt Matters
Suppose someone has:
- KSh 2 million mortgage balance
- School fees obligations
- Dependants relying on income
A KSh 500,000 benefit may not provide sufficient financial protection.
Personal Accident limits should therefore have some relationship to:
Income + Dependants + Debt + Existing protection
Personal Accident Insurance Is Not Medical Insurance
These products solve different problems.
Personal Accident Insurance
Triggered primarily by accidental events.
It may pay:
- Lump-sum death benefit
- Disability benefit
- Accident medical expenses
- Funeral benefit
Medical Insurance
Can provide healthcare cover for:
- Illness
- Hospital admission
- Outpatient treatment
- Surgery
- Chronic conditions
- Maternity
depending on the plan.
A person may therefore hold both.
Personal Accident Insurance Is Not WIBA
WIBA is an employer-related statutory work-injury framework.
Personal Accident Insurance is a separate accident policy.
If someone is an employee, the employer's WIBA responsibilities are not automatically replaced by an individual PA policy.
The two can coexist.
Personal Accident Insurance Is Not Life Insurance
Life Insurance and Personal Accident Insurance are also different.
Personal Accident death benefits generally require death to arise from an insured accident.
Life Insurance may provide broader death protection according to its terms.
Someone supporting dependants may therefore consider:
- Personal Accident
- Life Insurance
- Medical Insurance
as separate layers of protection.
Who Should Consider Personal Accident Insurance?
Personal Accident cover may be useful for:
- Employees
- Self-employed professionals
- Business owners
- Drivers
- Riders
- Contractors
- Frequent travellers
- Field workers
- Parents
- Students
- People with dependants
The need is particularly relevant where an accident could stop income immediately.
Personal Accident Insurance for the Self-Employed
Self-employed people can be particularly exposed because an accident can affect both:
- Health
- Income
Examples include:
- Consultants
- Shop owners
- Freelancers
- Mechanics
- Technicians
- Drivers
- Traders
If the person cannot work, there may be no employer salary or paid sick leave.
Personal Accident Insurance can provide an additional financial buffer.
Personal Accident Insurance for Drivers and Riders
People who spend large amounts of time on the road face substantial accident exposure.
Examples include:
- Taxi drivers
- Commercial drivers
- Ride-hailing drivers
- Boda boda riders
- Delivery riders
- Sales representatives
Motor Insurance and Personal Accident Insurance should not be confused.
Motor Insurance protects the vehicle and specified motor liabilities.
Personal Accident Insurance protects the insured person according to the PA policy.
Personal Accident Insurance for Families
A family can also consider Personal Accident Insurance as part of broader financial protection.
The principal income earner may require a higher limit than someone with fewer financial obligations.
Where more than one family member needs cover, ask whether:
- Individual policies
- Family arrangements
- Group PA
are available from the insurer.
Personal Accident Insurance for Companies
Businesses can also arrange Group Personal Accident Insurance for employees.
That quotation may be based on:
- Number of employees
- Occupations
- Benefit limits
- Salaries
- Nature of business
- Claims history
Group PA should be quoted separately from WIBA.
What Usually Changes the Personal Accident Premium?
Pricing may vary because of:
- Age
- Occupation
- Nature of work
- Benefit amount
- 24-hour vs limited-time cover
- Territorial scope
- Hazardous activities
- Sports
- Group size
- Claims history
Someone working in an office may not receive the same underwriting terms as:
- A rider
- Construction worker
- Security officer
- Heavy-machine operator
Does Age Affect Personal Accident Insurance?
It can.
Insurers may:
- Apply maximum entry ages
- Restrict renewal ages
- Apply different terms for older applicants
The exact age requirements differ by insurer.
Always confirm eligibility before buying.
Does Occupation Affect the Premium?
Yes, it can.
Insurers assess accident exposure.
Higher-risk occupations may include:
- Construction
- Security
- Riding
- Driving
- Industrial work
- Manual labour
Some occupations may attract higher premiums, restrictions or special underwriting.
Does Personal Accident Cover High-Risk Sports?
Not automatically.
Activities such as:
- Motor racing
- Aviation
- Extreme sports
- Professional sport
- Hazardous recreational activities
may be restricted or excluded.
Disclose such activities before purchase.
Does Personal Accident Insurance Cover Illness?
Ordinarily, Personal Accident Insurance is designed around accidental injury.
It is not intended to cover ordinary illness such as:
- Malaria
- Flu
- Chronic disease
- Planned surgery
unless the policy specifically says otherwise.
For broader healthcare needs, consider Medical Insurance separately.
Can Personal Accident Insurance Cover You 24 Hours a Day?
Some products may provide 24-hour accident protection.
Others may have occupational, territorial or activity restrictions.
Always confirm:
- When cover applies
- Where it applies
- Occupational restrictions
- Travel limits
before relying on the policy.
What Information Is Needed for a Personal Accident Quote?
For an individual quotation, insurers may ask for:
- Full name
- Date of birth
- National ID or Passport
- Occupation
- Nature of work
- Benefit limit required
- Cover period
- Whether 24-hour cover is required
- Next of kin or beneficiary information
- Start date
For Group PA, insurers may request:
- Staff count
- Occupations
- Benefit limits
- Salary information
- Claims history
What Should You Compare Before Buying?
Do not compare premium only.
Check:
- Accidental Death benefit
- PTD benefit
- TTD definition
- Accident Medical limit
- Funeral Expenses
- Exclusions
- Age limits
- Occupational restrictions
- Territorial scope
- 24-hour or duty-only cover
- Claims documentation
Two Personal Accident policies costing similar amounts can still have materially different terms.
How to Buy Personal Accident Insurance in Kenya
Step 1
Decide the benefit amount you want.
Step 2
Provide your age and occupation.
Step 3
Compare available options.
Step 4
Review:
- Death benefit
- PTD
- TTD
- Medical limit
- Funeral benefit
- Exclusions
Step 5
Select the appropriate option.
Step 6
Complete the required application and payment.
Step 7
Receive the policy documentation subject to insurer processing.
Start here:
https://imana.co.ke/
Why Compare Personal Accident Insurance Through Imana?
Different insurers may provide different:
- Premiums
- Benefit limits
- Occupation classes
- Medical-expense limits
- TTD structures
- Age limits
- Exclusions
Comparison helps the customer understand what they are actually buying.
The goal should be:
Suitable protection at a reasonable premium
rather than simply:
The cheapest Personal Accident policy available.
Frequently Asked Questions
How much does Personal Accident Insurance cost in Kenya?
On the illustrative schedule used for this guide:
KSh 1,800–25,000 annually
depending on the selected benefit limit.
What is the cheapest option?
Option 1 costs:
KSh 1,800 annually
with KSh 500,000 Accidental Death and PTD benefits.
How much is KSh 1 million Personal Accident cover?
Approximately:
KSh 3,600 annually
on the sample schedule.
How much is KSh 2 million cover?
Approximately:
KSh 5,600 annually
How much is KSh 5 million Personal Accident Insurance?
Approximately:
KSh 13,000 annually
How much is KSh 8 million cover?
Approximately:
KSh 20,000 annually
How much is KSh 10 million Personal Accident Insurance?
Approximately:
KSh 25,000 annually
Does Personal Accident Insurance pay medical expenses?
The sample options provide Accident Medical Expenses ranging from:
KSh 50,000 to KSh 1 million
depending on option.
Does it cover funeral expenses?
Yes, under this sample structure.
Benefits range from:
KSh 40,000 to KSh 150,000
Is Personal Accident Insurance the same as Medical Insurance?
No.
PA focuses on accident-related benefits while Medical Insurance covers broader healthcare needs subject to its policy.
Is Personal Accident Insurance the same as WIBA?
No.
WIBA relates to qualifying employment-related injury and occupational disease exposure.
Where can I compare Personal Accident Insurance?
Start at:
https://imana.co.ke/
How Much Does Personal Accident Insurance Cost in Kenya? Final Answer
Based on the illustrative schedule:
KSh 500,000 Accidental Death/PTD
→ KSh 1,800 annually
KSh 800,000
→ KSh 2,700
KSh 1 million
→ KSh 3,600
KSh 2 million
→ KSh 5,600
KSh 5 million
→ KSh 13,000
KSh 8 million
→ KSh 20,000
KSh 10 million
→ KSh 25,000
The sample options can also include:
- Temporary Total Disability
- Accident Medical Expenses
- Funeral Expenses
The better question is not simply:
“How cheap can Personal Accident Insurance be?”
It is:
“How much protection would my family or I actually need after a serious accident?”
Compare the premium. Compare the benefit. Protect the person, not only the property.
Compare Personal Accident Insurance
www.imana.co.ke
MyKava:
www.mykava.co.ke
Author:
Raymond Momanyi – Founder & CEO, Imana Insurance Agency Kenya Ltd
The premiums and benefits in this article are illustrative and based on the supplied Personal Accident schedule. They are not universal market tariffs, binding quotations or guarantees of insurer acceptance. TTD definitions, age limits, occupation loadings, territorial scope, exclusions and premiums vary by insurer. Always read the final quotation and policy wording before buying.