- Author: Raymond
- Category: Car Insurance in Kenya
How Much Is Car Insurance in Kenya? 2026 and beyond Price Guide
Discover how much car insurance costs in Kenya in 2026. Compare third-party and comprehensive premiums, understand pricing factors, excesses, optional benefits and ways to get better value.
How Much Does Car Insurance Cost in Kenya?
Car insurance in Kenya can cost approximately KSh 5,000 per year for basic private-car third-party cover, while comprehensive insurance commonly starts from around KSh 25,000 annually or is calculated as a percentage of the vehicle’s value.
However, these figures are only indicative starting points.
The actual premium depends on:
- The type of vehicle
- Its current market value
- Private, commercial or PSV use
- The selected insurer
- The driver’s claims history
- The vehicle’s age and condition
- Optional benefits
- Policy excesses
- The period of insurance
Imana’s published motor-insurance content uses approximately KSh 25,000 annually as a starting reference for comprehensive cover, but the final rate remains subject to vehicle details and insurer underwriting. (imana.co.ke)
The safest way to establish the actual cost is to request several quotations using identical vehicle information and compare the premiums, benefits, excesses and exclusions.
Is Motor Insurance Compulsory in Kenya?
At minimum, vehicles used on public roads in Kenya must carry insurance against specified third-party risks, subject to the limited exceptions contained in law.
The Insurance (Motor Vehicle Third Party Risks) Act establishes the legal framework for insurance against liabilities arising from the use of motor vehicles. A 2026 High Court decision also restated that Section 4 makes third-party insurance mandatory for motor vehicles used on a road, subject to statutory exceptions. (Kenya Law)
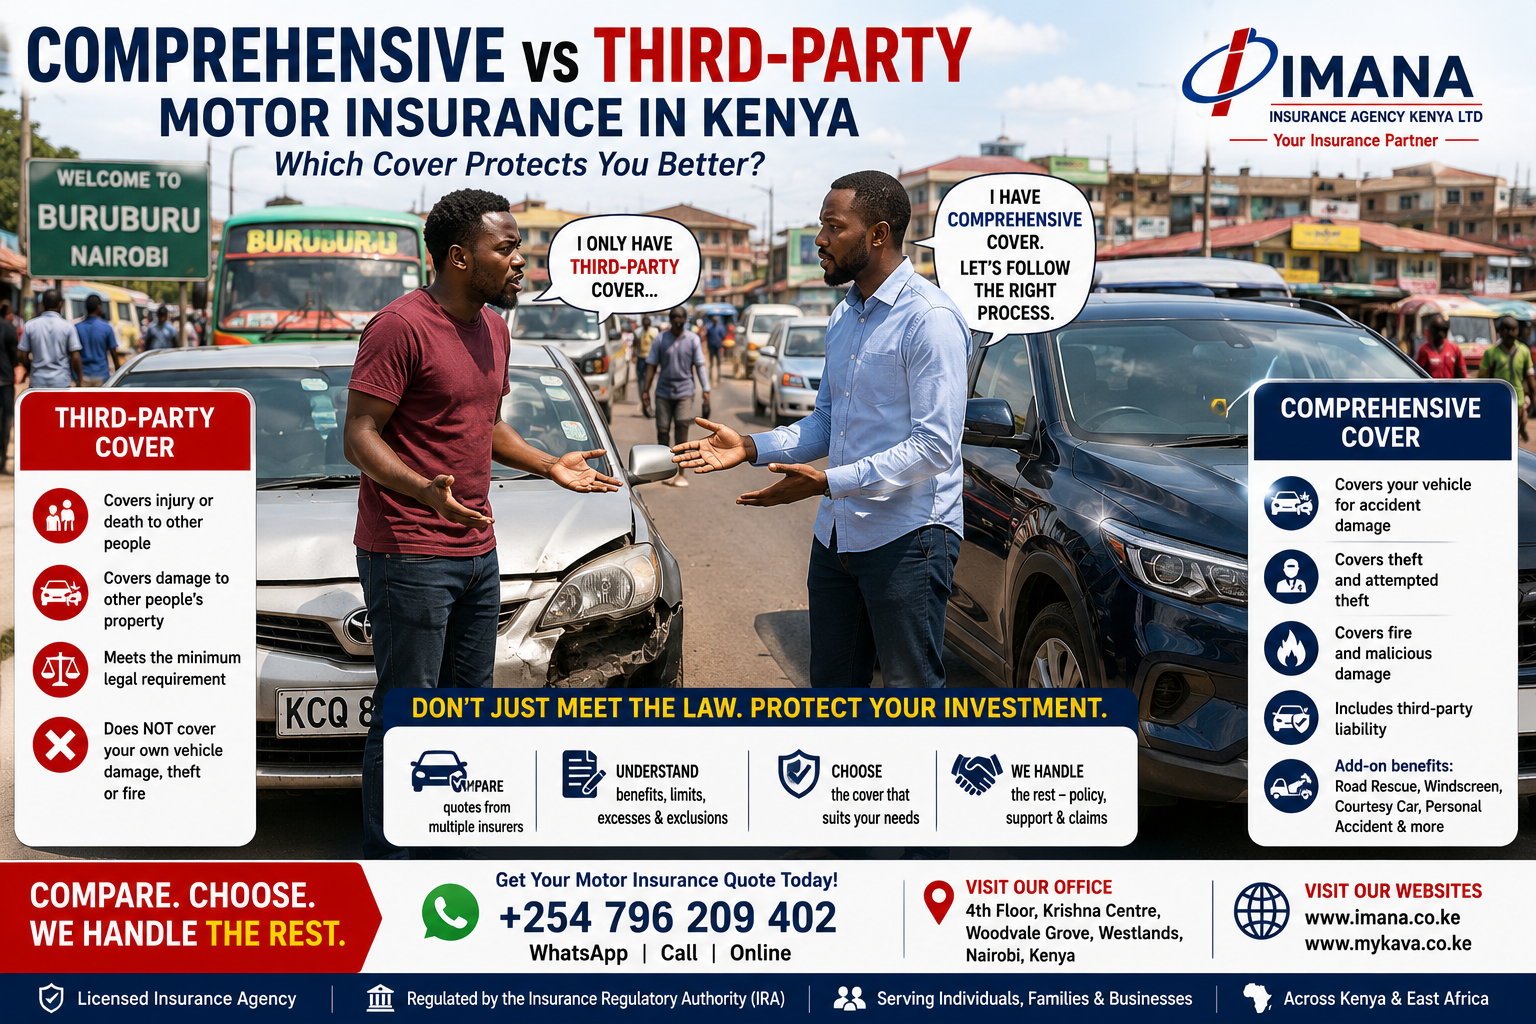
The legal minimum does not generally protect the value of your own car.
To insure your own vehicle against risks such as accidental damage, theft and fire, you normally need comprehensive insurance or another policy that expressly includes those risks.
Indicative Car Insurance Prices in Kenya
The following figures provide a practical guide rather than fixed market tariffs.
Private Car Third-Party Insurance
Private-car Third-Party Only insurance may start from approximately:
KSh 5,000 per year
The exact premium can differ between insurers and may be affected by:
- Period of cover
- Vehicle classification
- Policy fees and levies
- Passenger usage
- Underwriting terms
Some short-term third-party options may also be available for qualifying vehicle classes, but annual cover often provides better continuity and reduces the risk of forgetting to renew.
Comprehensive Private Car Insurance
Comprehensive car insurance may start from approximately:
KSh 25,000 per year
For many vehicles, the premium is calculated as a percentage of the current insured value, subject to the insurer’s minimum premium.
Indicative market rates can vary considerably, but a private vehicle may commonly be assessed within a broad range such as:
Approximately 2.5% to 8% of the vehicle value
This is not an official universal tariff. The percentage depends on the insurer, vehicle, driver, usage, claims record and selected benefits.
A KSh 25,000 minimum premium means that even where the percentage calculation produces a lower figure, the insurer may still charge at least KSh 25,000.
Commercial Vehicle Third-Party Insurance
Third-party insurance for a commercial vehicle may start from approximately:
KSh 7,500 per year
Commercial vehicles can include:
- Pickups
- Delivery vans
- Lorries
- Goods-carrying vehicles
- Company utility vehicles
The cost may increase according to the vehicle’s tonnage, carrying capacity, business activity and whether it carries the owner’s goods or transports goods for other people.
PSV Taxi, Uber and Bolt Insurance
Third-party insurance for a qualifying PSV taxi or ride-hailing vehicle may start from approximately:
KSh 7,500 annually
The final premium depends on the vehicle, seating capacity, intended operation and policy duration.
A car used for Uber, Bolt or taxi services must be insured under the appropriate PSV classification. A private-car policy may not respond correctly where the vehicle is being used to carry passengers for hire or reward.
Motorcycle and Boda Boda Insurance
Indicative annual third-party motorcycle premiums may start from approximately:
- Private motorcycle: KSh 3,500
- Delivery motorcycle: KSh 3,500
- Boda boda or PSV motorcycle: KSh 4,000
Rates depend on the motorcycle’s declared use, engine details and insurer.
Matatu, Bus and Other PSV Insurance
Matatu and bus insurance prices are normally customised.
The insurer may consider:
- Seating capacity
- Town or long-distance operation
- Vehicle value
- Route
- Cover period
- Passenger liability
- Claims history
- Comprehensive or third-party cover
Available periods may include short-term and annual options, depending on the insurer.
Heavy Commercial Vehicle Insurance
Premiums for prime movers, trailers, tankers, trucks and other heavy commercial vehicles are determined individually.
The quotation may depend on:
- Gross vehicle weight
- Type of goods carried
- Vehicle value
- Geographical area
- Long-distance or local operation
- Claims experience
- Number of vehicles
- Fleet-management controls
- Driver experience
- Dangerous or specialised cargo
Examples of Comprehensive Car Insurance Calculations
Comprehensive premiums become easier to understand when viewed as worked examples.
These examples use an illustrative rate of 3% of the vehicle’s value before levies, fees and optional benefits.
Car Valued at KSh 800,000
Calculation:
KSh 800,000 × 3% = KSh 24,000
Where the insurer has a minimum comprehensive premium of KSh 25,000, the payable base premium may become:
KSh 25,000
Car Valued at KSh 1,500,000
Calculation:
KSh 1,500,000 × 3% = KSh 45,000
The base premium would be approximately:
KSh 45,000
Car Valued at KSh 3,000,000
Calculation:
KSh 3,000,000 × 3% = KSh 90,000
The base premium would be approximately:
KSh 90,000
Car Valued at KSh 5,000,000
Calculation:
KSh 5,000,000 × 3% = KSh 150,000
The base premium would be approximately:
KSh 150,000
These examples are not insurer quotations. The final cost may increase or decrease depending on the rate, minimum premium, taxes, extensions and underwriting conditions.
Why Do Comprehensive Insurance Rates Differ?
There is no single comprehensive insurance rate used by every company.
One insurer may quote 2.5% of the vehicle’s value, while another may quote 3.5%, 4% or a higher percentage.
The difference can reflect:
- Vehicle repair costs
- Spare-parts availability
- Theft frequency
- Historical claims
- Driver profile
- Vehicle use
- Selected excess
- Insurer appetite
- Optional benefits
- Garage arrangements
A lower percentage is not automatically the best deal.
The policy with the lowest rate may have:
- A higher excess
- A smaller windscreen limit
- No excess protector
- Restricted garage access
- No courtesy-car benefit
- Lower towing limits
- More restrictive theft conditions
Compare the full policy offer rather than the percentage alone.
What Determines the Cost of Car Insurance in Kenya?
1. Vehicle Value
Vehicle value is one of the most important factors in comprehensive insurance.
A KSh 5 million vehicle usually costs more to insure than a KSh 1 million vehicle because the insurer faces a higher potential repair or total-loss settlement.
The insured value should reflect the vehicle’s reasonable current market value—not the price the owner wishes it were worth.
2. Type of Cover
Third-party insurance costs less because it primarily protects against covered liabilities to other people.
Comprehensive insurance costs more because it may cover:
- Damage to your vehicle
- Theft
- Fire
- Third-party liabilities
- Additional selected benefits
Britam’s comprehensive motor product, for example, advertises vehicle-damage protection together with windscreen, specified accessories, towing and other benefits, while its third-party product focuses on liabilities involving other persons and their property. (Britam)
3. Vehicle Use
A privately used family car presents a different risk from:
- A taxi
- Ride-hailing vehicle
- Delivery van
- School bus
- Tour van
- Matatu
- Long-distance truck
Vehicles used commercially normally spend more time on the road and may carry goods or passengers, increasing the potential exposure.
4. Make and Model
Some vehicle models are more expensive to repair because of:
- High spare-parts prices
- Limited availability of parts
- Specialised electronics
- Expensive headlights and sensors
- Advanced driver-assistance systems
- Aluminium or specialised body panels
- Limited approved repairers
The premium may reflect this repair complexity.
5. Year of Manufacture
An older car may be difficult to insure comprehensively where:
- Its value is too low
- Parts are unavailable
- It has existing damage
- Repair costs may exceed its market value
- Its mechanical condition is uncertain
An inspection or valuation may be required before acceptance.
6. Claims History
A driver or company with frequent previous claims may receive:
- A higher premium
- Increased excesses
- Restricted benefits
- Special underwriting conditions
- A declined quotation
Customers with a favourable claims history may qualify for more competitive terms or a no-claim discount. Britam, for example, advertises a no-claim discount that can build over claim-free years under its comprehensive product. (Britam)
7. Driver Age and Experience
Young or inexperienced drivers may attract an additional excess.
This does not always mean the annual premium will increase directly, but it can increase the amount payable by the policyholder during a claim.
8. Security Features
Insurers may consider:
- Vehicle tracking system
- Alarm
- Immobiliser
- Secure overnight parking
- Anti-theft devices
- Fleet-monitoring systems
High-value or theft-prone vehicles may be accepted only after specified security requirements have been met.
9. Geographical Area
A vehicle operating in a major city may face different risks from one operating mainly in a rural area.
Relevant factors may include:
- Traffic density
- Theft exposure
- Road conditions
- Flood risk
- Distance travelled
- Cross-border use
10. Optional Benefits
Adding extensions increases the level of protection and may increase the premium.
Common additions include:
- Excess protector
- Political violence and terrorism
- Courtesy car
- Road rescue
- Personal accident
- Increased windscreen cover
- Increased entertainment-equipment cover
- COMESA Yellow Card
What Additional Charges May Apply?
The quoted premium may include or be subject to:
- Insurance Training Levy
- Policyholders Compensation Fund levy
- Stamp duty
- Policy fees
- Instalment charges
- Valuation fees
- Tracking costs
- Optional-extension premiums
Ask whether the quotation presented is the final total payable.
Do not compare one insurer’s base premium against another insurer’s final premium inclusive of charges.
What Is a Motor Insurance Excess?
An excess is the amount the policyholder contributes towards an approved claim.
For example:
- Approved repair cost: KSh 300,000
- Applicable excess: KSh 30,000
- Policyholder contribution: KSh 30,000
- Eligible insurer contribution: KSh 270,000
This simplified example remains subject to all other policy terms.
A comprehensive policy can contain several excesses:
- Standard excess
- Theft excess
- Young-driver excess
- Inexperienced-driver excess
- Flood excess
- Third-party property-damage excess
A lower premium accompanied by a much higher excess may not provide better overall value.
What Is Excess Protector?
Excess protector is an optional benefit that may reimburse or remove specified excess amounts after an eligible claim.
It does not necessarily protect every excess.
Before adding it, confirm whether it applies to:
- Standard own-damage excess
- Theft excess
- Young-driver excess
- Special-perils excess
- Claims below a minimum amount
An Imana article illustrates how an excess may be calculated as a percentage of vehicle value, subject to a minimum amount, which shows why the applicable excess should be checked before buying. (imana.co.ke)
Is Comprehensive Insurance Worth the Cost?
Comprehensive insurance may be worth considering when:
- The vehicle has a high market value
- It is financed
- You depend on it for work
- It would be difficult to replace from savings
- Theft exposure is significant
- Repair costs are likely to be high
- It is an important business asset
Ask yourself:
If this vehicle were stolen or written off tomorrow, could I replace it without causing serious financial strain?
Where the answer is no, comprehensive insurance may offer important financial protection.
When Might Third-Party Insurance Be Enough?
Third-party insurance may be considered where:
- The vehicle has a low current market value
- Comprehensive insurance is uneconomical
- The owner can afford own repairs
- The car is used infrequently
- The owner only requires the legal minimum
- Comprehensive insurers decline the vehicle because of age or condition
The decision should be based on your capacity to absorb the loss—not simply the lower premium.
Can You Pay Comprehensive Insurance in Instalments?
Some insurers allow comprehensive premiums to be paid in instalments.
Britam’s MotiFlex, for example, advertises monthly, quarterly and semi-annual payment structures, with an initial payment starting from KSh 10,000 under its applicable terms. (Britam)
Instalment arrangements may involve:
- A minimum deposit
- Scheduled payment dates
- Additional financing or administrative cost
- Restrictions after missed payments
- Full third-party payment requirements
- Policy cancellation after default
Always calculate the total amount payable under the instalment option and compare it against the single-payment premium.
Can You Get Car Insurance for One Month?
Short-term third-party insurance may be available for selected vehicle classes.
Possible periods can include:
- One month
- Seven days
- Fourteen days
- Thirty days
- Annual cover
Availability depends on vehicle class, insurer and current underwriting rules.
Comprehensive motor insurance is generally arranged annually, although instalment-payment structures may help spread the cost.
Short-term insurance should not become a habit that creates gaps between certificates.
How Much Does Insurance Cost for an Imported Car?
Imported cars are assessed according to:
- Current Kenyan market value
- Registration status
- Customs and import documents
- Year of manufacture
- Spare-parts availability
- Vehicle inspection
- Duty-paid or duty-free status
- Intended use
An unregistered vehicle may require specialised arrangements before ordinary annual cover can be issued.
Duty-free vehicles can also be insured, but the valuation, ownership and total-loss settlement terms should reflect their customs status.
How Much Does Electric Vehicle Insurance Cost?
Electric-vehicle insurance is customised according to:
- EV value
- Battery replacement value
- Charger value
- Electric motor system
- Repair availability
- Vehicle use
- Towing and recovery requirements
- Selected extensions
No one universal EV premium applies across the market.
Specialist EV insurance may include battery protection, charging-equipment cover and out-of-charge recovery in addition to ordinary comprehensive risks.
Does a Cheaper Policy Mean Lower Quality?
Not always.
An insurer may offer a competitive rate because:
- It wants to grow that vehicle segment
- It has favourable claims experience
- It has negotiated repair arrangements
- The vehicle falls within its preferred market
- The customer has a strong claims history
However, a low quotation may also reflect:
- Higher excesses
- Reduced benefits
- Narrower extensions
- Restricted repair arrangements
- Lower accessory limits
That is why price should be compared together with policy value.
How to Get a Cheaper Car Insurance Quote Without Losing Important Protection
Compare Several Insurers
Different companies price the same vehicle differently.
Use an Accurate Vehicle Value
Overvaluation increases the premium but does not guarantee an inflated claim payment.
Consider a Voluntary Excess Carefully
A higher voluntary excess may reduce the premium, but only choose an amount you could afford during a claim.
Maintain a Good Claims Record
Avoid claiming for very small losses where the claim may cost less than the long-term effect on your record—but only after carefully considering the policy and repair cost.
Install Approved Security
A tracker or immobiliser may help satisfy theft-related underwriting requirements.
Choose Useful Add-Ons
Do not pay for extensions you do not need, but do not remove critical protection merely to reduce the premium.
Ask About Fleet Discounts
Businesses insuring several vehicles may qualify for negotiated fleet terms.
Consider Instalments
Instalments do not necessarily make insurance cheaper, but they may make the premium easier to manage.
What Documents Are Required for a Car Insurance Quote?
You may need:
- National ID or passport
- KRA PIN
- Vehicle logbook
- Registration number
- Make and model
- Year of manufacture
- Vehicle class
- Declared use
- Seating or carrying capacity
- Estimated value
- Existing policy
- Claims history
- Motor valuation for comprehensive insurance
- Financier information
Providing accurate information helps insurers issue realistic quotations.
Why a Motor Valuation Matters
A professional valuation helps establish:
- Current market value
- Vehicle condition
- Existing damage
- Accessories
- Correct vehicle details
- Recommended sum insured
Without an accurate value, the vehicle may be underinsured or overinsured.
Underinsurance can reduce a claim. Overinsurance can increase the premium without automatically increasing the amount payable after a loss.
What Should You Compare in Car Insurance Quotations?
Before selecting a quotation, compare:
- Total premium
- Vehicle value
- Premium rate
- Minimum premium
- Standard excess
- Theft excess
- Young-driver excess
- Excess protector
- Political violence and terrorism
- Windscreen limit
- Entertainment limit
- Road rescue
- Courtesy car
- Personal accident
- Approved garages
- Instalment options
- Claims requirements
Britam’s published motor pages demonstrate how comprehensive policies can include benefits such as windscreen protection, accessories, towing and no-claim discounts, while third-party cover remains focused on liabilities involving other people. (Britam)
How Imana Helps You Compare Car Insurance Prices
Imana Insurance Agency Kenya Ltd helps motorists compare quotations from several trusted insurance companies.
Available vehicle categories include:
- Private cars
- Commercial vehicles
- PSV taxis
- Uber and Bolt vehicles
- Matatus
- Buses
- Motorcycles
- Boda bodas
- Tuk-Tuks
- School buses
- Tour vans
- Tractors
- Prime movers
- Heavy commercial vehicles
- Duty-free vehicles
- Electric vehicles
The comparison can examine:
- Premiums
- Excesses
- Benefits
- Extensions
- Payment options
- Insurer requirements
- Claims procedures
Imana’s motor quotation platform is specifically designed to help customers compare comprehensive and third-party car-insurance options online. (imana.co.ke)
Request a Motor Insurance Quote
Visit:
https://imana.co.ke/motor-quote
Or contact Imana Insurance Agency Kenya Ltd:
Call or WhatsApp: +254 796 209 402
Office:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Car Insurance in Westlands, Nairobi and Across Kenya
Imana serves motorists around:
- Westlands
- Sarit Centre
- Westgate
- Parklands
- Riverside
- Spring Valley
- Lavington
- Kitisuru
- Gigiri
- Runda
- Muthaiga
- Nairobi CBD
- Buruburu
- Syokimau
- Karen
- Nairobi CBD
Vehicle owners elsewhere in Kenya can request quotations and submit documents digitally.
Frequently Asked Questions
How much is private-car third-party insurance in Kenya?
Indicative private-car TPO premiums commonly begin at around KSh 5,000 annually, although final pricing depends on the insurer and policy terms.
How much is comprehensive car insurance?
Comprehensive insurance may start from around KSh 25,000 annually or be calculated as a percentage of the vehicle value. (imana.co.ke)
What percentage of vehicle value is charged?
The rate varies by insurer, vehicle and risk. A broad indicative range may be approximately 2.5% to 8%, subject to a minimum premium and underwriting terms.
Is third-party insurance compulsory?
Yes. Vehicles used on public roads must have insurance meeting Kenya’s third-party-risk requirements, subject to statutory exceptions. (Kenya Law)
Does third-party insurance repair my car?
No. It generally protects against eligible liabilities involving other people, not damage to your own vehicle.
Does comprehensive insurance cover theft?
Comprehensive policies ordinarily include theft, subject to security conditions, excesses and exclusions.
Can I pay comprehensive insurance monthly?
Some insurers offer monthly or other instalment structures. Britam’s MotiFlex is one current example, subject to its applicable conditions. (Britam)
Is a motor valuation required?
A valuation is commonly required for comprehensive insurance to confirm the vehicle’s market value and condition.
Does an expensive car always have a higher premium?
Generally, a higher-value vehicle attracts a higher premium, although the rate also depends on model, use, repairs, claims and insurer appetite.
Can Imana compare quotations from several insurers?
Yes. Subject to insurer availability and underwriting criteria, Imana can help motorists compare comprehensive and third-party quotations.
The Bottom Line
There is no single answer to “How much is car insurance in Kenya?”
The cost ranges from approximately KSh 5,000 for basic private third-party protection to tens or hundreds of thousands of shillings for comprehensive insurance on higher-value or specialised vehicles.
The most important question is not only:
“What is the cheapest premium?”
It is:
“What financial loss will I still carry after buying this policy?”
Compare the premium, benefits, excesses and exclusions before making your decision.
Visit: www.imana.co.ke
Get a motor quote: https://imana.co.ke/motor-quote
Call or WhatsApp: +254 796 209 402
Know the price. Understand the protection. Insure the vehicle according to the loss you cannot comfortably carry.
The prices and percentages in this article are indicative starting points for general information. Final premiums, levies, minimums, excesses, benefits and acceptance terms depend on the insurer, vehicle and underwriting requirements. Obtain a current written quotation before purchasing cover.