- Author: Raymond
- Category: Corporate & SME Insurance in Kenya
Business Interruption Insurance Kenya | Imana
Understand business interruption insurance in Kenya, cover triggers, exclusions and recovery periods. Compare business insurance quotes with Imana.
Business Interruption Insurance in Kenya: Who Pays the Bills When Your Business Stops?
Author: Raymond Momanyi, Founder & CEO, Imana Insurance Agency Kenya Ltd
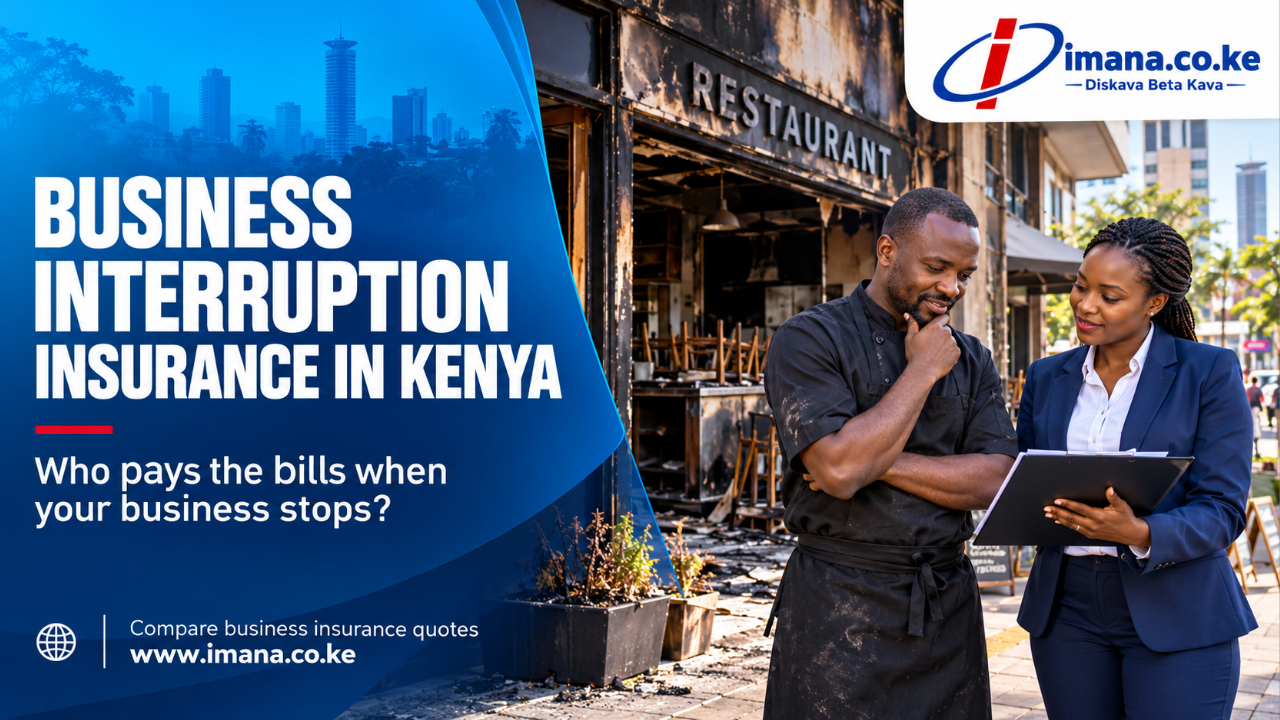
A fire destroys your restaurant in Westlands. Your property insurer agrees to pay for covered damage to equipment and fittings. You breathe a little easier.
Then another problem arrives: the restaurant cannot open.
Rent may still be due. Your employees need clarity about their salaries. Customers start eating elsewhere. Repairing the kitchen takes time, and reopening does not immediately bring every customer back.
Your assets may be insured—but is the income they generate protected?
Business interruption insurance addresses this financial gap. For Kenyan business owners, understanding the cover before a disruption can be as important as insuring the premises themselves.
What Is Business Interruption Insurance?
Business interruption insurance can compensate a business for specified financial losses when an insured event interrupts its operations. Traditional property-linked cover generally requires insured physical damage, such as fire damage, before the income-loss section responds.
The trigger, settlement basis, limits and exclusions must be checked in the policy. Having a fire policy does not automatically mean you have business interruption cover.
For example, GA Insurance Kenya describes a business interruption product responding to losses following fire damage, with benefits including gross profit and increased cost of working. This illustrates why the insured cause matters: the policy responds to its agreed triggers, rather than every reason a business might close.
Property Insurance and Business Interruption: What Is the Difference?
Property insurance addresses covered damage to insured buildings, stock, machinery or equipment. Business interruption addresses eligible financial consequences of the disruption.
Consider a hypothetical shop in Gikomba. A fire damages its insured stock and shelving. Replacing those items solves the physical-loss problem, but the owner may also lose trading income while the shop is restored.
The business needs to review both exposures. A stock replacement payment should not be assumed to include compensation for lost trading income.
Likewise, a landlord's building insurance should not be assumed to protect a tenant's business income. Each party should confirm its own insured interests and cover.
What Can Business Interruption Insurance Cover?
Depending on the selected wording, the insured basis may include loss of gross profit, revenue or rental income. A policy may also provide for eligible additional expenses incurred to reduce the interruption, and specified professional fees for preparing financial claim information.
Continuing costs such as rent or wages need careful discussion. They may be reflected in the insured financial basis; they are not necessarily separate benefits paid on top of the income-loss settlement.
Ask the insurer or intermediary to explain exactly how your chosen policy treats them. Insurance “gross profit” can differ from the figure your accountant uses in ordinary accounts.
Additional Expenses During Recovery
A business might need to rent temporary premises, hire replacement equipment or arrange alternative production after an insured loss.
Before committing to major expenditure, confirm what is recoverable and whether insurer approval is required. Standard increased-cost-of-working cover may limit recovery by reference to the insured loss avoided. Broader additional-cost cover, where available, needs its own review.
Kenyan Businesses That Should Consider the Cover
Use these hypothetical examples to think through your own exposure:
- A Westlands restaurant: a kitchen fire interrupts service while equipment is replaced and the premises restored.
- An Industrial Area manufacturer: covered damage stops a production line, and replacement equipment has a long delivery time.
- A Mombasa hotel: insured damage puts rooms out of use during a busy booking period.
- A Kisumu retailer: an insured incident affects the shop's ability to trade while restoration takes place.
These examples are prompts for an insurance review, not promises of claim payment. The cause of damage, property insured and financial-loss section must match the actual risk.
What Does Business Interruption Insurance Usually Not Cover?
Business interruption insurance is not a general guarantee that your business will remain profitable.
Low customer turnout, poor management, inadequate stock, competition and voluntary closure should not be assumed to qualify. A restaurant that repeatedly cannot supply meals on its menu has an operational problem; declining sales alone do not establish an insured interruption.
Other situations need specific checks:
- Power outages: ordinary supply failure is not automatically insured. Ask whether a utilities extension applies and what must cause the interruption.
- Machinery breakdown: property cover against fire should not be assumed to include mechanical breakdown or its income consequences.
- Supplier disruption: losses caused by damage at a supplier's premises may require a specified extension.
- Restricted access: closure because customers cannot reach the premises needs examination of any denial-of-access wording.
- Cyber incidents: review cyber insurance and its interruption terms separately.
- Political violence, terrorism, disease or government restrictions: do not assume these triggers are included; request written clarification.
An extension may have its own limits, waiting periods, geographical restrictions and exclusions. Cover for physical damage also does not automatically establish cover for every associated financial loss.
Choosing the Right Indemnity Period
The maximum indemnity period sets the outer time limit for eligible interruption losses following the insured event. It is different from the annual policy period.
Choose it by asking how long full trading recovery could take—not simply how long repairs might take.
Your recovery plan should consider debris clearance, rebuilding approvals, specialist equipment delivery, installation, restocking and winning customers back. A manufacturer waiting for imported machinery may face a different timeline from a shop able to relocate quickly.
Ask for available period options and compare them against a realistic recovery scenario. The cheapest quotation may provide too little recovery time.
How Much Business Interruption Cover Do You Need?
Start with the policy's financial definition and the selected indemnity period. Do not choose an arbitrary figure or copy the value of your stock.
Work with your accountant and intermediary to review turnover, relevant expenses, seasonality, expected growth and the time needed to recover. Reassess the figure when your business expands, changes activities or opens another branch.
Underinsurance can affect settlement where the wording applies an average or other adequacy condition. The calculation and consequences depend on the particular policy.
For a new business without a long trading history, ask what financial projections and records the insurer will accept.
How Much Does Business Interruption Insurance Cost in Kenya?
There is no single reliable price for every business. Request a quotation based on your activity, location, insured financial exposure, underlying property cover, indemnity period, extensions and risk controls.
For a useful comparison, ask insurers to quote on the same assumptions. A lower premium is difficult to assess if one quotation covers fewer causes, has a shorter recovery period or carries tighter limits.
Preparing for a Quotation
Prepare your business name, premises locations, description of operations, current insurance schedule and relevant financial information. Include your dependence on specialist equipment, key suppliers and any proposed temporary operating arrangements.
Financial statements, management accounts, sales records, payroll information and forecasts may be requested. Confirm the precise requirements and share sensitive records through an agreed secure channel.
What Should You Do After an Insured Disruption?
Prioritise safety and notify the insurer or intermediary promptly. Record the damage and interruption timeline, preserve relevant evidence where safe, and discuss mitigation and major recovery spending before committing to it.
Keep separate records of additional expenses, continuing costs, sales during the disruption and steps taken to resume trading. The insurer may request financial records and appoint specialists to assess the loss.
A closed business does not automatically receive its normal turnover as a payout. Settlement follows the insured basis and may account for saved expenses, continuing sales and business trends.
For general notification guidance, visit Imana's Insurance Claims Knowledge Centre or submit a claim notification.
Frequently Asked Questions
Can a small business buy business interruption insurance?
Ask about both traditional income-loss cover and suitable SME products. Some products offer fixed benefits instead of a calculated indemnity for actual financial loss. Britam Connect, for example, lists optional fixed-amount interruption benefits within its retail property solution. Compare the benefit amount and trigger carefully.
Can I buy cover after the disruption has happened?
New cover should not be expected to pay for an event or loss that has already occurred. Disclose existing damage and known circumstances when applying.
Does the cover pay every salary and loan instalment?
Do not assume it does. Request an explanation of how wages, continuing expenses, finance costs and loan repayments are treated under the actual wording.
Does reopening end the claim immediately?
Some policies address continuing insured trading effects during recovery, within the indemnity period. Check the definition and settlement provisions rather than assuming physical reopening ends every eligible loss.
Compare Business Insurance Quotes with Imana
Before your next renewal, ask one practical question: if an insured incident stopped trading, could your business afford the time needed to recover?
Imana Insurance Agency Kenya Ltd can help you compare business insurance quotations and review the relationship between your property cover and business interruption protection.
Request a corporate insurance quotation or contact Imana to discuss your premises, financial exposure and recovery needs.
Call/WhatsApp: +254 796 209 402
Visit: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya.
Websites: imanainsurance.com | imana.co.ke | mykava.co.ke
DISKAVA BETA KAVA.
Cover is subject to the insurer's policy wording, schedule, endorsements, limits and exclusions. Examples in this article are hypothetical.
Sources and Further Reading
- GA Insurance Kenya: Business Interruption Insurance — Kenyan product example.
- Britam Connect: Retail Property Insurance — example of optional fixed-amount interruption benefits.
- Allianz: Understanding the Risk of Underinsurance — general technical guidance on financial definitions and cover adequacy.
- Allianz: Business Interruption Events Wording — illustrative settlement provisions, not a Kenyan policy quotation.
- Allianz: Setting Indemnity Periods — general recovery-planning guidance.
Sources checked on 2 October 2026. International guidance explains general insurance concepts; Kenyan cover must be confirmed from the local insurer's wording.