- Author: Raymond
- Category: Insurance in Kenya
Before You Renew: Why the Right Insurance Cover Matters More Than the Cheapest Premium
Insurance is often treated like a routine transaction. A certificate expires, the owner pays for another one, and life moves on.
That approach may be convenient, but it can also be risky.
The real purpose of insurance is not simply to satisfy a legal requirement or receive a certificate. It is to protect your finances, your property, your family and your business when something unexpected happens.
Whether you own a private car, commercial vehicle, motorcycle, home or business, the question should not only be:
“How much is the premium?”
The better question is:
“What exactly will this policy protect when I need it most?”
Insurance Is Not One-Size-Fits-All
A vehicle, home, business and family do not face the same risks. That means one standard policy cannot protect everything effectively.
A private car owner may be concerned about theft, accidental damage and third-party liability. A commercial vehicle owner may also need protection against business interruption and the financial consequences of losing an income-generating asset.
A motorcycle rider may require protection against accidental damage, theft and third-party liabilities. A business owner may need WIBA, fire insurance, burglary insurance, goods-in-transit cover, professional indemnity and other specialised policies.
The right policy must reflect the real risks surrounding the person, asset or business being insured.
At Imana Insurance Agency Kenya Ltd, we help clients compare suitable options and understand the protection they are purchasing before committing their money.
Third-Party Insurance May Not Be Enough
Third-Party Only insurance is the basic legal requirement for vehicles operating on Kenyan roads. It primarily protects the insured against certain liabilities arising from injury, death or property damage caused to other people.
However, it generally does not pay for damage to your own vehicle.
This distinction becomes especially important for commercial vehicles.
Your truck, van, taxi, delivery vehicle or business motorcycle may be responsible for generating daily income. If it is damaged in an accident and you only have Third-Party cover, you may be left to finance the repairs from your own pocket.
The vehicle could remain in a garage for weeks while your business loses revenue.
Comprehensive insurance may provide broader protection against risks such as:
- Accidental damage
- Theft or attempted theft
- Fire damage
- Third-party liability
- Malicious damage, depending on the policy
- Windscreen damage, subject to policy limits
- Towing and recovery, where included
- Other optional benefits selected by the client
This is why commercial vehicle owners should not settle for minimum protection without first considering the financial consequences of losing the vehicle.
Protect the Vehicle That Protects Your Business
A commercial motor vehicle is not just a machine. It may be the bridge between your business and your customers.
It carries goods, transports employees, makes deliveries, supports contracts and keeps income flowing.
When that vehicle is involved in an accident, the cost goes beyond repairs. There may be missed deliveries, cancelled jobs, unhappy customers and delayed payments.
Comprehensive commercial motor insurance can help protect the asset at the centre of these operations.
The policy may cost more than Third-Party cover, but the additional protection can be far more valuable when a serious loss occurs.
The goal is not to buy the most expensive policy. The goal is to purchase cover that matches the vehicle’s value, usage and exposure to risk.
Motorcycle Owners Also Need More Than a Certificate
Motorcycles have become an essential part of transport and commerce across Kenya.
They are used for personal travel, delivery services, courier work, business operations and public transport. For many riders, the motorcycle is their primary source of income.
A basic policy may help meet legal requirements, but Comprehensive Motorcycle Insurance can offer broader protection for the motorcycle itself.
Depending on the insurer and policy terms, the cover may include accidental loss or damage, theft, fire and liabilities to third parties.
Motorcycle owners should confirm the correct class of use before purchasing insurance. A privately used motorcycle, a delivery motorcycle and a PSV or boda boda motorcycle may require different policy classifications.
Using the motorcycle for a purpose that was not disclosed to the insurer can create serious challenges during a claim.
Always provide accurate information about how the motorcycle is used.
Do Not Renew Motor Insurance Automatically
Many drivers renew with the same insurance company every year without checking whether better options exist.
There is nothing wrong with staying with the same insurer when the cover, pricing and service remain competitive. The problem comes when renewal becomes automatic and unquestioned.
Before renewing, compare the following:
1. The premium
Check whether another reputable insurer offers similar or better protection at a more competitive price.
Do not choose a policy solely because it is the cheapest. An unusually low premium may come with narrower benefits, higher excesses or restrictive conditions.
2. The policy benefits
Two policies described as “Comprehensive” may not offer exactly the same benefits.
One may include towing, windscreen cover and emergency medical expenses, while another may treat these as optional add-ons.
3. The excess
The excess is the portion of a claim that the policyholder may be required to pay.
A cheaper premium with a high excess can become expensive during a claim. Ask how much excess applies to accidental damage, theft, young drivers, inexperienced drivers and other situations.
4. The exclusions
Insurance policies contain exclusions that explain situations the insurer will not cover.
Read and understand them. Common issues may involve unlicensed drivers, drink-driving, unauthorised vehicle use, undisclosed modifications or use outside the declared class.
5. Claims support
The true value of insurance is revealed during a claim.
Ask whether your intermediary will help with the police abstract, assessment, garage coordination, documentation and follow-up with the insurer.
6. Optional benefits
Depending on your needs, you may consider:
- Excess Protector
- Political Violence and Terrorism cover
- Windscreen cover
- Entertainment system cover
- Road rescue
- Courtesy car
- COMESA Yellow Card
- Personal Accident cover
- Passenger liability
These benefits should be selected according to the vehicle, usage and budget.
The Cheapest Policy Is Not Always the Best Policy
Price matters. Nobody wants to overpay for insurance.
However, focusing only on the premium can create a false sense of savings.
A policy that saves you a few thousand shillings during purchase may cost you much more if it leaves out an essential benefit or carries a high excess.
The correct approach is to compare value, not just price.
A strong insurance decision considers:
Premium + Benefits + Excess + Exclusions + Claims Service + Insurer Reliability
This creates a clearer picture of what you are actually buying.
Why Working With an Insurance Intermediary Matters
The Kenyan insurance market has many companies offering different products, rates, limits and terms.
Comparing all these options alone can be confusing.
A licensed insurance intermediary helps you understand the available choices, identify suitable insurers and avoid purchasing cover blindly.
At Imana Insurance Agency Kenya Ltd, we help clients:
- Compare quotations from trusted insurance companies
- Understand policy benefits and exclusions
- Select suitable cover for their vehicles, homes, businesses and families
- Arrange digital insurance certificates
- Receive support during claims
- Review existing policies before renewal
Our role is not simply to sell a certificate. It is to help clients make insurance sense.
Protect More Than Your Vehicle
Insurance planning should extend beyond motor insurance.
A well-protected individual, family or business may require several forms of cover, including:
Home Insurance
A home contains years of work, memories and valuable belongings. Home insurance may protect the building and contents against risks such as fire, burglary and accidental damage, depending on the policy.
Health Insurance
Medical emergencies can place enormous pressure on family finances. Health insurance helps provide access to treatment while reducing unexpected out-of-pocket expenses.
Business Insurance
A business may require fire, burglary, money insurance, goods-in-transit, machinery breakdown, public liability or professional indemnity cover.
WIBA Insurance
Employers in Kenya are required to protect employees against occupational injuries and illnesses under the Work Injury Benefits Act.
Travel Insurance
Travel insurance may protect against medical emergencies, lost luggage, trip cancellation, delayed travel and emergency evacuation, subject to policy terms.
Life and Last Expense Insurance
These policies can help families manage the financial impact of death and funeral expenses.
The right combination depends on the risks surrounding your family, property and business.
Check Before You Renew
Insurance should never be treated as a rushed annual expense.
Before renewing, take time to review what you currently have, what has changed and what protection you may now require.
Your vehicle may have changed in value. Your business may have expanded. You may have added new drivers, entered new markets or started travelling across borders.
These changes can affect the type of cover you need.
Do not renew automatically.
Compare. Ask questions. Understand the policy. Confirm the insurer. Check the benefits. Review the excess. Disclose the correct use.
A few minutes spent reviewing your insurance today could save you from a major financial shock tomorrow.
Get Kavad With Imana Insurance
At Imana Insurance Agency Kenya Ltd, we help individuals, families and businesses compare insurance options and select protection that fits their real needs.
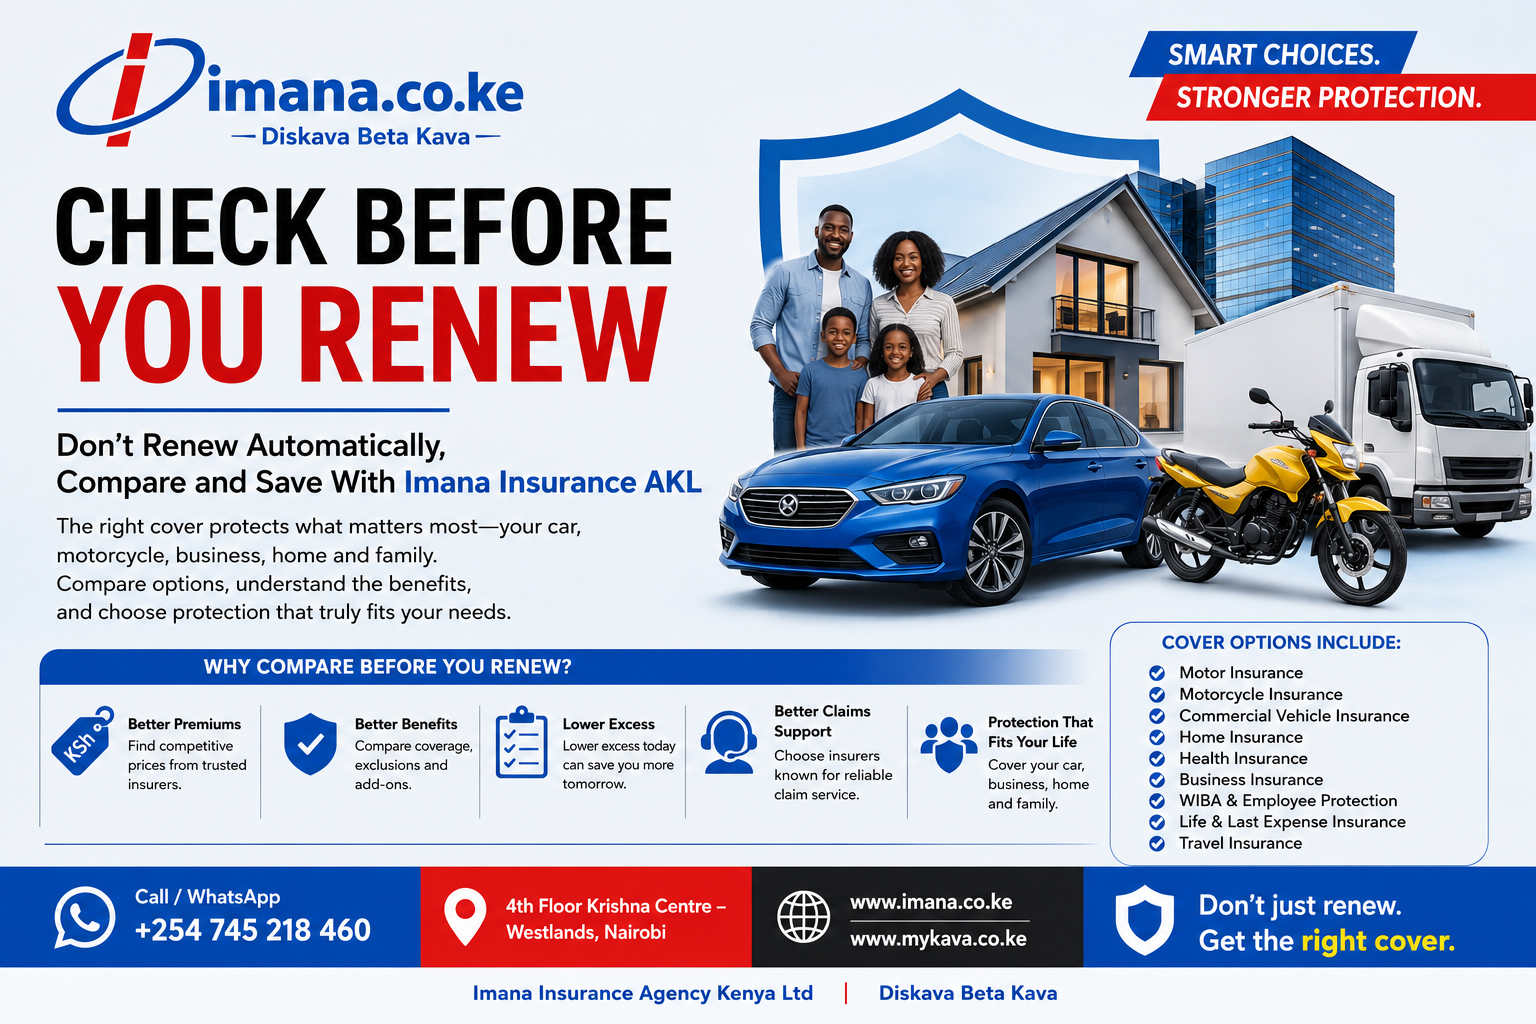
Whether you need Motor Insurance, Motorcycle Insurance, Commercial Vehicle Insurance, Health Insurance, Home Insurance, WIBA, Travel Insurance or Business Insurance, our team is ready to guide you.
Call or WhatsApp: +254 745 218 460
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Website: www.imana.co.ke | www.mykava.co.ke
Imana Insurance Agency Kenya Ltd — Diskava Beta Kava.
Why You Should Compare Motor Insurance Before Renewing in Kenya
Compare motor insurance before renewing in Kenya. Learn the difference between Third-Party and Comprehensive cover and how to protect your car, motorcycle or commercial vehicle.
Motor insurance Kenya, compare car insurance Kenya, comprehensive motor insurance, third-party insurance Kenya, motorcycle insurance Kenya, commercial vehicle insurance Kenya, insurance renewal Kenya, Imana Insurance, MyKava Insurance.