- Author: Raymond
- Category: Insurance in Kenya
7 Principles of Insurance in Kenya Explained
Understand the seven principles of insurance in Kenya and how good faith, indemnity, subrogation and other rules can affect your policy and claim.
The 7 Principles of Insurance in Kenya: What Every Policyholder Should Know
Insurance is not simply a receipt proving that you paid a premium. It is a contract built on honesty, financial interest, fair compensation and responsible conduct before and after a loss.
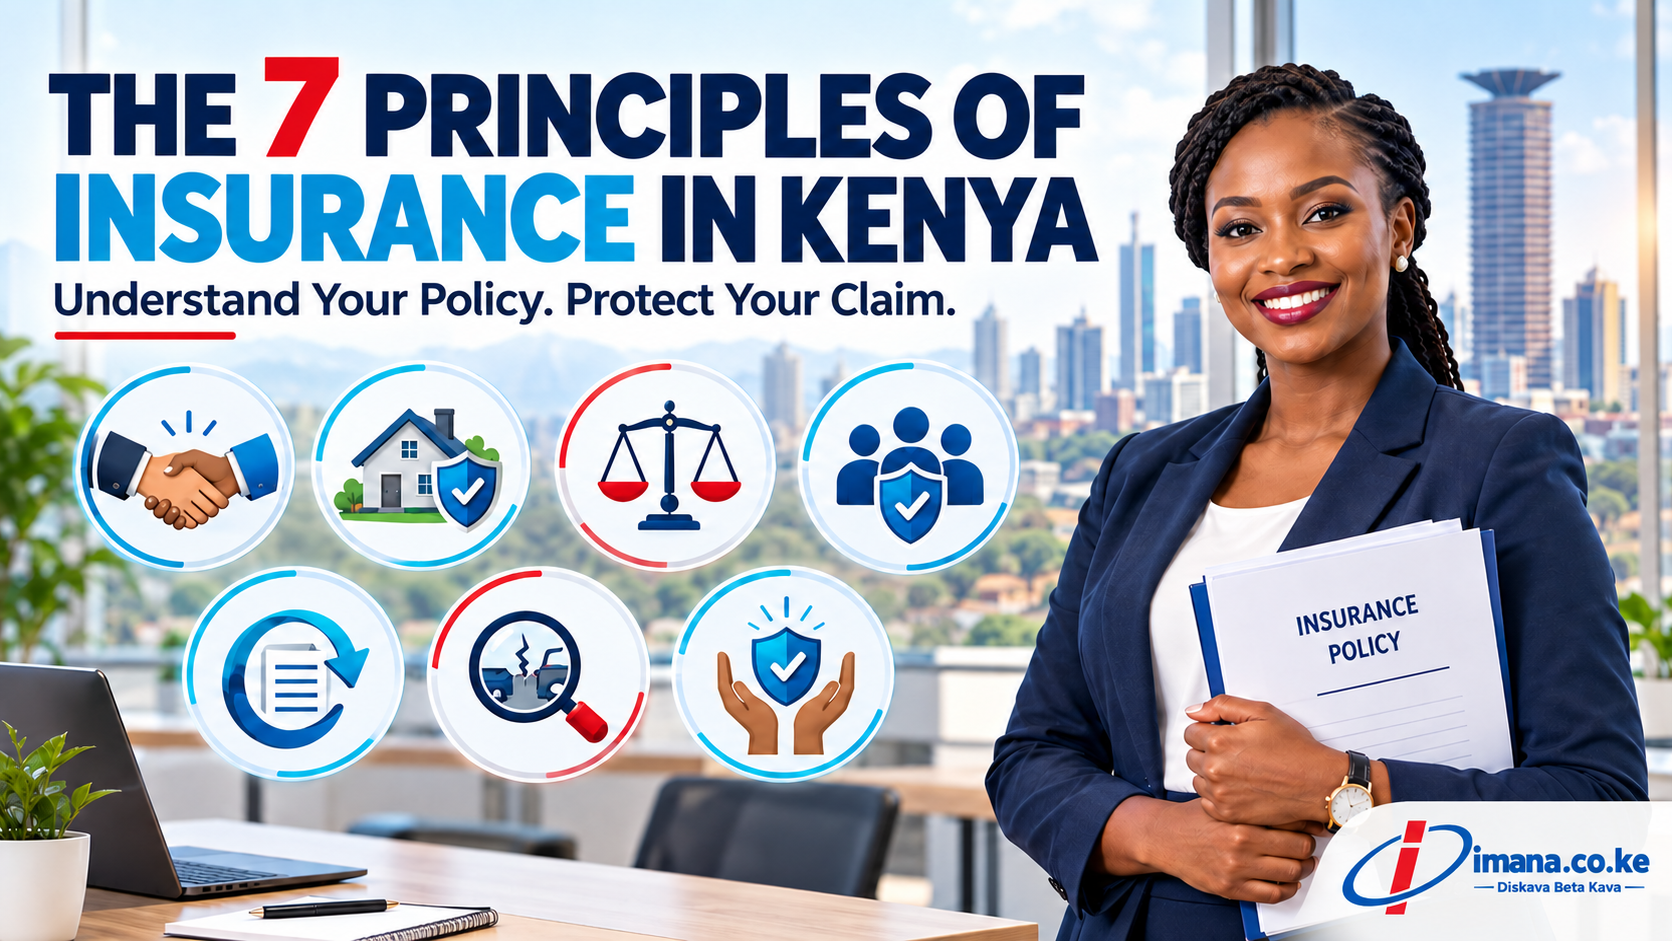
These foundations are commonly explained through the seven principles of insurance: utmost good faith, insurable interest, indemnity, contribution, subrogation, proximate cause and loss minimisation.
They may sound like classroom language, but they shape real decisions every day. They can influence whether an insurer accepts a risk, how a premium is calculated, which policy responds to a loss, how much is payable and whether a claim is admitted or declined.
This guide explains the seven principles of insurance using practical Kenyan examples from motor, medical, property, travel, marine and business insurance.
If you are comparing cover, start at ImanaInsurance.com. For product information and claims guidance, visit Imana Insurance Agency Kenya Ltd.
Quick answer: What are the seven principles of insurance?
The seven commonly recognised principles are:
- Utmost good faith
- Insurable interest
- Indemnity
- Contribution
- Subrogation
- Proximate cause
- Loss minimisation
Together, they help create fairness between the insurer and the insured. They discourage concealment, prevent people from profiting unfairly from losses, guide claim assessment and encourage policyholders to protect insured property from further damage.
The exact outcome of any claim still depends on the policy wording, schedule, exclusions, endorsements, evidence and applicable Kenyan law.
1. Utmost good faith
Utmost good faith means that the parties to an insurance contract should deal honestly and disclose information that is material to the risk.
A material fact is information that could reasonably influence an insurer’s decision to accept the risk, set the premium, impose a condition or decline the proposal.
Examples of material information
When buying motor insurance, relevant information may include:
- The vehicle’s correct use—private, commercial, PSV, school transport or hire
- Previous accidents and claims
- Significant vehicle modifications
- The correct year of manufacture and value
- Whether the vehicle is used outside Kenya
- The identity or category of drivers where requested
When applying for medical insurance, the proposal may ask about:
- Pre-existing medical conditions
- Current medication or ongoing treatment
- Previous operations or hospital admissions
- Pregnancy, where relevant to the benefits requested
- Ages and relationships of the people to be covered
For property or business insurance, material facts may include the nature of the business, construction materials, security measures, claims history, neighbouring risks, stock values and whether hazardous materials are kept on the premises.
Good faith also matters on the insurer’s side
An insurer or intermediary should explain the cover clearly, including significant exclusions, limits, waiting periods, excesses, warranties and claim requirements. A low premium can become expensive if the customer was never helped to understand what the policy excludes.
What happens when material information is withheld?
The outcome depends on the circumstances, policy and applicable law, but non-disclosure or misrepresentation can result in amended terms, a reduced claim, avoidance of the contract or rejection of a claim.
The safest approach is simple: answer proposal questions accurately and ask for help where a question is unclear. Do not assume that information is unimportant merely because it may increase the premium.
2. Insurable interest
Insurable interest means that the person taking insurance must have a recognised financial, legal or other insurable relationship with the subject of the policy. In simple terms, the policyholder should stand to suffer a genuine loss if the insured event occurs.
You normally have an insurable interest in:
- A vehicle you own
- A house or business property you own
- Stock belonging to your business
- Property for which you are legally responsible
- Your own life and, in appropriate circumstances, the life of another person
- An employee or contractual risk where the law or agreement creates responsibility
You cannot ordinarily insure a stranger’s vehicle or house merely because you would like to receive money if it is damaged.
Financed vehicles and property
Where a bank or other lender has financed an asset, both the owner and financier may have an interest in it. The policy schedule may therefore note the lender’s interest. If the asset is seriously damaged or written off, the claim settlement may have to account for the outstanding finance and the policy terms.
Why insurable interest matters
It separates insurance from gambling. The purpose of cover is to protect a genuine interest, not to create a financial reward from the destruction of property in which the claimant had no legitimate stake.
3. Indemnity
Indemnity means placing the insured, as far as money or an authorised repair can reasonably do so, in approximately the financial position occupied immediately before the covered loss. Insurance should compensate for an actual loss; it should not become a source of profit.
If an insured vehicle suffers covered repairs costing KSh 180,000, the insurer does not pay the full vehicle value simply because that is the sum insured. Subject to the policy, the settlement is based on the covered repair cost after applying any excess, limits, depreciation or other relevant terms.
If a building insured for KSh 20 million suffers covered damage of KSh 2 million, the normal starting point is the proven cost of the insured damage—not an automatic payment of KSh 20 million.
Sum insured is not always the claim amount
The sum insured is usually the maximum relevant limit, not a guaranteed payout. Claim settlement may be affected by:
- The actual value of the loss
- Policy excesses
- Underinsurance or average clauses
- Depreciation or betterment
- Applicable sub-limits
- Salvage
- Policy exclusions and conditions
Underinsurance can reduce a claim
If property is insured for substantially less than its correct value, an average condition may treat the policyholder as carrying part of the risk. The insurer may then pay only a proportion of an otherwise covered loss.
Accurate valuations are therefore not cosmetic paperwork. They help establish an appropriate sum insured and reduce disputes when a claim arises.
Does indemnity apply to every policy?
Not in exactly the same way. Life insurance and some personal accident benefits are generally benefit policies that pay an agreed amount when the stated insured event occurs, subject to the contract. They are not simply reimbursement of a repair bill or damaged asset.
4. Contribution
Contribution applies when the same interest and risk are covered by more than one relevant indemnity policy. It allows the insurers to share the claim in appropriate proportions instead of the policyholder recovering the same loss several times.
Imagine that the same warehouse stock is properly insured against fire under two policies. If a covered fire occurs, the existence of two policies does not normally entitle the owner to collect the full loss twice. The participating insurers may apportion the valid claim according to their respective obligations.
Why clients should disclose other insurance
Many claim forms ask whether another policy covers the same loss. Answer honestly. The question does not automatically cancel the claim; it helps insurers identify overlapping protection and apply the policy terms correctly.
Contribution should not be confused with ordinary co-insurance, where several insurers knowingly share a large risk from the beginning, or with benefit policies that may operate differently.
5. Subrogation
Subrogation allows an insurer that has compensated an insured loss to pursue recovery from a third party responsible for that loss, subject to the policy and law.
Suppose another driver negligently damages your comprehensively insured vehicle. Your insurer may settle the covered repairs and then seek recovery from the responsible party or that party’s insurer. The insurer is, in effect, exercising recovery rights connected to the loss it has paid.
Kenyan courts have repeatedly recognised subrogation as the mechanism through which an insurer that has indemnified an insured may pursue the wrongdoer, ordinarily through the insured’s legal rights and subject to procedural requirements.
What the policyholder should do
After a loss:
- Preserve police records, photographs, witness details and correspondence
- Give the insurer accurate information about the responsible party
- Do not sign an unapproved settlement or release that damages recovery rights
- Do not recover the same loss from both the insurer and the responsible party
- Cooperate with reasonable recovery requests
Subrogation helps place the cost of a loss on the responsible party where recovery is legally and practically possible. It can also protect the integrity of the insurance pool.
6. Proximate cause
Proximate cause means identifying the dominant, effective or most direct cause of a loss. A claim is not decided only by the final event in a chain; the insurer examines what truly set the loss in motion and whether that cause is covered or excluded.
Motor example
A storm causes a tree to fall directly onto a comprehensively insured car. The claim assessment considers the storm and resulting impact, together with the policy’s accidental-damage and weather-related terms.
Property example
An electrical fault starts a fire that damages business premises. The insurer investigates the fire, the electrical cause, compliance with policy conditions and whether any exclusion or warranty applies.
Travel example
A traveller misses a flight because of a documented medical emergency. The proximate cause may be the illness, but payment still depends on whether the illness and missed-departure circumstances fall within the selected travel policy.
Why evidence matters
Incident reports, police abstracts, fire-brigade reports, weather information, medical records, photographs, repair reports and witness statements can help establish the sequence and dominant cause.
Proximate cause is one reason clients should avoid guessing in a claim statement. State what happened accurately and preserve the available evidence.
7. Loss minimisation
Loss minimisation—also called mitigation of loss—means the insured should take reasonable steps to prevent an incident from worsening. Having insurance does not give anyone permission to ignore avoidable damage.
Reasonable action may include:
- Switching off the main water supply after a burst pipe
- Calling firefighters and moving people to safety during a fire
- Towing an accident-damaged vehicle to secure storage
- Covering an exposed roof temporarily to prevent rain damage
- Reporting a stolen bank card or phone promptly
- Seeking timely medical attention during a travel emergency
- Moving undamaged stock away from rising water where safe
The duty is to act reasonably, not heroically. Do not enter a burning building, cross dangerous floodwater or risk human life merely to save property.
Keep receipts for reasonable emergency costs and notify the insurer or intermediary as soon as practicable. Whether those costs are reimbursable depends on the policy.
How the seven principles work together during a claim
Consider a Nairobi business whose insured shop suffers fire damage:
- Utmost good faith asks whether the business and risk were described honestly when cover was arranged.
- Insurable interest confirms that the claimant had a legitimate interest in the premises, stock or equipment.
- Indemnity guides assessment of the actual covered financial loss.
- Contribution may apply if another policy covers the same interest and peril.
- Subrogation may allow recovery if a responsible contractor or neighbouring party caused the fire.
- Proximate cause identifies the dominant cause and whether it falls within the policy.
- Loss minimisation considers whether reasonable steps were taken to prevent further damage.
These principles do not replace the policy wording. They help explain the logic behind underwriting and claims decisions.
Common mistakes that can weaken an insurance claim
Giving the wrong use of a vehicle
Buying private motor insurance for a vehicle operating as a taxi, delivery vehicle, school vehicle or PSV can create a serious coverage problem. The certificate and policy should match the actual use.
Understating property or stock values
Lower values may reduce the initial premium, but they can lead to underinsurance and a proportionately reduced claim.
Hiding medical information
Where an insurer asks about medical history, answer fully and accurately. Concealing a known condition can affect underwriting and later claims.
Repairing or disposing of damaged property too quickly
Emergency action may be necessary, but obtain photographs, reports and insurer guidance where reasonably possible. Destroying evidence can make loss assessment difficult.
Admitting liability without guidance
After an accident, assist injured people and report the incident, but avoid making unauthorised promises of payment or signing settlements that may prejudice the insurer’s position.
Expecting insurance to create a profit
For indemnity policies, the goal is compensation for a covered loss—not a financial upgrade. Betterment, depreciation, excesses and policy limits may affect settlement.
What policyholders should check before buying insurance
Before accepting a quotation, confirm:
- The name of the insured and subject matter are correct
- The declared use and risk details are accurate
- The sum insured or benefit limit is suitable
- Major exclusions and waiting periods are understood
- Excesses and sub-limits are clear
- Required add-ons have been included
- Territorial limits match where the risk will operate
- The insurer is licensed for the relevant class of business
- The claim-notification process and emergency contacts are available
Do not compare premiums alone. Two quotations can have different limits, excesses, provider networks, exclusions, optional benefits and claim conditions.
Compare insurance quotations through ImanaInsurance.com or explore relevant cover below:
- Motor Insurance in Kenya
- Health Insurance in Kenya
- WIBA Insurance
- Travel Insurance
- Corporate Insurance Quotations
What to do when a claim occurs
Protect life first, then prevent further damage where it is safe to do so. Notify the insurer or intermediary promptly and follow the policy’s reporting requirements.
Depending on the claim, keep:
- Police abstracts and occurrence-book references
- Photographs and videos
- Medical reports and receipts
- Repair estimates
- Fire, incident or investigation reports
- Proof of ownership
- Purchase invoices and stock records
- Witness and third-party details
- Written communication from airlines, transporters or other service providers
Do not fabricate, alter or exaggerate a claim. Insurance depends on evidence and trust from proposal to settlement.
For claims guidance, use the Imana claims request page.
Frequently asked questions
Which is the most important principle of insurance?
Utmost good faith is often described as fundamental because insurance pricing and acceptance depend heavily on accurate information. In practice, all seven principles serve different functions and can become important at different stages of a policy or claim.
Can an insurer reject a claim because information was not disclosed?
Material non-disclosure or misrepresentation can affect a claim or policy. The outcome depends on what was asked, what was withheld, its relevance, the policy terms and applicable law. Give complete, accurate answers and request clarification before signing a proposal.
Can I insure the same vehicle with two companies and claim twice?
You should disclose overlapping insurance. Under indemnity principles, you cannot ordinarily recover more than the covered loss merely because two policies exist. Contribution may apply between the insurers.
Why does the insurer deduct an excess?
An excess is the portion of an admissible claim borne by the insured under the policy. Its amount or percentage should appear in the quotation, schedule or wording. Some covers offer an excess-protector extension subject to stated terms.
Does comprehensive insurance pay every type of loss?
No. Comprehensive motor insurance provides broader protection than third-party cover, but it still contains exclusions, limits, excesses, territorial conditions and optional extensions. Read the schedule and wording carefully.
Does indemnity mean the insurer must replace an old item with a new one?
Not automatically. Settlement may consider repairs, market value, depreciation, replacement terms, betterment and the basis of cover stated in the policy.
What if I disagree with an insurance claim decision?
Ask the insurer for a written explanation citing the relevant policy terms. Submit missing evidence or use the insurer’s complaints process. If the matter remains unresolved, consumers can consult the Insurance Regulatory Authority’s complaints channels or seek appropriate professional advice.
Compare cover before the loss happens
The seven principles of insurance are not abstract rules sitting in a textbook. They explain why honest disclosure matters, why valuations matter, why evidence matters and why a policyholder must still act responsibly after paying a premium.
The best time to understand your policy is before a claim—not when the vehicle is already damaged, the business is closed or a hospital is asking for authorisation.
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Cyber, SME/Corporate and other insurance classes.
Compare insurance quotations: imanainsurance.com
Insurance authority and product information: imana.co.ke
Travel, accommodation and insurance: mykava.co.ke
Call/WhatsApp: +254 796 209 402
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya
Compare. Understand. Buy the cover that fits the real risk.
Author: Raymond Momanyi, Founder & CEO, Imana Insurance Agency Kenya Ltd
Insurance is built on more than premium payments. Learn how utmost good faith, insurable interest, indemnity, contribution, subrogation, proximate cause and loss minimisation affect Kenyan policies and claims.
Editorial and compliance note: This article provides general insurance education and is not legal advice or a guarantee of claim payment. Policy benefits and claim decisions remain subject to the insurer’s underwriting, policy schedule, wording, exclusions, excesses, evidence and applicable Kenyan law.